애질리티로보틱스, 스팩 합병 완료하고 나스닥 상장, 신탁 61% 상환
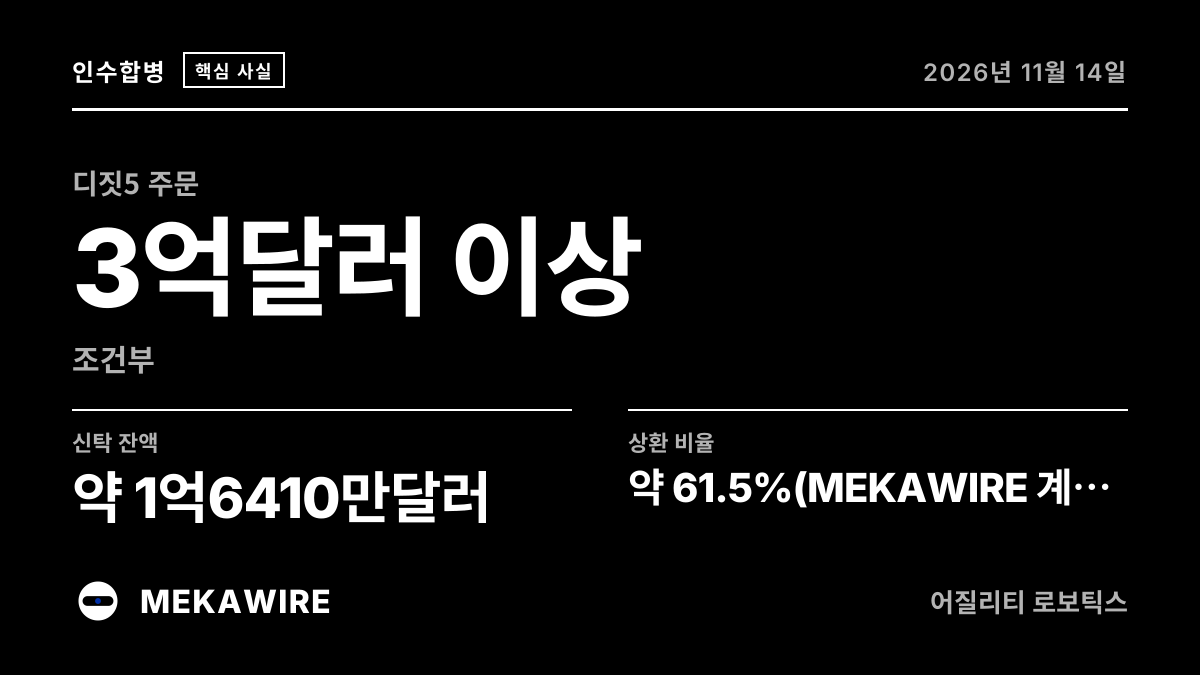
휴머노이드 디짓을 만드는 애질리티로보틱스가 4일 처칠캐피털11과 합병을 마치고 5일 나스닥에 AGLT로 상장했다고 6일 제출한 8-K 공시에서 밝혔다. 공모주 2545만주가 약 2억6180만달러에 상환돼 신탁에는 1억6410만달러가 남았다.
합병 후 발행주식은 2억4209만주다. MEKAWIRE 계산으로 신탁의 약 61%가 빠져나갔다.
애질리티로보틱스는 4일 보도자료에서 스팩(SPAC) 처칠캐피털11과의 합병을 완료했다고 밝혔고, 보통주와 워런트는 5일 나스닥에서 AGLT와 AGLTW로 거래를 시작했다. 6일 제출된 8-K에 따르면 클래스A 공모주 2545만1804주가 주당 약 10.287달러, 모두 약 2억6180만달러에 상환됐고 신탁 계좌에는 약 1억6410만달러가 남았다. 합병 후 발행주식 수는 2억4208만9880주다.
- 애질리티 지분가치
- 25억달러
- 합병계약
- 상환가
- 주당 약 10.287달러
- 8-K
- 상환 주식
- 2545만1804주
- 8-K
- 상환액
- 약 2억6180만달러
- 8-K
- 신탁 잔액
- 약 1억6410만달러
- 8-K
- 상환 전 신탁
- 약 4억2590만달러
- MEKAWIRE 계산
- 상환 비율
- 약 61.5%
- MEKAWIRE 계산
- 발행주식
- 2억4208만9880주
- 8-K
상환 전 신탁은 상환액과 잔액의 합.
2026년 11월 14일 기준
신탁 61% 상환
상환 전 신탁 규모는 약 4억2590만달러로, 이 중 61.5%가 빠져나갔다(MEKAWIRE 계산). 발행주식에 상환가를 곱하면 약 24억9000만달러로, 이는 거래가 기준 참고치이지 시가총액이 아니다. MEKAWIRE가 10월 30일 보도한 총조달액 약 4억6500만달러와 신탁 잔액이 일치한다.
회사는 6만5000시간 이상의 상업 운영, 디짓5에 대한 3억달러 이상 다년 주문(계약상 조건부), 연 최대 1만대 생산 설계의 로보팹 공장을 내세웠다. 고객으로 GXO, 셰플러, 토요타 캐나다, AGCO를 꼽았다. 자세한 이력은 애질리티 해설에 있다.
MEKAWIRE 분석
스팩 공모주 대부분이 상환돼 현금으로 돌아갔고, 거래를 떠받친 것은 폭스콘 주도 PIPE였다.
국내 휴머노이드 기업 대부분이 대기업 지분 투자나 비상장 투자로 자금을 마련하는 것과 달리 애질리티는 공개시장을 택했다. 회사 측은 상업 현장에 로봇을 실제 배치한 미국 유일의 순수 휴머노이드 상장사가 될 것으로 기대한다고 밝혔다. 11월 13일 제출된 첫 분기보고서는 합병 전 스팩의 9월 말까지 수치만 담았다. 애질리티 자체 실적이 처음 반영되는 공시가 현금 소진 속도를 가늠하는 기준이 될 전망이다.
- 2026년 11월 4일
- 11월 5일 나스닥 AGLT, AGLTW
- 2545만1804주, 약 2억6180만달러
- 약 1억6410만달러
- 약 61.5%(MEKAWIRE 계산)
- 2억4208만9880주
- 3억달러 이상, 조건부
매일 아침 8시, 로봇 산업 1면을 텔레그램으로
주요 기사와 신규 투자, 인수, 제휴를 한 장에 담아 보냅니다. 관심 기업 소식은 들어오는 대로 알립니다.
왜 중요한가
Agility's Nasdaq listing gives investors public-market exposure to a humanoid developer with active commercial deployments, according to the company. Redemptions of about 61.5% left $164.1 million in trust, making available funding and execution against over $300 million in milestone-based Digit 5 commitments central to the investment case. Those commitments require milestone delivery to translate into realized business, and the input provides no conversion schedule.
경쟁사 비교
Figure AI is identified as a direct warehouse-humanoid rival, while Boston Dynamics offers adjacent logistics competition through Stretch. Agility's GXO customer relationship, Schaeffler strategic relationship and AGCO pilot provide commercial reference points, but the input supplies no comparable rival deployment counts, pricing or performance data. Competitive leadership cannot be established from these facts.
밸류에이션 맥락
The supplied $2 billion figure is a disclosed valuation whose date and basis are unspecified. Current market capitalization requires a share price applied to the 242,089,880 shares outstanding after closing, and no share price is supplied. The separately reported $465 million SPAC merger figure has no defined basis in the input, so it cannot establish valuation or cash proceeds.
근거가 된 연구
No research papers are supplied, leaving technical performance and reliability unassessed. The cited 8-K, 10-Q and company releases document the transaction and commercial relationships, while the AGCO release concerns a pilot.
공급망 파급
NVIDIA is identified as a supplier, but the input specifies no components, contract terms or sourcing alternatives. GXO is a customer, Schaeffler a strategic partner and AGCO a pilot partner. Manufacturing capacity, unit costs and supplier concentration are undisclosed, limiting assessment of Digit 5 delivery economics.
지켜볼 신호
Watch milestone completion and revenue conversion from the over $300 million in Digit 5 commitments, alongside expansion of customer deployments and the AGCO pilot. Cash balance, operating burn and transaction costs will determine funding runway, since the $164.1 million trust balance alone is insufficient to calculate it. The input provides no delivery timetable or profitability metrics.
애널리스트 시각
The listing creates a public investment entry point, while milestone execution and deployment economics will determine the commercial case. With substantial trust redemptions and no supplied burn rate, margins or delivery schedule, the available facts support monitoring cash sufficiency and order conversion before judging the disclosed valuation.
따져봐야 할 질문
How much unrestricted cash remained after closing costs and other financing flows, and what operating runway does it support? What milestones, delivery dates and cancellation terms govern the over $300 million in Digit 5 commitments? What deployment economics and reliability data can GXO and the AGCO pilot establish?