Agility Robotics closes SPAC merger, lists as AGLT after 61% of trust redeemed
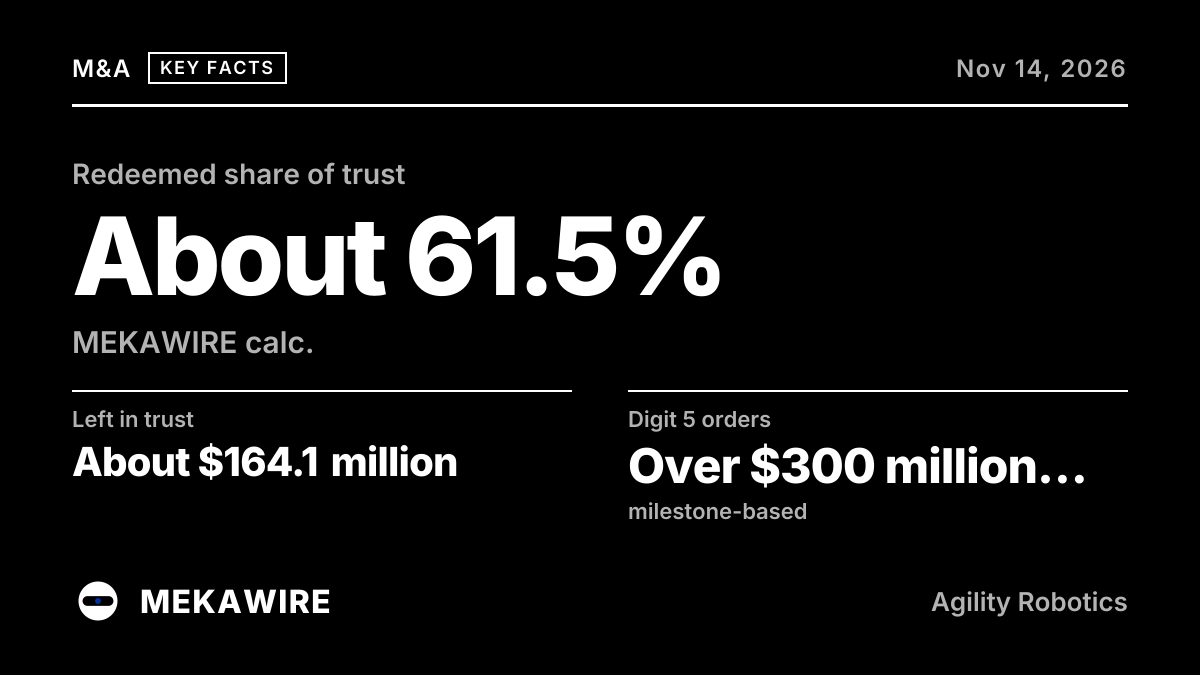
Agility Robotics completed its merger with Churchill Capital Corp XI on Nov 4 and began trading on Nasdaq as AGLT on Nov 5, according to an 8-K filed on Nov 6. Holders of 25.45 million public shares redeemed about $261.8 million, leaving $164.1 million in the trust, and the combined company had 242.1 million shares outstanding after closing.
By our calculation about 61% of the trust was redeemed. Agility said it expects to become the only US-listed pure-play humanoid company with active commercial deployments.
Agility Robotics, maker of the Digit humanoid, said in a press release dated Nov 4 that it had completed its business combination with Churchill Capital Corp XI, and its common stock and warrants began trading on Nasdaq on Nov 5 under AGLT and AGLTW. The 8-K filed on Nov 6 gives the closing numbers: holders of 25,451,804 Class A shares redeemed them at about $10.287 each, roughly $261.8 million, and about $164.1 million remained in the trust account. Together with the PIPE investment, that money paid transaction expenses and funds the company. After closing, 242,089,880 shares of common stock were outstanding.
What the filing settles
Shareholders approved the deal on Nov 2. The merger consideration was based on a $2.5 billion equity value for Agility, paid entirely in new shares valued at the redemption price. Each whole warrant can be exercised for one share at $11.50.
- Equity value for Agility
- $2.5 billion
- Merger agreement
- Redemption price
- About $10.287 per share
- 8-K
- Shares redeemed
- 25,451,804
- 8-K
- Cash redeemed
- About $261.8 million
- 8-K
- Left in trust
- About $164.1 million
- 8-K
- Trust before redemptions
- About $425.9 million
- MEKAWIRE calc.
- Redeemed share
- About 61.5%
- MEKAWIRE calc.
- Shares outstanding
- 242,089,880
- 8-K
Trust before redemptions = 261.8 + 164.1; redeemed share = 261.8 / 425.9.
As of Nov 14, 2026
On our arithmetic, the trust held about $425.9 million before redemptions, so about 61.5% was withdrawn (MEKAWIRE calc.). The 242.1 million shares multiplied by the $10.287 redemption price give about $2.49 billion; that is a reference value at the deal price, not a market capitalisation. Our Oct 30 story reported gross proceeds of about $465 million including the Foxconn-led PIPE and pre-closing equity; the filing's trust figure of $164.1 million matches it.
What Agility says it has
The release cites more than 65,000 hours of commercial operation, more than $300 million in committed multi-year orders for Digit 5 subject to contractual milestones, and RoboFab, a US plant designed for up to 10,000 robots a year. Named customers include GXO, Schaeffler, Toyota Motor Manufacturing Canada and AGCO, whose Digit pilot in Hesston, Kansas is expected to begin in 2027. Our Agility explainer has the company's full history.
MEKAWIRE analysis
The market funded Agility, but on public-market terms: holders of most public SPAC shares took their cash back, and the PIPE carried the deal.
With 61% of the trust withdrawn, public SPAC holders put in less than half of what they could have. The bull case is that Agility now has listed equity to pay for Digit 5 production before its $300 million in orders turn into revenue. The bear case is that those orders depend on milestones and that the first report of Agility's own results after the merger will show cash burn without the private-market cushion. Signals to watch: the first filing that reports Agility's own results after the merger (the 10-Q filed on Nov 13 covers only the SPAC through Sept 30), any Digit 5 delivery milestone, and the end of the lock-up period.
- Nov 4, 2026
- Nasdaq AGLT and AGLTW from Nov 5
- 25,451,804 shares, about $261.8 million
- About $164.1 million
- Over $300 million committed, milestone-based
- 242,089,880 after closing
- About 61.5% (MEKAWIRE calc.)
Why it matters
Agility's Nasdaq listing gives investors public-market exposure to a humanoid developer with active commercial deployments, according to the company. Redemptions of about 61.5% left $164.1 million in trust, making available funding and execution against over $300 million in milestone-based Digit 5 commitments central to the investment case. Those commitments require milestone delivery to translate into realized business, and the input provides no conversion schedule.
Rival analysis
Figure AI is identified as a direct warehouse-humanoid rival, while Boston Dynamics offers adjacent logistics competition through Stretch. Agility's GXO customer relationship, Schaeffler strategic relationship and AGCO pilot provide commercial reference points, but the input supplies no comparable rival deployment counts, pricing or performance data. Competitive leadership cannot be established from these facts.
Valuation context
The supplied $2 billion figure is a disclosed valuation whose date and basis are unspecified. Current market capitalization requires a share price applied to the 242,089,880 shares outstanding after closing, and no share price is supplied. The separately reported $465 million SPAC merger figure has no defined basis in the input, so it cannot establish valuation or cash proceeds.
Related papers
No research papers are supplied, leaving technical performance and reliability unassessed. The cited 8-K, 10-Q and company releases document the transaction and commercial relationships, while the AGCO release concerns a pilot.
Supply-chain implications
NVIDIA is identified as a supplier, but the input specifies no components, contract terms or sourcing alternatives. GXO is a customer, Schaeffler a strategic partner and AGCO a pilot partner. Manufacturing capacity, unit costs and supplier concentration are undisclosed, limiting assessment of Digit 5 delivery economics.
Signals to watch
Watch milestone completion and revenue conversion from the over $300 million in Digit 5 commitments, alongside expansion of customer deployments and the AGCO pilot. Cash balance, operating burn and transaction costs will determine funding runway, since the $164.1 million trust balance alone is insufficient to calculate it. The input provides no delivery timetable or profitability metrics.
Analyst view
The listing creates a public investment entry point, while milestone execution and deployment economics will determine the commercial case. With substantial trust redemptions and no supplied burn rate, margins or delivery schedule, the available facts support monitoring cash sufficiency and order conversion before judging the disclosed valuation.
Questions you should be asking
How much unrestricted cash remained after closing costs and other financing flows, and what operating runway does it support? What milestones, delivery dates and cancellation terms govern the over $300 million in Digit 5 commitments? What deployment economics and reliability data can GXO and the AGCO pilot establish?