德国Agile Robots完成5亿美元F轮融资,估值85亿美元,软银领投
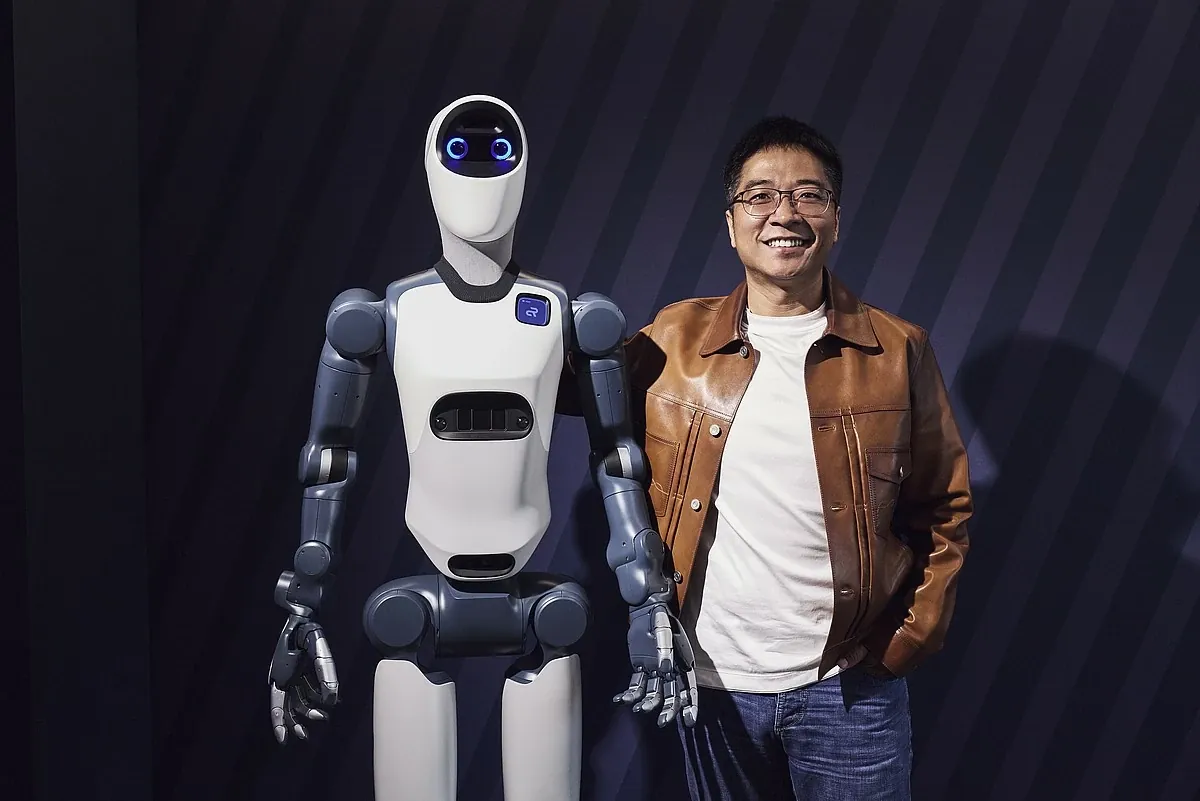
总部位于慕尼黑的Agile Robots于11月12日发布新闻稿称,完成由软银集团领投的5亿美元F轮融资,估值85亿美元,英伟达、日立和T.Capital参投。公司称累计融资约20亿美元,资金将用于扩大产能、进入重点市场并加强美国业务。按MEKAWIRE数据库统计,这是近120天第三大机器人融资。
Agile Robots SE于11月12日通过新闻稿宣布,完成5亿美元F轮融资,估值85亿美元。软银集团领投,英伟达、日立集团(日立及日立风投)和T.Capital参投。公司称累计融资约20亿美元。
年产万台人形机器人的工厂
公司表示,资金将用于提升产能、拓展重点市场和加强在美国的布局。其2026年初投产的慕尼黑近郊菲尔斯滕费尔德布鲁克工厂,年产能最高1万台足式和轮式人形机器人。公司称已在全球部署超过2万套机器人解决方案,员工逾3500人,其中研发人员超过2000人,旗下包括Franka Robotics等自动化企业。
这家公司于2018年从德国航空航天中心(DLR)孵化。软银愿景基金二期曾在2021年9月领投其2.2亿美元C轮,本轮金额为当时的2.3倍(MEKAWIRE计算)。新闻稿未说明85亿美元为投前还是投后估值。
- Re:Build
- 风险投资
- 21亿美元
- 10月27日
- Bedrock Robotics
- C轮
- 6亿美元
- 10月26日
- Agile Robots
- F轮
- 5亿美元
- 11月12日
- Agility Robotics
- SPAC合并毛募资
- 4.65亿美元
- 10月30日
- Path Robotics
- E轮
- 3亿美元
- 11月10日
仅含已核实的披露金额。
截至 2026年11月14日
MEKAWIRE 分析
资本给Agile Robots的定价,更像一家附带人形机器人期权的工业自动化供应商。
支撑这一判断的是2万套装机量和收购来的自动化业务,而1万台只是产能,并非出货。与优必选、智元等国内厂商公布订单金额的做法不同,Agile Robots尚未披露人形机器人订单量。软银收购ABB中国机器人业务刚被中国外商投资安全审查叫停,股东结构对跨境业务的影响值得关注。
- 5亿美元F轮
- 85亿美元(未说明投前或投后)
- 软银集团
- 英伟达、日立、日立风投、T.Capital
- 约20亿美元(公司口径)
- 年产最高1万台
- 逾2万套
- C轮2.2亿美元的2.3倍(MEKAWIRE计算)
为何重要
The $500 million Series F gives Agile Robots capital to expand production, enter key markets and build its US presence. More than 20,000 installed robotic solutions provide an existing deployment base, but revenue, margins and repeat orders are not supplied. The round ranks third among private robotics rounds in MEKAWIRE's database over the past 120 days, indicating strong financing access without establishing commercial returns.
竞争对手分析
Path Robotics raised $300 million at a disclosed $2.45 billion valuation, versus Agile Robots' $500 million at $8.5 billion. Path focuses on autonomous welding and is moving into shipbuilding, while Agile spans force-sensitive arms, dexterous hands and factory AI software, making the valuation comparison imperfect. SoftBank's planned $5.375 billion ABB robotics acquisition and backing of Skild AI broaden its robotics exposure, but the input establishes no integration plans with Agile.
估值背景
The $8.5 billion figure is a disclosed private valuation, not a public market cap; its pre-money or post-money basis is unstated. MEKAWIRE's 2.3x calculation compares the $500 million round with the $220 million Series C, not valuations. The company reports about $2 billion raised, conflicting with the profile's $720 million and Series C stage label; the newer Series F announcement is the relevant update. Revenue and earnings are missing, preventing operating multiple analysis.
研究依据
The supplied titles include Agile's Industrial ReMEmbR on robot fleet memory, plus AlphaNIST on assembly skills, which is credited to Franka Robotics (an Agile subsidiary) and NVIDIA. These are themes relevant to industrial automation. No abstracts, results or deployment evidence are provided, so these listings do not establish technical advantages or commercial readiness.
供应链影响
Agile plans to fund production capacity, with stated humanoid capacity of up to 10,000 units annually at Fürstenfeldbruck. That figure does not establish actual output, utilization or orders. Franka Robotics adds an owned torque-sensing arm business; Hitachi is listed as a strategic partner and NVIDIA as a pilot partner, both also Series F investors. Component suppliers, procurement terms and manufacturing bottlenecks are not disclosed.
后续看点
Watch for actual output and utilization against the stated humanoid capacity, plus customer orders supporting expansion. US facility commitments, customer wins and delivery milestones would show how funding translates into market access. Revenue, gross margins and repeat purchases would help assess whether the installed base supports attractive economics.
分析师观点
Agile's installed base and access to strategic capital support its expansion case, but the supplied facts do not establish that its $8.5 billion valuation is justified. The central investment question is whether broader production and US expansion produce profitable deployments. Treat investor participation as financing support, with commercial execution still to be demonstrated.
值得追问的问题
Is the $8.5 billion valuation pre-money or post-money, and what rights attach to the Series F? What revenue, gross margin and repeat-order rates underpin the more than 20,000 installed solutions? How much of the stated humanoid capacity is operational, what orders support it, and how will the $500 million be allocated?