独アジャイルロボッツ、評価額85億ドルで5億ドル調達 ソフトバンク主導
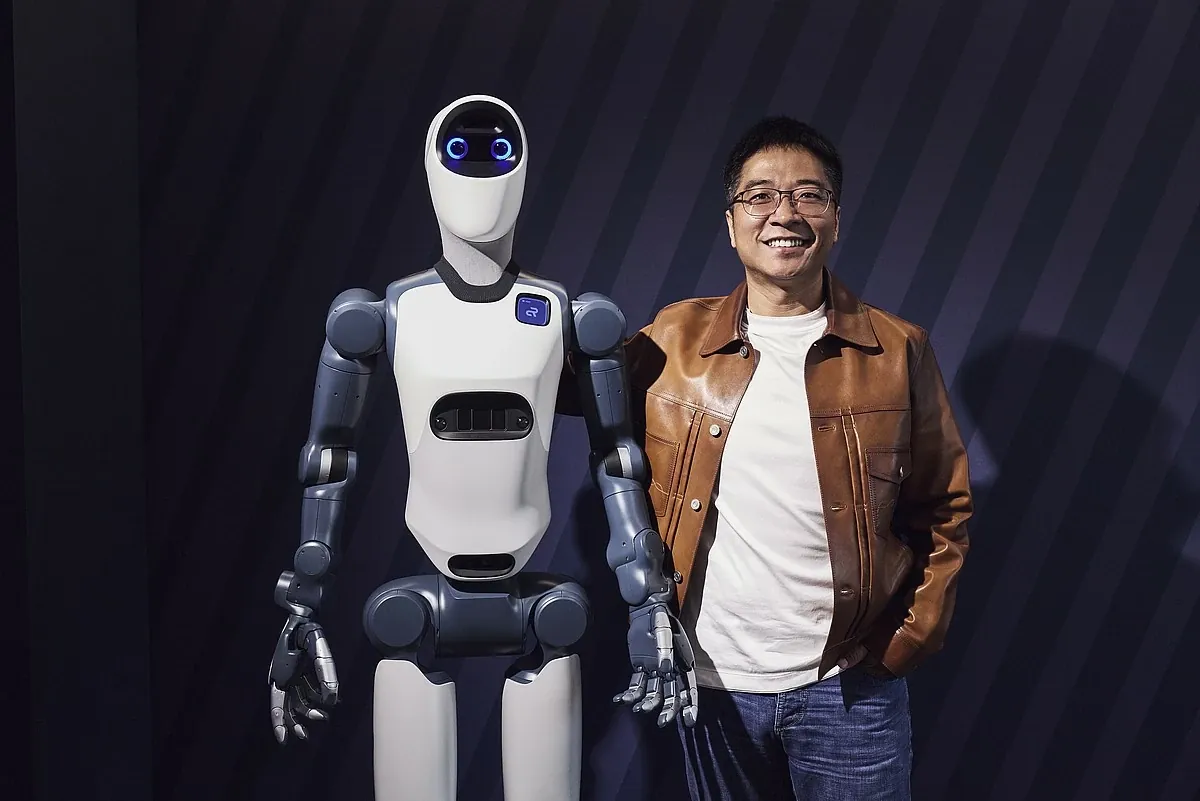
独ミュンヘンのアジャイルロボッツは12日、ソフトバンクグループが主導するシリーズFで5億ドルを調達したと発表した。評価額は85億ドルで、エヌビディア、日立、T.Capitalが参加した。累計調達額は約20億ドル。資金は生産能力の拡大と米国事業の強化に充てる。
アジャイルロボッツ(Agile Robots SE)は12日、プレスリリースでシリーズFラウンドで5億ドルを調達したと発表した。評価額は85億ドル。ソフトバンクグループが主導し、エヌビディア、日立グループ(日立と日立ベンチャーズ)、T.Capitalが参加した。累計調達額は約20億ドルとしている。
年1万台のヒューマノイド工場
同社によると資金は生産能力の増強、主要市場への進出、米国での事業拡大に使う。2026年初めにミュンヘン近郊フュルステンフェルトブルックで稼働した工場は、脚型と車輪型のヒューマノイドを年最大1万台生産できるという。導入済みのロボットソリューションは2万件超、従業員は3500人超で、うち研究開発要員が2000人を超える。
ソフトバンクのビジョンファンド2は2021年9月にも同社の2億2000万ドルのシリーズCを主導した。今回はその2.3倍にあたる(MEKAWIRE算出)。日立は9月29日に同社との製造業向けフィジカルAI提携を発表しており、今回の出資で関係を一段深めた形だ。
- 2019年7月
- プレシリーズA
- 非開示
- 記録なし
- 2020年4月
- シリーズA
- 非開示
- 記録なし
- 2021年9月
- シリーズC
- 2億2000万ドル
- ソフトバンク ビジョンファンド2
- 2026年11月12日
- シリーズF
- 5億ドル、評価額85億ドル
- ソフトバンクグループ
同社プレスリリースに基づく。シリーズB、D、Eは未収録。
2026年11月14日時点
MEKAWIRE分析
投資家はアジャイルロボッツを、ヒューマノイドという選択肢を持つ産業自動化サプライヤーとして評価した。
根拠は2万件の導入実績と買収した自動化企業群で、1万台は出荷実績ではなく生産能力にとどまる。ヒューマノイドの受注量はまだ開示されていない。人手不足に悩む日本の製造業にとっては、日立経由で同社の機体と制御ソフトが国内工場に入るかどうかが次の焦点となる。
- 5億ドル、シリーズF
- 85億ドル(算定基準は非開示)
- ソフトバンクグループ
- エヌビディア、日立、日立ベンチャーズ、T.Capital
- 約20億ドル(同社発表)
- ヒューマノイド年最大1万台
- 2万件超
- シリーズCの2.3倍(MEKAWIRE算出)
なぜ重要か
The $500 million Series F gives Agile Robots capital to expand production, enter key markets and build its US presence. More than 20,000 installed robotic solutions provide an existing deployment base, but revenue, margins and repeat orders are not supplied. The round ranks third among private robotics rounds in MEKAWIRE's database over the past 120 days, indicating strong financing access without establishing commercial returns.
競合分析
Path Robotics raised $300 million at a disclosed $2.45 billion valuation, versus Agile Robots' $500 million at $8.5 billion. Path focuses on autonomous welding and is moving into shipbuilding, while Agile spans force-sensitive arms, dexterous hands and factory AI software, making the valuation comparison imperfect. SoftBank's planned $5.375 billion ABB robotics acquisition and backing of Skild AI broaden its robotics exposure, but the input establishes no integration plans with Agile.
企業価値の背景
The $8.5 billion figure is a disclosed private valuation, not a public market cap; its pre-money or post-money basis is unstated. MEKAWIRE's 2.3x calculation compares the $500 million round with the $220 million Series C, not valuations. The company reports about $2 billion raised, conflicting with the profile's $720 million and Series C stage label; the newer Series F announcement is the relevant update. Revenue and earnings are missing, preventing operating multiple analysis.
裏付けとなる研究
The supplied titles include Agile's Industrial ReMEmbR on robot fleet memory, plus AlphaNIST on assembly skills, which is credited to Franka Robotics (an Agile subsidiary) and NVIDIA. These are themes relevant to industrial automation. No abstracts, results or deployment evidence are provided, so these listings do not establish technical advantages or commercial readiness.
サプライチェーンへの影響
Agile plans to fund production capacity, with stated humanoid capacity of up to 10,000 units annually at Fürstenfeldbruck. That figure does not establish actual output, utilization or orders. Franka Robotics adds an owned torque-sensing arm business; Hitachi is listed as a strategic partner and NVIDIA as a pilot partner, both also Series F investors. Component suppliers, procurement terms and manufacturing bottlenecks are not disclosed.
今後の注目点
Watch for actual output and utilization against the stated humanoid capacity, plus customer orders supporting expansion. US facility commitments, customer wins and delivery milestones would show how funding translates into market access. Revenue, gross margins and repeat purchases would help assess whether the installed base supports attractive economics.
アナリストの見方
Agile's installed base and access to strategic capital support its expansion case, but the supplied facts do not establish that its $8.5 billion valuation is justified. The central investment question is whether broader production and US expansion produce profitable deployments. Treat investor participation as financing support, with commercial execution still to be demonstrated.
問うべき論点
Is the $8.5 billion valuation pre-money or post-money, and what rights attach to the Series F? What revenue, gross margin and repeat-order rates underpin the more than 20,000 installed solutions? How much of the stated humanoid capacity is operational, what orders support it, and how will the $500 million be allocated?