米パスロボティクス、評価額24億5000万ドルで3億ドル調達
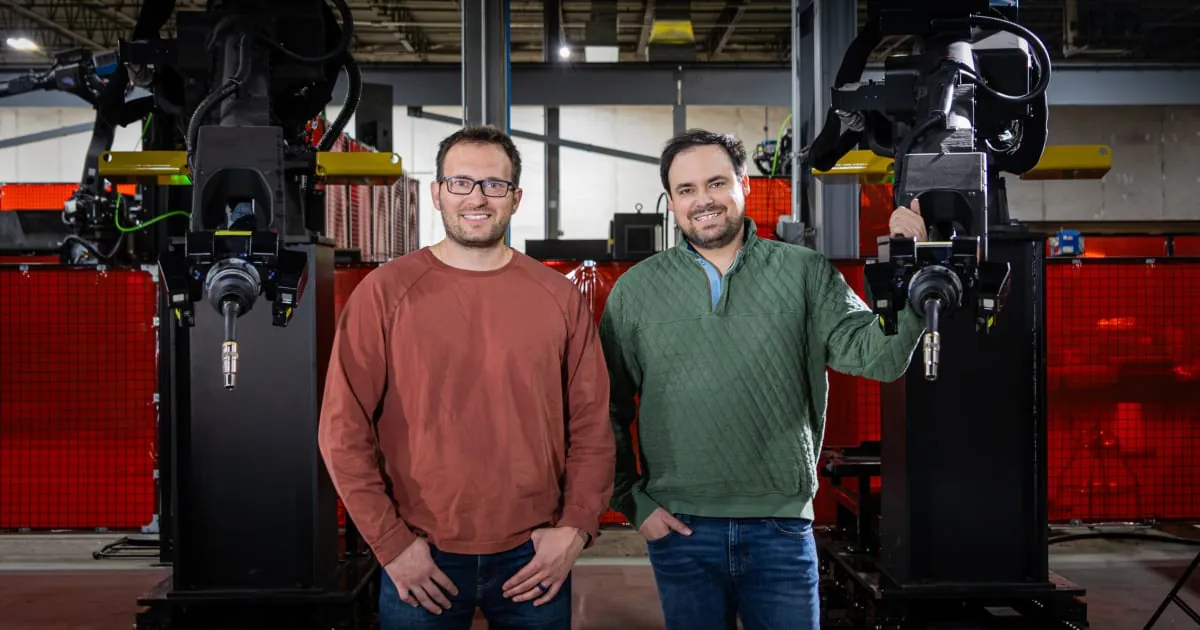
AI溶接ロボットの米パスロボティクス(オハイオ州コロンバス)は10日、ジョージアン主導のシリーズEで3億ドルを調達したと発表した。評価額は24億5000万ドル。溶接事業の拡大と、溶接前後の工程を担うモデル開発に充てる。2024年のシリーズDの3倍の規模だ。
パスロボティクス(Path Robotics)は10日、プレスリリースでAI特化のグロース投資会社ジョージアン(Georgian)が主導するシリーズEで3億ドルを調達したと発表した。評価額は24億5000万ドル。ブルームバーグは同日の見出しで25億ドルとしたが、本稿は同社発表の数字を用いる。
溶接の前後工程へ
同社は資金を顧客とともに溶接事業を拡大することに加え、溶接の前後工程に向けたデータ、計算資源、モデルの開発に投じるとしている。最高経営責任者のアンディ ロンズベリー氏は工場全体の自動化を目指すと述べた。リリースの図表では年間経常収益が18カ月で17倍になったが、金額は非開示だ。
米海軍艦艇大手のHIIもリリースで協業に触れた。HIIは8月、パスとグレイマターロボティクスの2社と最大9億ドルの成果連動型生産契約を結んでいる。
- 2021年5月
- シリーズB
- 5600万ドル
- 記録なし
- 2021年11月
- Form D
- 1億ドル
- 届出、主導なし
- 2024年10月
- シリーズD
- 1億ドル
- 記録なし
- 2026年11月10日
- シリーズE
- 3億ドル、評価額24億5000万ドル
- ジョージアン
同社リリースとSEC届出に基づく。
2026年11月14日時点
MEKAWIRE分析
投資家が評価したのは溶接ロボットではなく、実際の生産現場のデータだ。
溶接ロボットで高いシェアを持つファナックや安川電機にとって、ソフトウエアで工程を広げる新興勢は新たな競合となる。ただARRの基準額が非開示で、成長倍率の重みは測りにくい。
- 3億ドル、シリーズE
- 24億5000万ドル
- ジョージアン
- 18カ月で17倍、金額非開示
- 2億5600万ドル(DB収録3件)
- 3倍(MEKAWIRE算出)
- HIIと最大9億ドル契約(2社合計)
なぜ重要か
Path's $300 million Series E funds expansion of its autonomous welding business and model training for tasks before and after welding. The round triples its October 2024 financing and exceeds the $256 million across earlier rounds in MEKAWIRE's database. Reported ARR grew 17x in 18 months, but the undisclosed starting base limits assessment of commercial scale.
競合分析
Agile Robots raised $500 million on November 12 and has $720 million in reported funding, compared with Path's $556 million. Agile spans force-sensitive arms, dexterous hands and factory AI, while Path is expanding from welding into adjacent tasks and shipbuilding. Agile's listed relationships include Hitachi and Audi, while Path names HII and Saronic. Revenue, margins and deployment counts are missing, preventing a commercial performance comparison.
企業価値の背景
Path's $2.45 billion and Agile's $8.5 billion figures are disclosed private-company valuations. The input supplies no public market capitalization for either company. Path's 3x increase refers to round size, and its prior valuation is missing. Absolute ARR and whether the valuation is pre-money or post-money are undisclosed, preventing a revenue-multiple calculation.
裏付けとなる研究
The input lists Industrial ReMEmbR under Agile Robots, with a title focused on spatiotemporal memory for robot fleets. It also lists papers on tennis-video intelligence and navigation simulation, but supplies no findings or evidence of production use. No Path research papers are supplied, so research-based comparisons remain limited.
サプライチェーンへの影響
Path's shipbuilding relationships with HII and Saronic provide context for its expansion plans. HII's performance-based agreements total up to $900 million across Path and GrayMatter, with Path's allocation undisclosed. Component suppliers, manufacturing capacity, lead times and sourcing dependencies are missing, leaving delivery constraints unassessed.
今後の注目点
Watch for absolute ARR, customer deployment counts and revenue from tasks beyond welding to assess the expansion's commercial progress. For HII, track Path's allocated contract value, performance milestones and realized revenue against the shared $900 million ceiling. Capacity disclosures and delivery timelines would help assess execution against the new funding.
アナリストの見方
The financing gives Path resources to expand from an established welding focus into adjacent production tasks. The investment case depends on converting reported ARR growth and shipbuilding relationships into repeatable revenue with sustainable economics. Missing ARR, margins, deployment costs and contract allocations leave valuation support and execution efficiency unresolved.
問うべき論点
What are current ARR, gross margins and the starting base behind the reported 17x growth? How much of HII's shared agreement ceiling belongs to Path, and which performance conditions determine revenue? Which tasks before and after welding have paying deployments, and what capacity is required to deliver them?