美国焊接AI公司Path Robotics完成3亿美元E轮,估值24.5亿美元
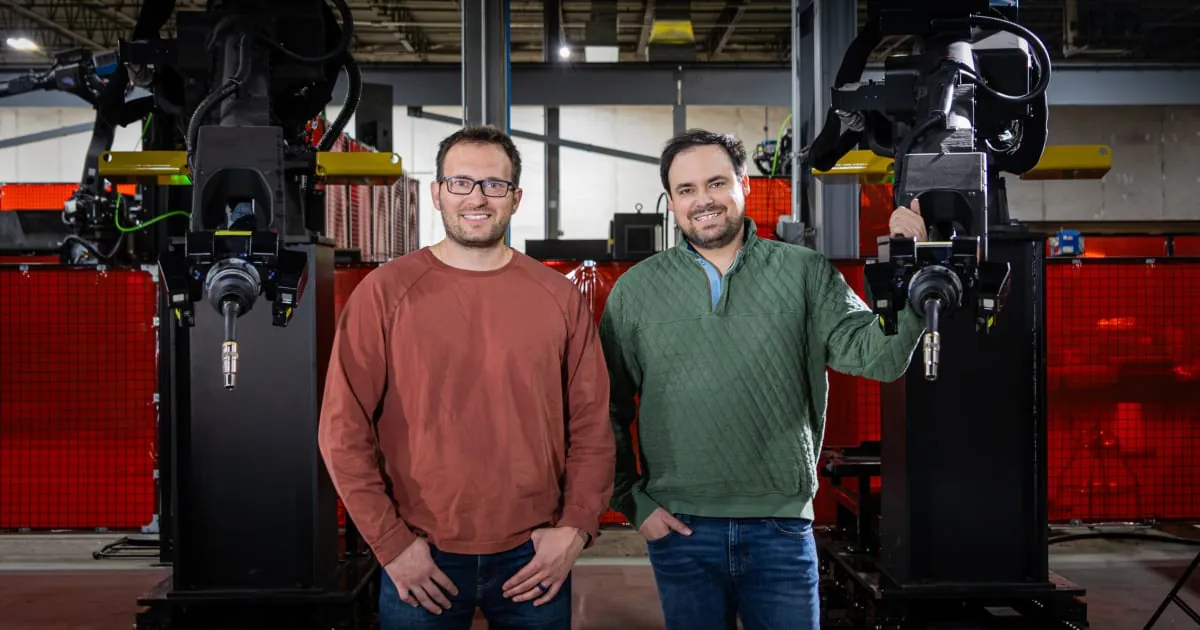
美国俄亥俄州哥伦布市的AI焊接机器人公司Path Robotics于11月10日宣布完成3亿美元E轮融资,由Georgian领投,估值24.5亿美元。资金将用于扩大焊接业务,并为焊接前后工序训练模型。本轮金额为其2024年D轮的3倍。
Path Robotics于11月10日发布新闻稿称,完成由AI成长型投资机构Georgian领投的3亿美元E轮融资,估值24.5亿美元。彭博社当日标题写作25亿美元,本文采用公司公布的数字。
从焊接走向整座工厂
公司表示,资金将用于与客户一起扩大焊接业务,并投入数据、算力和模型,覆盖焊接前后的工序。首席执行官Andy Lonsberry称目标是实现整座工厂的自动化。新闻稿图表显示,过去18个月年度经常性收入增长17倍,但未披露金额。
美国最大军舰制造商HII在新闻稿中表示将与Path继续扩充海事工业基础。HII在8月与Path及GrayMatter Robotics签署了总额最高9亿美元的绩效型生产协议。
- 2021年5月
- B轮
- 5600万美元
- 无记录
- 2021年11月
- Form D发行
- 1亿美元
- 备案无领投
- 2024年10月
- D轮
- 1亿美元
- 无记录
- 2026年11月10日
- E轮
- 3亿美元,估值24.5亿美元
- Georgian
公司新闻稿及SEC备案。
截至 2026年11月14日
MEKAWIRE 分析
投资人买的是Path积累的真实生产数据,而不是焊接机器人本身。
中国焊接机器人市场由埃斯顿、新松等厂商和大量系统集成商分食,价格竞争激烈;Path以美国国防造船订单为依托,走的是高价值数据路线。风险在于焊接单元项目制特征明显,ARR基数未公开。
- 3亿美元E轮
- 24.5亿美元
- Georgian
- 18个月17倍,金额未披露
- 2.56亿美元(数据库三笔)
- 3倍(MEKAWIRE计算)
- HII协议最高9亿美元(两家供应商合计)
为何重要
Path's $300 million Series E funds expansion of its autonomous welding business and model training for tasks before and after welding. The round triples its October 2024 financing and exceeds the $256 million across earlier rounds in MEKAWIRE's database. Reported ARR grew 17x in 18 months, but the undisclosed starting base limits assessment of commercial scale.
竞争对手分析
Agile Robots raised $500 million on November 12 and has $720 million in reported funding, compared with Path's $556 million. Agile spans force-sensitive arms, dexterous hands and factory AI, while Path is expanding from welding into adjacent tasks and shipbuilding. Agile's listed relationships include Hitachi and Audi, while Path names HII and Saronic. Revenue, margins and deployment counts are missing, preventing a commercial performance comparison.
估值背景
Path's $2.45 billion and Agile's $8.5 billion figures are disclosed private-company valuations. The input supplies no public market capitalization for either company. Path's 3x increase refers to round size, and its prior valuation is missing. Absolute ARR and whether the valuation is pre-money or post-money are undisclosed, preventing a revenue-multiple calculation.
研究依据
The input lists Industrial ReMEmbR under Agile Robots, with a title focused on spatiotemporal memory for robot fleets. It also lists papers on tennis-video intelligence and navigation simulation, but supplies no findings or evidence of production use. No Path research papers are supplied, so research-based comparisons remain limited.
供应链影响
Path's shipbuilding relationships with HII and Saronic provide context for its expansion plans. HII's performance-based agreements total up to $900 million across Path and GrayMatter, with Path's allocation undisclosed. Component suppliers, manufacturing capacity, lead times and sourcing dependencies are missing, leaving delivery constraints unassessed.
后续看点
Watch for absolute ARR, customer deployment counts and revenue from tasks beyond welding to assess the expansion's commercial progress. For HII, track Path's allocated contract value, performance milestones and realized revenue against the shared $900 million ceiling. Capacity disclosures and delivery timelines would help assess execution against the new funding.
分析师观点
The financing gives Path resources to expand from an established welding focus into adjacent production tasks. The investment case depends on converting reported ARR growth and shipbuilding relationships into repeatable revenue with sustainable economics. Missing ARR, margins, deployment costs and contract allocations leave valuation support and execution efficiency unresolved.
值得追问的问题
What are current ARR, gross margins and the starting base behind the reported 17x growth? How much of HII's shared agreement ceiling belongs to Path, and which performance conditions determine revenue? Which tasks before and after welding have paying deployments, and what capacity is required to deliver them?