Path Robotics holt 300 Mio. Dollar bei 2,45 Mrd. Dollar Bewertung
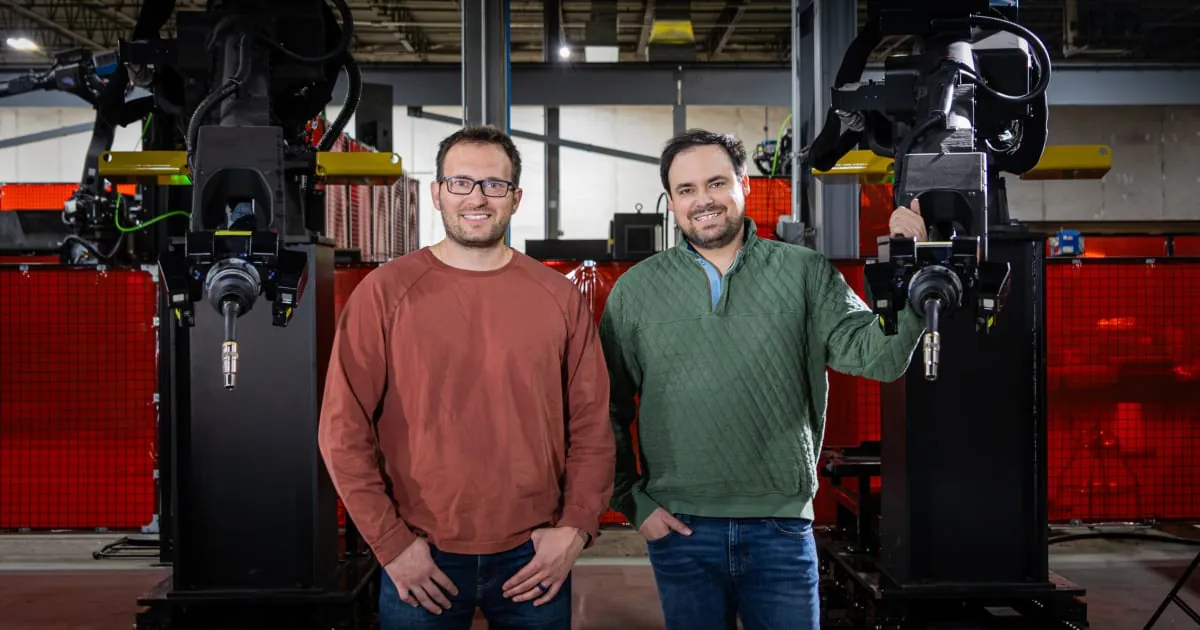
Path Robotics aus Columbus, Ohio, Anbieter KI-gestützter Schweißroboter, hat am 10. November eine Serie-E-Runde über 300 Millionen US-Dollar unter Führung von Georgian gemeldet. Die Bewertung liegt bei 2,45 Milliarden Dollar.
Das Geld fließt in den Ausbau des Schweißgeschäfts und in Modelle für vor- und nachgelagerte Fertigungsschritte.
Path Robotics teilte am 10. November mit, eine Serie-E-Finanzierung über 300 Millionen Dollar bei einer Bewertung von 2,45 Milliarden Dollar abgeschlossen zu haben. Angeführt wurde die Runde vom Wachstumsinvestor Georgian. Bloomberg rundete am selben Tag auf 2,5 Milliarden Dollar; maßgeblich ist hier die Unternehmensangabe.
Vom Schweißen zur ganzen Fabrik
Das Kapital soll das Schweißgeschäft mit bestehenden Kunden skalieren und Daten, Rechenleistung und Modelle für die Arbeitsschritte vor und nach dem Schweißen finanzieren. CEO Andy Lonsberry nannte die Automatisierung der gesamten Fabrik als Ziel. Eine Grafik in der Mitteilung zeigt ein 17-faches Wachstum der wiederkehrenden Jahresumsätze in 18 Monaten, ohne Dollarbetrag.
Der Marinewerftkonzern HII, der im August mit Path und GrayMatter Robotics Produktionsverträge über bis zu 900 Millionen Dollar schloss, äußert sich in der Mitteilung ebenso wie Lockheed Martin Ventures.
- Mai 2021
- Serie B
- 56 Mio. Dollar
- Nicht erfasst
- Nov. 2021
- Form-D-Angebot
- 100 Mio. Dollar
- Meldung ohne Lead
- Okt. 2024
- Serie D
- 100 Mio. Dollar
- Nicht erfasst
- 10. Nov. 2026
- Serie E
- 300 Mio. Dollar bei 2,45 Mrd.
- Georgian
Unternehmensmitteilungen und SEC-Meldung.
Stand: 14. Nov. 2026
MEKAWIRE-Analyse
Bezahlt wird für Produktionsdaten, nicht für Schweißzellen.
Für deutsche Anbieter von Schweißautomation ist das relevant: Path verkauft Software, die auf realen Werftdaten lernt. Das Risiko liegt im projektgetriebenen Zellengeschäft und in der unbekannten Umsatzbasis.
- 300 Mio. Dollar, Serie E
- 2,45 Mrd. Dollar
- Georgian
- 17-fach in 18 Monaten, Basis nicht genannt
- 256 Mio. Dollar in drei Finanzierungen
- Dreifach (MEKAWIRE-Berechnung)
- HII-Verträge bis 900 Mio. Dollar mit zwei Anbietern
Warum das wichtig ist
Path's $300 million Series E funds expansion of its autonomous welding business and model training for tasks before and after welding. The round triples its October 2024 financing and exceeds the $256 million across earlier rounds in MEKAWIRE's database. Reported ARR grew 17x in 18 months, but the undisclosed starting base limits assessment of commercial scale.
Wettbewerbsanalyse
Agile Robots raised $500 million on November 12 and has $720 million in reported funding, compared with Path's $556 million. Agile spans force-sensitive arms, dexterous hands and factory AI, while Path is expanding from welding into adjacent tasks and shipbuilding. Agile's listed relationships include Hitachi and Audi, while Path names HII and Saronic. Revenue, margins and deployment counts are missing, preventing a commercial performance comparison.
Bewertungskontext
Path's $2.45 billion and Agile's $8.5 billion figures are disclosed private-company valuations. The input supplies no public market capitalization for either company. Path's 3x increase refers to round size, and its prior valuation is missing. Absolute ARR and whether the valuation is pre-money or post-money are undisclosed, preventing a revenue-multiple calculation.
Zugrunde liegende Forschung
The input lists Industrial ReMEmbR under Agile Robots, with a title focused on spatiotemporal memory for robot fleets. It also lists papers on tennis-video intelligence and navigation simulation, but supplies no findings or evidence of production use. No Path research papers are supplied, so research-based comparisons remain limited.
Folgen für die Lieferkette
Path's shipbuilding relationships with HII and Saronic provide context for its expansion plans. HII's performance-based agreements total up to $900 million across Path and GrayMatter, with Path's allocation undisclosed. Component suppliers, manufacturing capacity, lead times and sourcing dependencies are missing, leaving delivery constraints unassessed.
Worauf jetzt zu achten ist
Watch for absolute ARR, customer deployment counts and revenue from tasks beyond welding to assess the expansion's commercial progress. For HII, track Path's allocated contract value, performance milestones and realized revenue against the shared $900 million ceiling. Capacity disclosures and delivery timelines would help assess execution against the new funding.
Analystensicht
The financing gives Path resources to expand from an established welding focus into adjacent production tasks. The investment case depends on converting reported ARR growth and shipbuilding relationships into repeatable revenue with sustainable economics. Missing ARR, margins, deployment costs and contract allocations leave valuation support and execution efficiency unresolved.
Offene Fragen
What are current ARR, gross margins and the starting base behind the reported 17x growth? How much of HII's shared agreement ceiling belongs to Path, and which performance conditions determine revenue? Which tasks before and after welding have paying deployments, and what capacity is required to deliver them?