美 패스로보틱스, 기업가치 24억5000만달러에 3억달러 유치
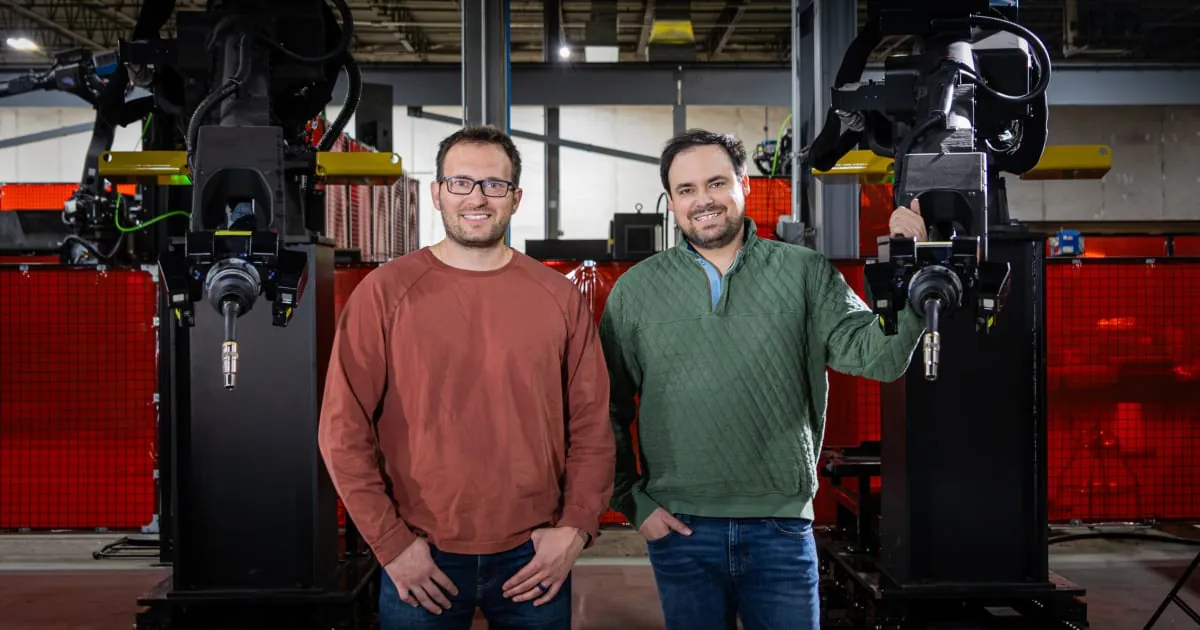
미국 오하이오주 콜럼버스의 AI 용접로봇 기업 패스로보틱스가 10일 보도자료를 통해 조지안 주도로 3억달러 규모 시리즈E 투자를 유치했다고 밝혔다. 기업가치는 24억5000만달러다. 용접 사업을 키우고 용접 전후 공정까지 자동화하는 모델 개발에 쓴다. 2024년 시리즈D의 3배 규모다.
패스로보틱스(Path Robotics)는 10일 보도자료에서 AI 전문 그로스 투자사 조지안(Georgian)이 주도한 3억달러(약 4400억원) 규모 시리즈E를 마쳤다고 밝혔다. 기업가치는 24억5000만달러다. 같은 날 블룸버그는 제목에서 25억달러로 표기했으나, 회사 발표 수치는 24억5000만달러다.
용접 다음 공정까지
회사는 투자금을 기존 고객과 함께 용접 사업을 키우고, 용접 앞뒤 공정을 위한 데이터와 컴퓨팅, 모델 개발에 쓰겠다고 밝혔다. 앤디 론스베리 최고경영자는 한 공정이 아니라 공장 전체를 자동화하는 것이 목표라고 말했다. 보도자료 도표에는 최근 18개월 연간반복매출(ARR)이 17배 늘었다고 나오지만 금액은 공개하지 않았다.
미 해군 함정 건조사 HII도 보도자료에 등장한다. HII는 8월 패스로보틱스와 그레이매터로보틱스 두 곳과 최대 9억달러 규모 성과 연동 생산 계약을 맺었다. 록히드마틴벤처스도 협력 관계를 언급했다.
- 2021년 5월
- 시리즈B
- 5600만달러
- 기록 없음
- 2021년 11월
- Form D
- 1억달러
- 공시, 주도사 없음
- 2024년 10월
- 시리즈D
- 1억달러
- 기록 없음
- 2026년 11월 10일
- 시리즈E
- 3억달러, 기업가치 24억5000만달러
- 조지안
회사 보도자료와 SEC 공시 기준.
2026년 11월 14일 기준
MEKAWIRE DB에 있는 이전 조달 세 건(2021년 시리즈B 5600만달러, 2021년 Form D 1억달러, 2024년 시리즈D 1억달러)을 합해도 2억5600만달러로 이번 한 번보다 적다(MEKAWIRE 계산).
MEKAWIRE 분석
투자자가 값을 매긴 것은 용접로봇이 아니라 실제 생산 현장 데이터다.
국내 조선 3사도 용접 자동화를 확대하고 있어, 미 해군 조선소에서 쌓인 패스의 데이터가 한국 조선 협력 사업과 맞물릴지 주목된다. 다만 ARR 기준 금액이 비공개라 성장 배수의 의미는 제한적이다.
- 3억달러, 시리즈E
- 24억5000만달러
- 조지안
- 18개월 17배, 금액 비공개
- 2억5600만달러(DB 세 건)
- 3배(MEKAWIRE 계산)
- HII 최대 9억달러 계약(8월, 2개사 합산)
매일 아침 8시, 로봇 산업 1면을 텔레그램으로
주요 기사와 신규 투자, 인수, 제휴를 한 장에 담아 보냅니다. 관심 기업 소식은 들어오는 대로 알립니다.
왜 중요한가
Path's $300 million Series E funds expansion of its autonomous welding business and model training for tasks before and after welding. The round triples its October 2024 financing and exceeds the $256 million across earlier rounds in MEKAWIRE's database. Reported ARR grew 17x in 18 months, but the undisclosed starting base limits assessment of commercial scale.
경쟁사 비교
Agile Robots raised $500 million on November 12 and has $720 million in reported funding, compared with Path's $556 million. Agile spans force-sensitive arms, dexterous hands and factory AI, while Path is expanding from welding into adjacent tasks and shipbuilding. Agile's listed relationships include Hitachi and Audi, while Path names HII and Saronic. Revenue, margins and deployment counts are missing, preventing a commercial performance comparison.
밸류에이션 맥락
Path's $2.45 billion and Agile's $8.5 billion figures are disclosed private-company valuations. The input supplies no public market capitalization for either company. Path's 3x increase refers to round size, and its prior valuation is missing. Absolute ARR and whether the valuation is pre-money or post-money are undisclosed, preventing a revenue-multiple calculation.
근거가 된 연구
The input lists Industrial ReMEmbR under Agile Robots, with a title focused on spatiotemporal memory for robot fleets. It also lists papers on tennis-video intelligence and navigation simulation, but supplies no findings or evidence of production use. No Path research papers are supplied, so research-based comparisons remain limited.
공급망 파급
Path's shipbuilding relationships with HII and Saronic provide context for its expansion plans. HII's performance-based agreements total up to $900 million across Path and GrayMatter, with Path's allocation undisclosed. Component suppliers, manufacturing capacity, lead times and sourcing dependencies are missing, leaving delivery constraints unassessed.
지켜볼 신호
Watch for absolute ARR, customer deployment counts and revenue from tasks beyond welding to assess the expansion's commercial progress. For HII, track Path's allocated contract value, performance milestones and realized revenue against the shared $900 million ceiling. Capacity disclosures and delivery timelines would help assess execution against the new funding.
애널리스트 시각
The financing gives Path resources to expand from an established welding focus into adjacent production tasks. The investment case depends on converting reported ARR growth and shipbuilding relationships into repeatable revenue with sustainable economics. Missing ARR, margins, deployment costs and contract allocations leave valuation support and execution efficiency unresolved.
따져봐야 할 질문
What are current ARR, gross margins and the starting base behind the reported 17x growth? How much of HII's shared agreement ceiling belongs to Path, and which performance conditions determine revenue? Which tasks before and after welding have paying deployments, and what capacity is required to deliver them?