Zipline以215亿美元估值融资15亿美元,约为1月的2.8倍,建设全美无人机配送网
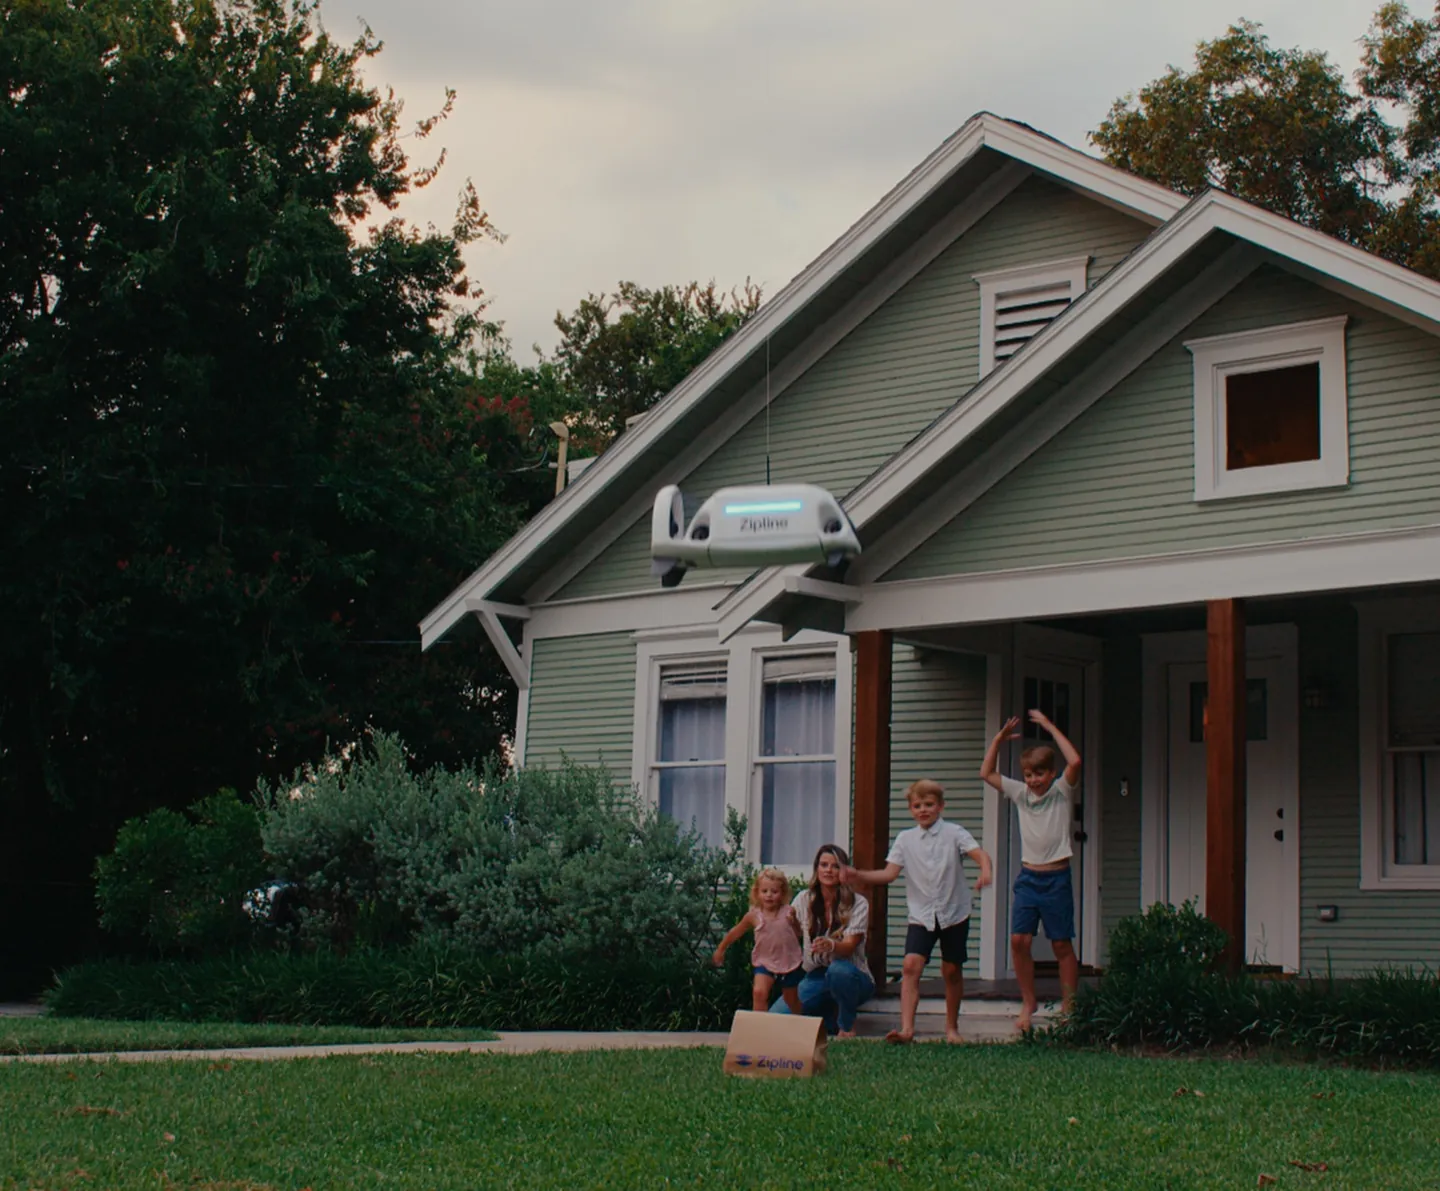
无人机配送公司Zipline于11月5日发布新闻稿称,以215亿美元投后估值完成15亿美元融资,由Paradigm、WCM Investment Management和Layer Global领投,资金将用于扩大美国制造设施和招聘。
按MEKAWIRE测算,估值约为1月那轮76亿美元的2.8倍。Zipline还表示,沃尔玛将根据新的多年期协议与其新增300个站点,Uber目标在2029年前通过Zipline实现每天100万单配送。
美国无人机配送公司Zipline于11月5日发布新闻稿称,已完成15亿美元融资,投后估值215亿美元。本轮由Paradigm、WCM Investment Management和Layer Global领投,Valor Equity Partners、富达、Uber、老虎环球、摩根大通、ARK Invest和Salesforce Ventures跟投。公司表示资金将用于扩大美国制造设施并加快招聘,建设覆盖全美的无人机配送网络。
关键在价格。Zipline在1月以76亿美元估值融资逾6亿美元,不到十个月估值升至约2.8倍(MEKAWIRE测算,215亿除以76亿)。
投资人买的是什么
Zipline列出两大客户:沃尔玛与其签订新的全国性多年期协议,将新增300个站点;Uber计划到2029年通过Zipline实现每天100万单配送。公司称今年仅在达拉斯沃斯堡地区就完成超过100万次配送,10月订单从下单到送达的中位时间为19分钟。按公司说法,合作最久的一批餐厅中,Zipline在其外卖收入中的占比从3月的10.8%升至10月的34.9%。
公司还表示,已累计完成1.5亿英里商业自主飞行且无安全事故,推出可载重更大、航程更远的新一代飞行器,并在科特迪瓦建设预计覆盖2200多家医疗机构的全国医疗配送网络。
- 2021年6月30日
- 2.5亿美元
- 27.5亿美元
- Fidelity, Intercorp, Emerging Capital Partners, Reinvent Capital, Baillie Gifford, Temasek, Katalyst Ventures
- 2026年1月21日
- 逾6亿美元,3月追加2亿美元
- 76亿美元
- 富达、Baillie Gifford、Valor Equity Partners、老虎环球等
- 2026年11月5日
- 15亿美元
- 215亿美元(投后)
- Paradigm、WCM、Layer Global(领投),Valor、富达、Uber、老虎环球、摩根大通、ARK Invest、Salesforce Ventures
Zipline公告(2021年及2026年1月数据来自MEKAWIRE融资数据库)。由76亿美元到215亿美元的倍数为MEKAWIRE测算。
截至 2026年11月14日
MEKAWIRE 分析:估值买的是网络而非飞机
投资人看重的是Zipline与沃尔玛和Uber的合同而非飞行器本身,这轮融资让美国无人机配送竞争转向制造竞赛。
本轮金额约为1月那轮的1.9倍。据Baillie Gifford报告,Zipline在3月将1月那轮追加2亿美元至约8亿美元,今年融资合计至少23亿美元(MEKAWIRE测算,15亿美元加约8亿美元)。次日即11月6日,Alphabet旗下Wing宣布两年内在得州沃斯堡工厂投资最高1.25亿美元,年产能数万架(相关报道)。两家都服务沃尔玛、都在投资美国工厂,竞争焦点正从机型设计转向谁能更快建成并运营站点。
反方观点同样清楚:Uber的每天100万单是2029年目标,沃尔玛300个站点尚未落地,Zipline也不披露收入,2.8倍的估值跃升建立在公司自行披露的合同和增速之上。对中国而言,美团等企业的无人机配送仍以城市试点为主,美国由大型零售和平台合同带动巨额制造投资的路径值得对照。公司页面见Zipline。
乐观情形是沃尔玛300个站点按期开通,双方8月表示将于今年晚些时候启动的Uber配送向2029年目标放量,支撑估值;悲观情形是地方审批拖慢站点建设,估值多年跑在收入前面。值得关注的是Uber首批配送市场、沃尔玛新站点开通节奏以及美国超视距飞行规则。
- 15亿美元,投后估值215亿美元(2026年11月5日)
- Paradigm、WCM、Layer Global
- 约为2026年1月76亿美元的2.8倍(MEKAWIRE测算)
- 扩大美国制造设施和招聘
- 新多年期协议新增300个站点
- 目标2029年前每天100万单
- 今年超过100万次配送
为何重要
Zipline's $1.5 billion raise funds US manufacturing expansion and hiring, linking fresh capital to its nationwide network plan. Walmart's agreement adds 300 planned sites, while Zipline reports more than one million Dallas-Fort Worth deliveries in 2026. Uber's target of one million Zipline deliveries daily by 2029 is a future ambition, not current throughput.
竞争对手分析
Wing also delivers Walmart orders in US metros, making Walmart a shared commercial channel rather than an exclusive Zipline advantage. The supplied material gives no comparable Wing delivery volumes, costs or expansion commitments. Investors therefore cannot establish operating leadership from Zipline's financing size alone.
估值背景
The $21.5 billion figure is a disclosed post-money financing valuation, not a public-market capitalization. It is about 2.8 times January's $7.6 billion valuation, a MEKAWIRE calculation. Revenue, margins and cash burn are absent, preventing valuation-multiple or runway analysis. The listed $1.75 billion total funding is not reconciled with the November raise, January financing and earlier rounds.
研究依据
No research papers are supplied; the references are company announcements and a financial report. They provide no independent technical evidence on reliability, autonomy performance or delivery economics.
供应链影响
Zipline designs, builds and operates its drones, and the funding explicitly supports US manufacturing expansion and hiring. Supplier identities, component sourcing, production capacity and manufacturing lead times are not supplied. Those omissions limit assessment of whether aircraft availability can support the planned site rollout.
后续看点
Track how many of Walmart's 300 additional sites actually launch and the delivery volume each supports. Compare Uber's progress with its stated 2029 daily delivery target, keeping targets separate from completed deliveries. Manufacturing output, cash burn and delivery margins would help test whether expansion is financially sustainable, but none is supplied.
分析师观点
The financing and Walmart agreement strengthen Zipline's resources and planned distribution footprint. The valuation step-up places greater weight on execution, yet the supplied facts do not establish profitable delivery economics. The investment case depends on converting planned sites into sustained utilization with manageable capital requirements.
值得追问的问题
What are the launch schedule, committed volumes and commercial terms for Walmart's 300 additional sites? What manufacturing capacity and cash runway does the raise fund? What delivery cost, margin and utilization assumptions underpin Uber's 2029 target?