ジップライン、企業価値215億ドルで15億ドル調達、1月の約2.8倍、米ドローン網構築へ
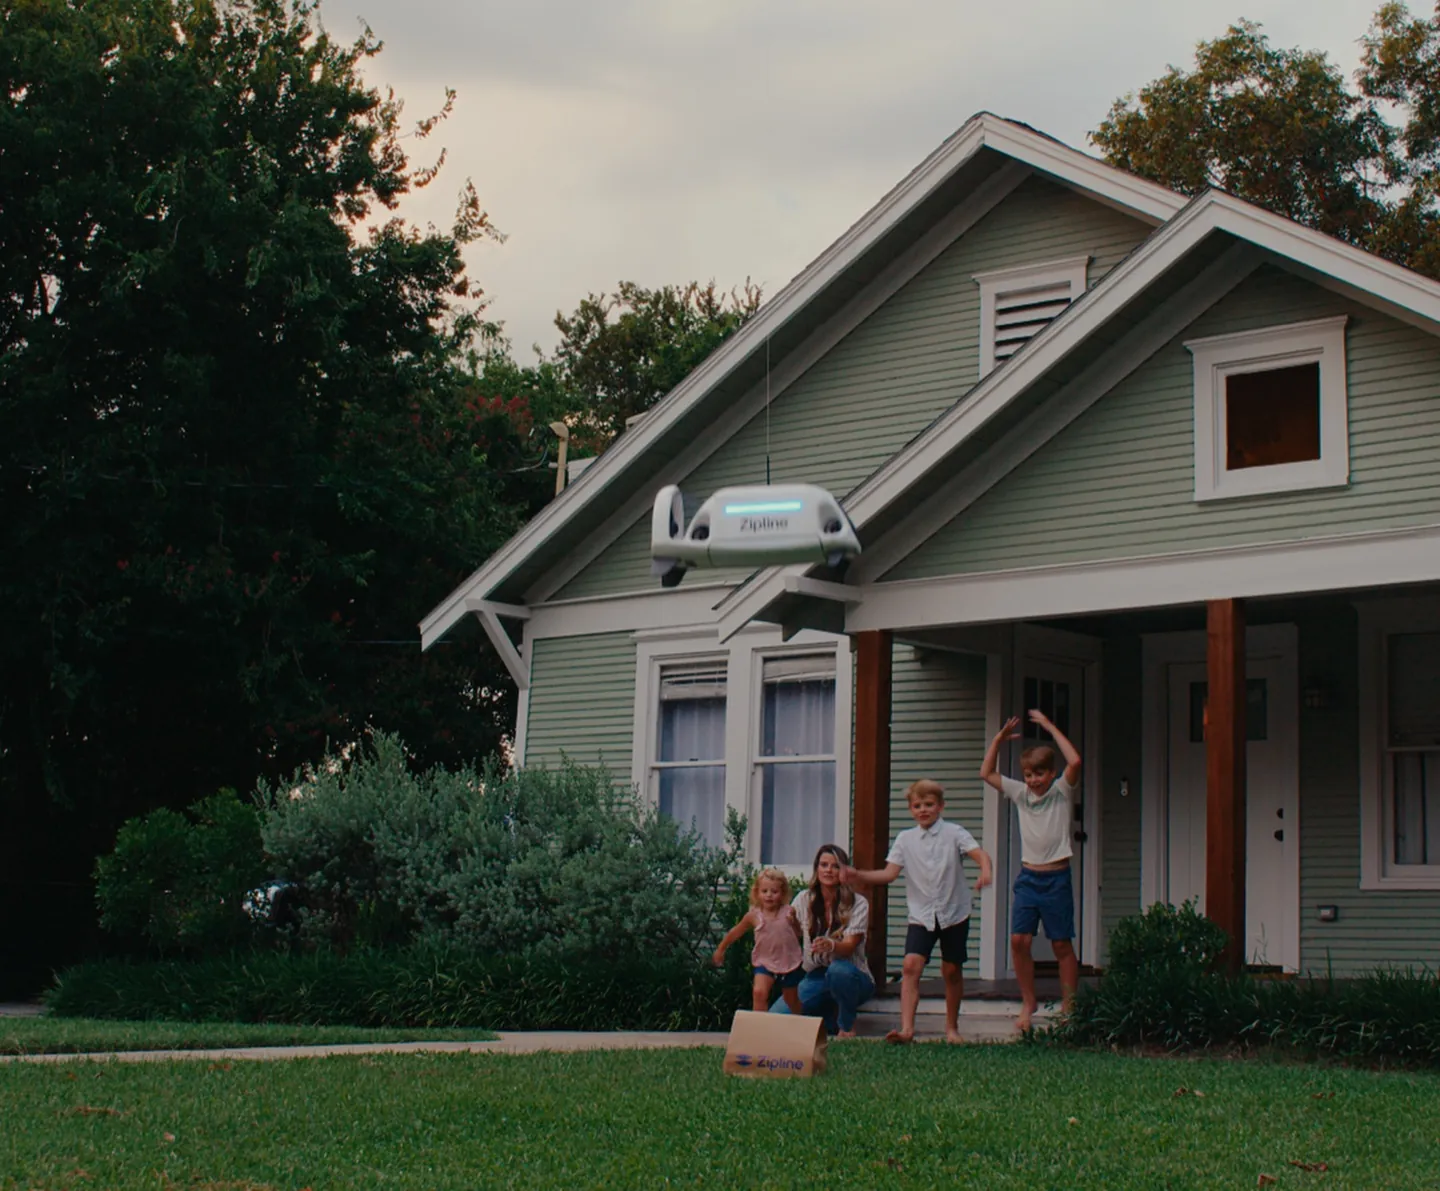
ドローン配送のジップラインは11月5日、投資後企業価値215億ドルで15億ドルを調達したと発表した。パラダイム、WCM Investment Management、レイヤーグローバルが主導し、資金は米国の製造施設拡張と採用に充てる。
企業価値は1月の調達時の76億ドルの約2.8倍(MEKAWIRE試算)。ウォルマートが新たな複数年契約で300拠点を追加し、ウーバーが2029年までに1日100万件の配送を目指すことも明らかにした。
米ドローン配送のジップライン(Zipline)は5日、プレスリリースで投資後企業価値215億ドルで15億ドルを調達したと発表した。パラダイム(Paradigm)、WCM Investment Management、レイヤーグローバル(Layer Global)が主導し、Valor Equity Partners、フィデリティ、ウーバー、タイガーグローバル、JPモルガン、ARK Invest、Salesforce Venturesが参加した。資金は米国の製造施設の拡張と採用に充て、全米規模のドローン配送網を築くという。
焦点は価格だ。同社は1月に企業価値76億ドルで6億ドル超を調達しており、10カ月足らずで評価額は約2.8倍になった(MEKAWIRE試算、215億ドルを76億ドルで割った値)。
投資家が買ったもの
ジップラインは大口顧客2社を挙げた。ウォルマートとは新たな全国規模の複数年契約で300拠点を追加し、ウーバーは2029年までにジップライン経由で1日100万件の配送を目指す。今年はダラスフォートワース地域だけで100万件超を配送し、10月の注文は決済から到着までの中央値が19分だったという。取引の長い飲食店グループでは、デリバリー売上に占めるジップラインの比率が3月の10.8%から10月には34.9%に高まったと同社は説明する。
同社は安全事故なしで商用自律飛行1億5000万マイルを達成し、より重い注文をより遠くへ運ぶ次世代機を発表、コートジボワールでは2200超の医療施設を結ぶ全国医療配送網を構築中だとしている。
- 2021年6月30日
- 2億5000万ドル
- 27億5000万ドル
- Fidelity, Intercorp, Emerging Capital Partners, Reinvent Capital, Baillie Gifford, Temasek, Katalyst Ventures
- 2026年1月21日
- 6億ドル超、3月に2億ドル追加
- 76億ドル
- フィデリティ、Baillie Gifford、Valor Equity Partners、タイガーグローバルなど
- 2026年11月5日
- 15億ドル
- 215億ドル(投資後)
- パラダイム、WCM、レイヤーグローバル(主導)、バロー、フィデリティ、ウーバー、タイガーグローバル、JPモルガン、ARK Invest、Salesforce Ventures
ジップラインの発表(2021年と2026年1月はMEKAWIRE資金調達データベース)。76億ドルから215億ドルへの倍率はMEKAWIRE試算。
2026年11月14日時点
MEKAWIRE分析:値が付いたのは機体ではなくネットワーク
投資家は機体よりウォルマートとウーバーとの契約に値を付けており、今回の調達で米国のドローン配送競争は製造競争に変わりつつある。
今回の調達額は1月のラウンドの約1.9倍だ。ベイリーギフォードの報告書によると、同社は1月のラウンドを3月に2億ドル積み増して約8億ドルとしており、今年の調達額は少なくとも23億ドルになる(MEKAWIRE試算、15億ドルと約8億ドルの合計)。翌6日にはアルファベット傘下のウイングが、テキサス州フォートワースの工場に2年で最大1億2500万ドルを投じ、年数万機の生産能力を持たせると発表した(関連記事)。両社ともウォルマートと組み、米国の工場に投資しており、競争の軸は機体設計から拠点をどれだけ速く築き運営できるかへ移っている。
反論もある。ウーバーの1日100万件は2029年の目標で、ウォルマートの300拠点はこれから開設され、同社は売上高を開示していない。2.8倍の評価額上昇は自社が示す契約と成長率に依拠している。日本ではレベル4飛行の制度が整った後も配送は実証段階が中心で、米国で大手小売りやプラットフォームとの契約が巨額の製造投資につながる流れは参考になる。企業情報はジップラインへ。
強気シナリオはウォルマートの300拠点が計画通り開設され、両社が8月に年内開始としたウーバー配送が2029年の目標に向けて伸び、評価額を裏付ける場合。弱気シナリオは地域の承認遅れで拠点開設がずれ込み、評価額が何年も売上高に先行する場合。注目点はウーバー配送の最初の市場、ウォルマート新拠点の開設ペース、米国の目視外飛行規則だ。
- 15億ドル、投資後企業価値215億ドル(2026年11月5日)
- パラダイム、WCM、レイヤーグローバル
- 2026年1月の76億ドルの約2.8倍(MEKAWIRE試算)
- 米国の製造施設拡張と採用
- 新たな複数年契約で300拠点を追加
- 2029年までに1日100万件の配送目標
- 今年100万件超を配送
なぜ重要か
Zipline's $1.5 billion raise funds US manufacturing expansion and hiring, linking fresh capital to its nationwide network plan. Walmart's agreement adds 300 planned sites, while Zipline reports more than one million Dallas-Fort Worth deliveries in 2026. Uber's target of one million Zipline deliveries daily by 2029 is a future ambition, not current throughput.
競合分析
Wing also delivers Walmart orders in US metros, making Walmart a shared commercial channel rather than an exclusive Zipline advantage. The supplied material gives no comparable Wing delivery volumes, costs or expansion commitments. Investors therefore cannot establish operating leadership from Zipline's financing size alone.
企業価値の背景
The $21.5 billion figure is a disclosed post-money financing valuation, not a public-market capitalization. It is about 2.8 times January's $7.6 billion valuation, a MEKAWIRE calculation. Revenue, margins and cash burn are absent, preventing valuation-multiple or runway analysis. The listed $1.75 billion total funding is not reconciled with the November raise, January financing and earlier rounds.
裏付けとなる研究
No research papers are supplied; the references are company announcements and a financial report. They provide no independent technical evidence on reliability, autonomy performance or delivery economics.
サプライチェーンへの影響
Zipline designs, builds and operates its drones, and the funding explicitly supports US manufacturing expansion and hiring. Supplier identities, component sourcing, production capacity and manufacturing lead times are not supplied. Those omissions limit assessment of whether aircraft availability can support the planned site rollout.
今後の注目点
Track how many of Walmart's 300 additional sites actually launch and the delivery volume each supports. Compare Uber's progress with its stated 2029 daily delivery target, keeping targets separate from completed deliveries. Manufacturing output, cash burn and delivery margins would help test whether expansion is financially sustainable, but none is supplied.
アナリストの見方
The financing and Walmart agreement strengthen Zipline's resources and planned distribution footprint. The valuation step-up places greater weight on execution, yet the supplied facts do not establish profitable delivery economics. The investment case depends on converting planned sites into sustained utilization with manageable capital requirements.
問うべき論点
What are the launch schedule, committed volumes and commercial terms for Walmart's 300 additional sites? What manufacturing capacity and cash runway does the raise fund? What delivery cost, margin and utilization assumptions underpin Uber's 2029 target?