오토스토어, 올해 매출 전망 7억5000만달러로 상향하고 팔레트 로봇 기업 로직스 인수
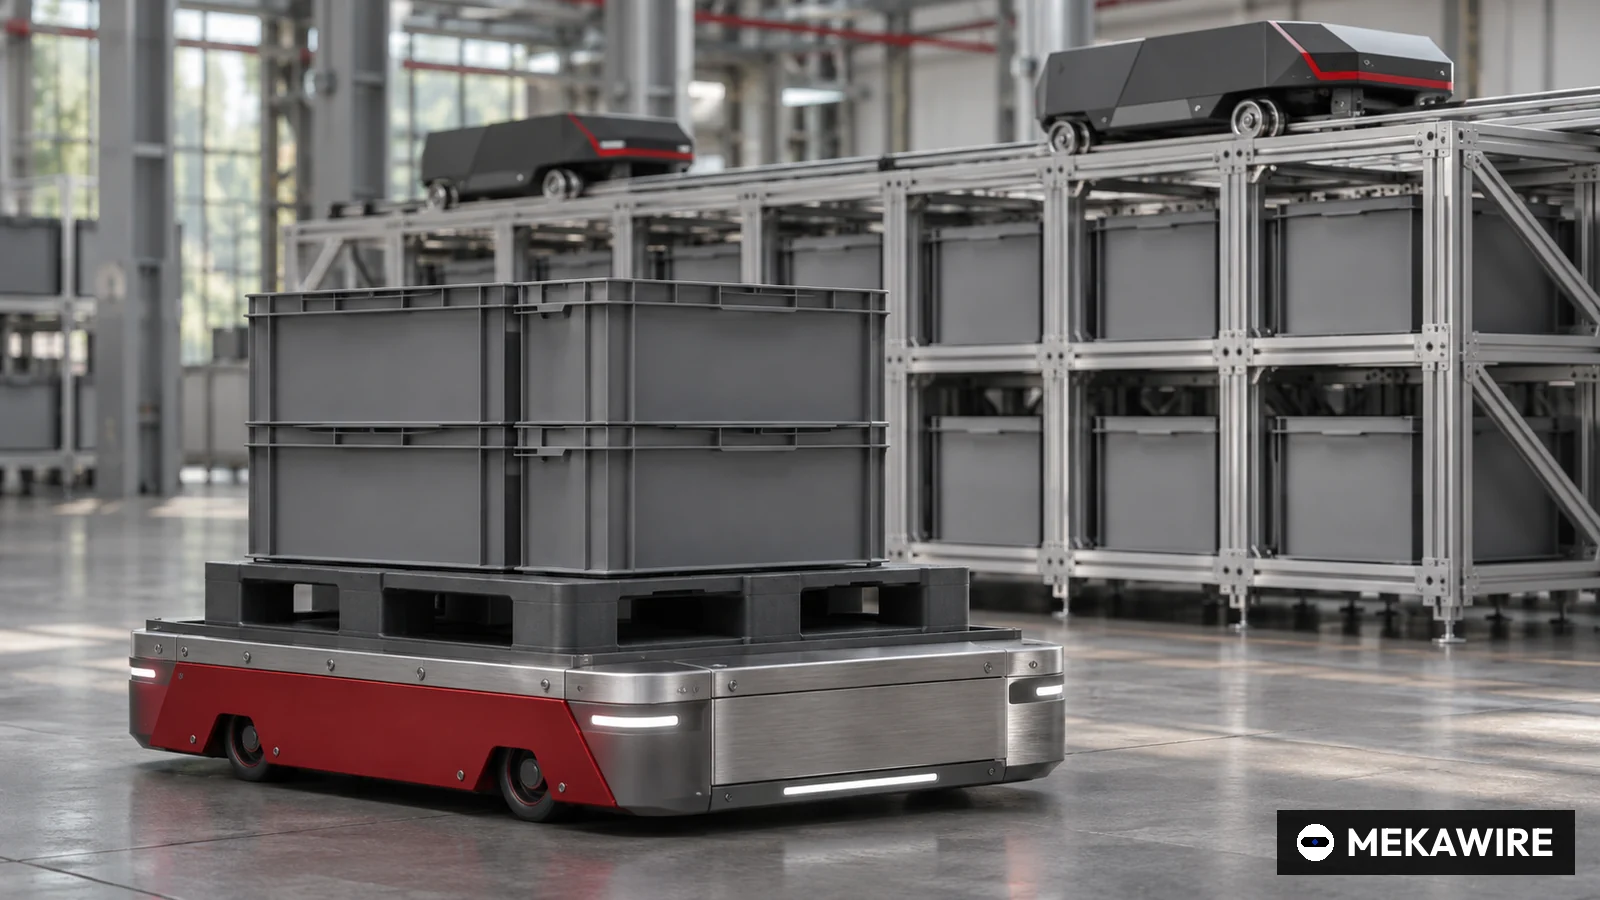
노르웨이 큐브형 자동창고 로봇 기업 오토스토어가 5일 네덜란드의 이동형 팔레트 자동창고(AS/RS) 기업 로직스를 최대 3000만유로에 인수한다고 발표하고, 같은 날 2026년 매출 전망을 약 7억달러에서 약 7억5000만달러로 올렸다.
3분기 매출은 1억9210만달러로 전년 동기보다 38.2% 늘었고 수주는 16.5% 증가한 1억7760만달러였다. MEKAWIRE 계산으로 새 전망은 4분기 매출 약 2억달러를 전제한다.
오슬로 증시 상장사 오토스토어는 5일 보도자료를 통해 네덜란드의 이동형 팔레트 자동창고(AS/RS) 기업 로직스(Logiqs BV)를 최대 3000만유로에 인수하기로 합의했다고 밝혔다. 같은 날 3분기 실적을 내놓으며 2026년 연간 매출 전망을 2분기 때 제시한 약 7억달러에서 약 7억5000만달러로 높였다. 격자 위를 달리는 로봇이 상자(빈)를 꺼내는 큐브 저장 방식으로 성장한 오토스토어가 팔레트 단위 보관으로 영역을 넓히는 첫 인수다.
인수 대금은 보유 현금으로 치르며 실적에 중대한 영향은 없을 것이라고 회사 측은 설명했다. 로직스는 팔레트 화물을 보관하고 꺼내는 이동형 로봇을 개발하며, 여러 지역과 산업의 약 30개 고객 사업장에 기술을 공급하고 있다. 직원은 60명이다. 로직스도 같은 날 자사 뉴스 페이지에 인수 합의를 알렸다. 거래는 통상적인 조건 충족을 전제로 2026년 4분기에 마무리될 예정이다.
상향 전망을 떠받친 3분기 숫자
3분기 매출은 1억9210만달러로 1년 전 1억3900만달러보다 38.2% 늘었고, 수주는 1억7760만달러로 16.5% 증가했다. 매출총이익률은 원자재 가격 상승분이 시차를 두고 반영되며 73.1%에서 71.3%로 내려갔고, 조정 EBITDA 이익률은 성장 투자가 이어지며 47.1%에서 42.3%로 낮아졌다. 영업현금흐름은 1억140만달러, 9월 말 현금은 1억5120만달러였다. 자사주 매입으로 11월 4일까지 5300만달러를 주주에게 돌려줬다.
- 매출
- 139.0
- 192.1
- 192.1
- 수주
- 152.4
- 217.6
- 177.6
- 매출총이익률
- 73.1%
- 72.2%
- 71.3%
- 조정 EBITDA 이익률
- 47.1%
- 44.9%
- 42.3%
- 수주/매출 비율
- 1.10
- 1.13
- 0.92
오토스토어 2026년 2분기와 3분기 실적 자료. 수주/매출 비율은 MEKAWIRE 계산.
2026년 11월 5일 기준
MEKAWIRE 분석: 하반기를 더 강하게 가정한 전망
오토스토어는 본업이 성장하는 동안 팔레트 영역을 싸게 사들였지만, 3분기 숫자는 수요가 가속이 아니라 정체 국면에 들어섰음을 보여준다.
1~9월 누적 매출이 5억4990만달러이므로 새 전망은 4분기 매출 약 2억10만달러, 3분기보다 약 4% 많은 수준을 뜻한다(MEKAWIRE 계산, 7억5000만달러에서 누적 매출을 뺀 값). 10월 MEKAWIRE 해설 기사에서 기존 7억달러 전망은 하반기가 상반기보다 약 4.4% 적다는 의미였는데, 새 전망은 하반기 약 3억9200만달러로 상반기 3억5780만달러보다 약 10% 많다(MEKAWIRE 계산). 반면 3분기 매출은 2분기와 같은 1억9210만달러였고 수주는 2분기 2억1760만달러에서 줄어 수주 대비 매출 비율은 약 0.92에 그쳤다(MEKAWIRE 계산). 전망 상향이 새 수주보다 이미 확보한 수주잔고에 기대고 있다는 뜻이다.
국내 물류 자동화 업계에도 시사점이 있다. 팔레트 자동창고는 국내 대형 유통과 3PL 센터의 주력 설비인데, 상자 단위 시스템 강자가 팔레트까지 묶어 팔기 시작하면 통합 구축사 입장에서는 한 플랫폼으로 두 영역을 제안할 수 있게 된다. 관련 해설은 오토스토어란?, 기업 정보는 오토스토어에서 볼 수 있다.
긍정 시나리오는 4분기 매출이 2억달러를 넘고 팔레트 제품이 기존 고객에게 붙어 팔리는 경우다. 부정 시나리오는 수주가 한 분기 더 매출을 밑돌고 이익률 하락이 이어지는 경우다. 확인할 지표는 4분기 중 로직스 거래 종결 공시, 2027년 2월 4분기 실적의 연간 매출, 오토스토어 팔레트 시스템의 첫 고객 공개다.
- 약 7억5000만달러(기존 약 7억달러)
- 1억9210만달러, 전년 대비 38.2% 증가
- 1억7760만달러, 16.5% 증가
- 매출총이익률 71.3%, 조정 EBITDA 42.3%
- 최대 3000만유로, 보유 현금
- 이동형 팔레트 AS/RS, 고객 사업장 약 30곳, 직원 60명
- 약 2억달러(MEKAWIRE 계산)
- 2026년 4분기 예정
매일 아침 8시, 로봇 산업 1면을 텔레그램으로
주요 기사와 신규 투자, 인수, 제휴를 한 장에 담아 보냅니다. 관심 기업 소식은 들어오는 대로 알립니다.
왜 중요한가
Buying Logiqs would extend AutoStore's offering from cube storage into roaming pallet AS/RS, adding a business with about 30 customer sites and 60 employees. The guidance increase to about USD 750 million implies roughly USD 200 million of Q4 revenue, a MEKAWIRE calculation. Q3 revenue grew 38.2%, while order intake grew 16.5%, making order conversion and demand momentum important to assess separately.
경쟁사 비교
Logiqs would broaden AutoStore's product coverage as it competes with warehouse automation suppliers including Symbotic, Ocado and Exotec. Symbotic serves retailers and distributors, with Walmart among its customers, while Ocado licenses robotic grocery fulfilment technology. Exotec combines rack-climbing bin retrieval robots with Deepsky software. The supplied facts provide no comparable pricing, margins or win rates to establish a competitive advantage.
밸류에이션 맥락
The acquisition consideration is up to EUR 30 million in cash, with no Logiqs revenue or earnings supplied to calculate transaction multiples. Market capitalizations for listed AutoStore, Symbotic and Ocado are absent. Exotec's USD 2 billion valuation is disclosed, with funding rounds dated 2020 and 2022, but its valuation date is unspecified and no current valuation estimate is supplied.
근거가 된 연구
No research papers are supplied, so technical performance claims cannot be assessed against published results. The cited company releases and quarterly update support the transaction and financial reporting.
공급망 파급
AutoStore plans to fund the purchase from existing cash, with closing expected in Q4 2026. Logiqs brings 60 employees and about 30 customer sites, creating integration and service obligations to assess. Component suppliers, manufacturing capacity and sourcing dependencies are absent from the supplied material.
지켜볼 신호
Watch whether Q4 revenue reaches the roughly USD 200 million implied by guidance, a MEKAWIRE calculation. Track order intake after its 16.5% Q3 increase alongside revenue growth of 38.2%. Closing progress and subsequent gross and adjusted EBITDA margins will help assess execution against the reported 71.3% and 42.3% levels.
애널리스트 시각
The acquisition offers a concrete route to broader warehouse automation coverage, supported by Logiqs' existing customer sites. Its financial contribution remains unquantified because revenue, earnings and integration costs are missing. The raised guidance supports near-term revenue expectations, while slower order growth warrants attention when assessing durability.
따져봐야 할 질문
What revenue, earnings and integration costs does AutoStore expect from Logiqs, and what determines the final consideration within the EUR 30 million ceiling? What backlog conversion assumptions support the implied Q4 revenue, and how will AutoStore sell and service pallet systems through its existing commercial relationships?