AutoStore lifts 2026 revenue guide to $750m and agrees to buy pallet-robot maker Logiqs
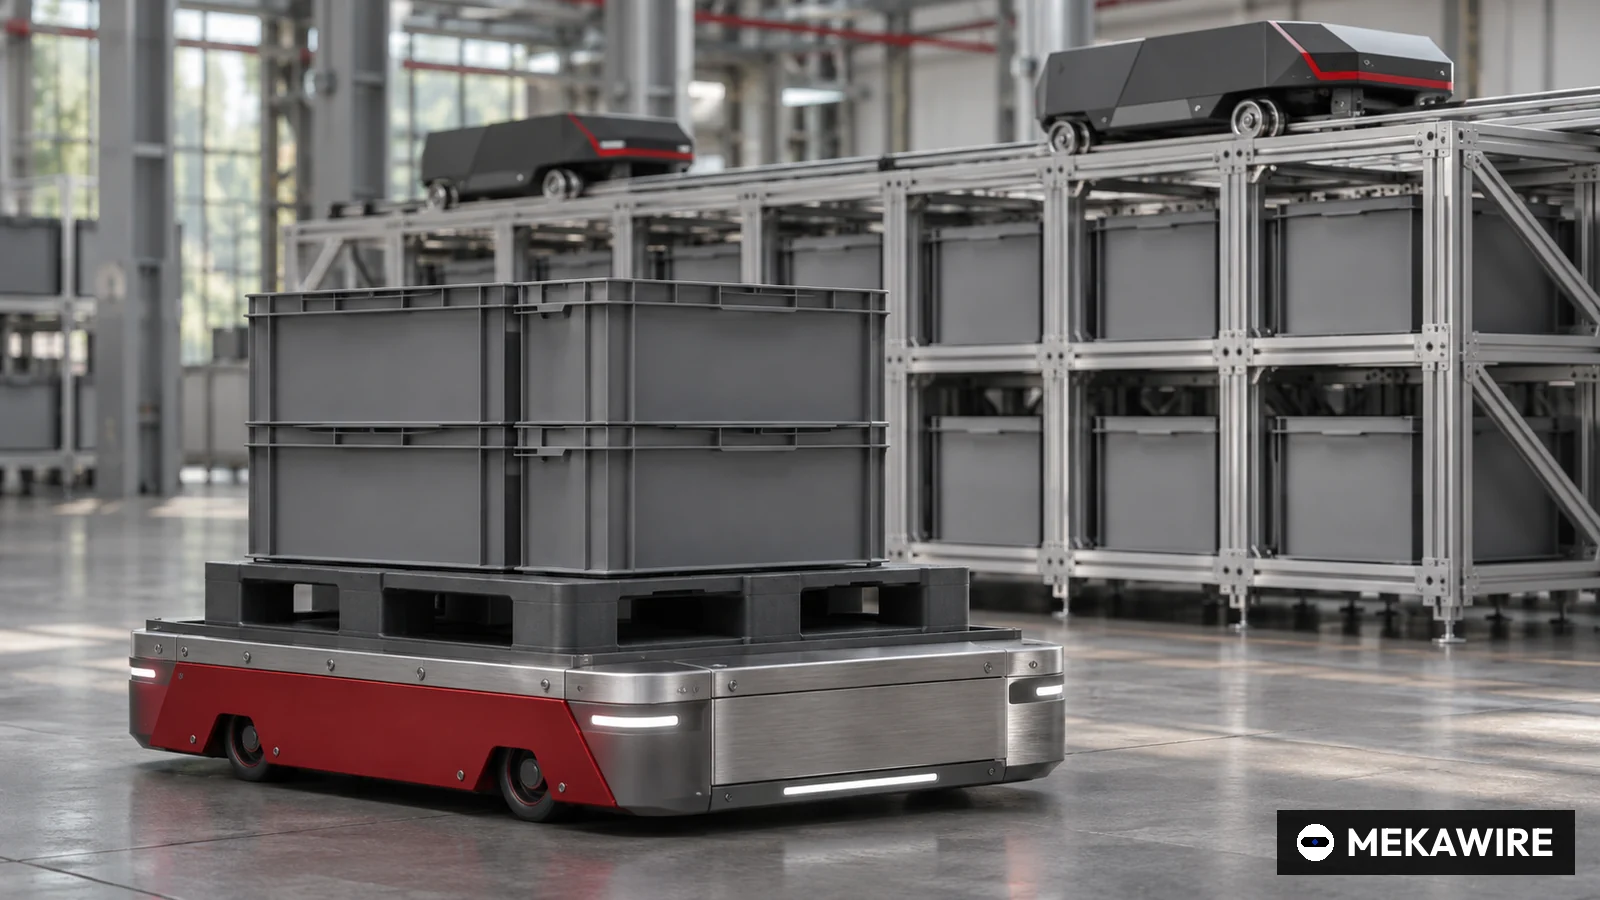
AutoStore, the Oslo-listed maker of cube storage robots, said on Nov 5 that it will buy Dutch roaming pallet AS/RS maker Logiqs for up to EUR 30 million in cash and raised its 2026 revenue guidance to about USD 750 million from about USD 700 million.
Q3 revenue was USD 192.1 million, up 38.2% from a year earlier, while order intake rose 16.5% to USD 177.6 million. The new guidance implies about USD 200 million of revenue in Q4, by MEKAWIRE's calculation.
AutoStore said on Nov 5 that it has agreed to acquire Logiqs BV, a Dutch provider of roaming pallet automated storage and retrieval systems, for a purchase price of up to EUR 30 million, and on the same day raised its full-year 2026 revenue guidance to around USD 750 million from around USD 700 million given with its second-quarter results. The Oslo-listed company, whose robots run on top of a grid of stacked bins, has until now handled totes and cases, not pallets.
The deal is small next to AutoStore's balance sheet, which is why the guidance matters more for investors and the pallet move matters more for customers. AutoStore said the price will be paid from existing cash and is not expected to have a material impact on its results.
A pallet business for a tote company
Logiqs, based in Maasdijk, builds roaming robots that store and retrieve palletised goods. AutoStore said its technology runs at about 30 customer sites in several regions and end markets and that its 60 employees bring automation, software and product skills. Logiqs announced the agreement on its own news page the same day. AutoStore CEO Mats Hovland Vikse called it a core technology that will, over time, bring roaming pallet AS/RS into the AutoStore platform. AutoStore expects the transaction to close in Q4 2026, subject to customary conditions, and said more detail will follow as it prepares the technology for a wider commercial release.
The quarter behind the higher guidance
Q3 revenue was USD 192.1 million, up 38.2% from USD 139.0 million a year earlier, and order intake was USD 177.6 million, up 16.5%, which the CEO called the company's highest third-quarter order intake. Gross margin slipped to 71.3% from 73.1%, which the report put down to the delayed effect of higher commodity prices, and the adjusted EBITDA margin fell to 42.3% from 47.1% reflecting continued investment in growth. Operating cash flow was USD 101.4 million and cash stood at USD 151.2 million on Sept. 30. AutoStore said USD 53 million had been returned to shareholders through its buy-back by Nov. 4.
- Revenue
- 139.0
- 192.1
- 192.1
- Order intake
- 152.4
- 217.6
- 177.6
- Gross margin
- 73.1%
- 72.2%
- 71.3%
- Adjusted EBITDA margin
- 47.1%
- 44.9%
- 42.3%
- Book-to-bill (order intake / revenue)
- 1.10
- 1.13
- 0.92
AutoStore Q2 2026 and Q3 2026 releases and reports. Book-to-bill is a MEKAWIRE calculation.
As of Nov 5, 2026
MEKAWIRE analysis: the guidance now asks for a stronger second half
AutoStore is buying its way into pallets cheaply while its core business is still growing, but the quarter shows demand that is levelling, not accelerating.
Revenue for the first nine months was USD 549.9 million, so the new guidance implies about USD 200.1 million in Q4, about 4% above Q3 (MEKAWIRE calc., 750 minus 549.9, divided by 192.1). In our October explainer the old USD 700 million guide implied a second half about 4.4% below the first; the new one implies a second half of about USD 392 million, about 10% above the first half of USD 357.8 million (MEKAWIRE calc.). Q3 revenue was flat on Q2 at USD 192.1 million, and order intake fell from USD 217.6 million in Q2, so the Q3 book-to-bill ratio was about 0.92 (MEKAWIRE calc., 177.6 divided by 192.1). That is the counter-argument to the bullish read: the raise rests on backlog already won, not on new orders running ahead of shipments.
The pallet step brings AutoStore closer to the pallet and case automation that Symbotic sells to Walmart and that Ocado and Exotec offer to grocers and retailers. A EUR 30 million ceiling for a 60-person company with about 30 sites suggests AutoStore is buying a technology to build out, not revenue. MEKAWIRE explainer: What is AutoStore?. Company page: AutoStore.
Bull case: Logiqs lets integrators sell one AutoStore stack for both bins and pallets, and Q4 lands above USD 200 million. Bear case: order intake stays below revenue for another quarter and the margin slide continues as commodity costs flow through. Signals to watch: the closing notice for Logiqs in Q4 2026, the Q4 2026 report in February 2027 with full-year revenue against USD 750 million, and the first named customer for an AutoStore pallet system.
- Roaming pallet AS/RS, about 30 customer sites, 60 employees
- Expected Q4 2026
- Gross 71.3%, adjusted EBITDA 42.3%
- About USD 200m (MEKAWIRE calc.)
- Up to EUR 30m, from existing cash
- About USD 750m, raised from about USD 700m
- USD 192.1m, up 38.2% YoY
- USD 177.6m, up 16.5% YoY
Why it matters
Buying Logiqs would extend AutoStore's offering from cube storage into roaming pallet AS/RS, adding a business with about 30 customer sites and 60 employees. The guidance increase to about USD 750 million implies roughly USD 200 million of Q4 revenue, a MEKAWIRE calculation. Q3 revenue grew 38.2%, while order intake grew 16.5%, making order conversion and demand momentum important to assess separately.
Rival analysis
Logiqs would broaden AutoStore's product coverage as it competes with warehouse automation suppliers including Symbotic, Ocado and Exotec. Symbotic serves retailers and distributors, with Walmart among its customers, while Ocado licenses robotic grocery fulfilment technology. Exotec combines rack-climbing bin retrieval robots with Deepsky software. The supplied facts provide no comparable pricing, margins or win rates to establish a competitive advantage.
Valuation context
The acquisition consideration is up to EUR 30 million in cash, with no Logiqs revenue or earnings supplied to calculate transaction multiples. Market capitalizations for listed AutoStore, Symbotic and Ocado are absent. Exotec's USD 2 billion valuation is disclosed, with funding rounds dated 2020 and 2022, but its valuation date is unspecified and no current valuation estimate is supplied.
Related papers
No research papers are supplied, so technical performance claims cannot be assessed against published results. The cited company releases and quarterly update support the transaction and financial reporting.
Supply-chain implications
AutoStore plans to fund the purchase from existing cash, with closing expected in Q4 2026. Logiqs brings 60 employees and about 30 customer sites, creating integration and service obligations to assess. Component suppliers, manufacturing capacity and sourcing dependencies are absent from the supplied material.
Signals to watch
Watch whether Q4 revenue reaches the roughly USD 200 million implied by guidance, a MEKAWIRE calculation. Track order intake after its 16.5% Q3 increase alongside revenue growth of 38.2%. Closing progress and subsequent gross and adjusted EBITDA margins will help assess execution against the reported 71.3% and 42.3% levels.
Analyst view
The acquisition offers a concrete route to broader warehouse automation coverage, supported by Logiqs' existing customer sites. Its financial contribution remains unquantified because revenue, earnings and integration costs are missing. The raised guidance supports near-term revenue expectations, while slower order growth warrants attention when assessing durability.
Questions you should be asking
What revenue, earnings and integration costs does AutoStore expect from Logiqs, and what determines the final consideration within the EUR 30 million ceiling? What backlog conversion assumptions support the implied Q4 revenue, and how will AutoStore sell and service pallet systems through its existing commercial relationships?