AutoStore将2026年营收指引上调至7.5亿美元,并收购托盘机器人企业Logiqs
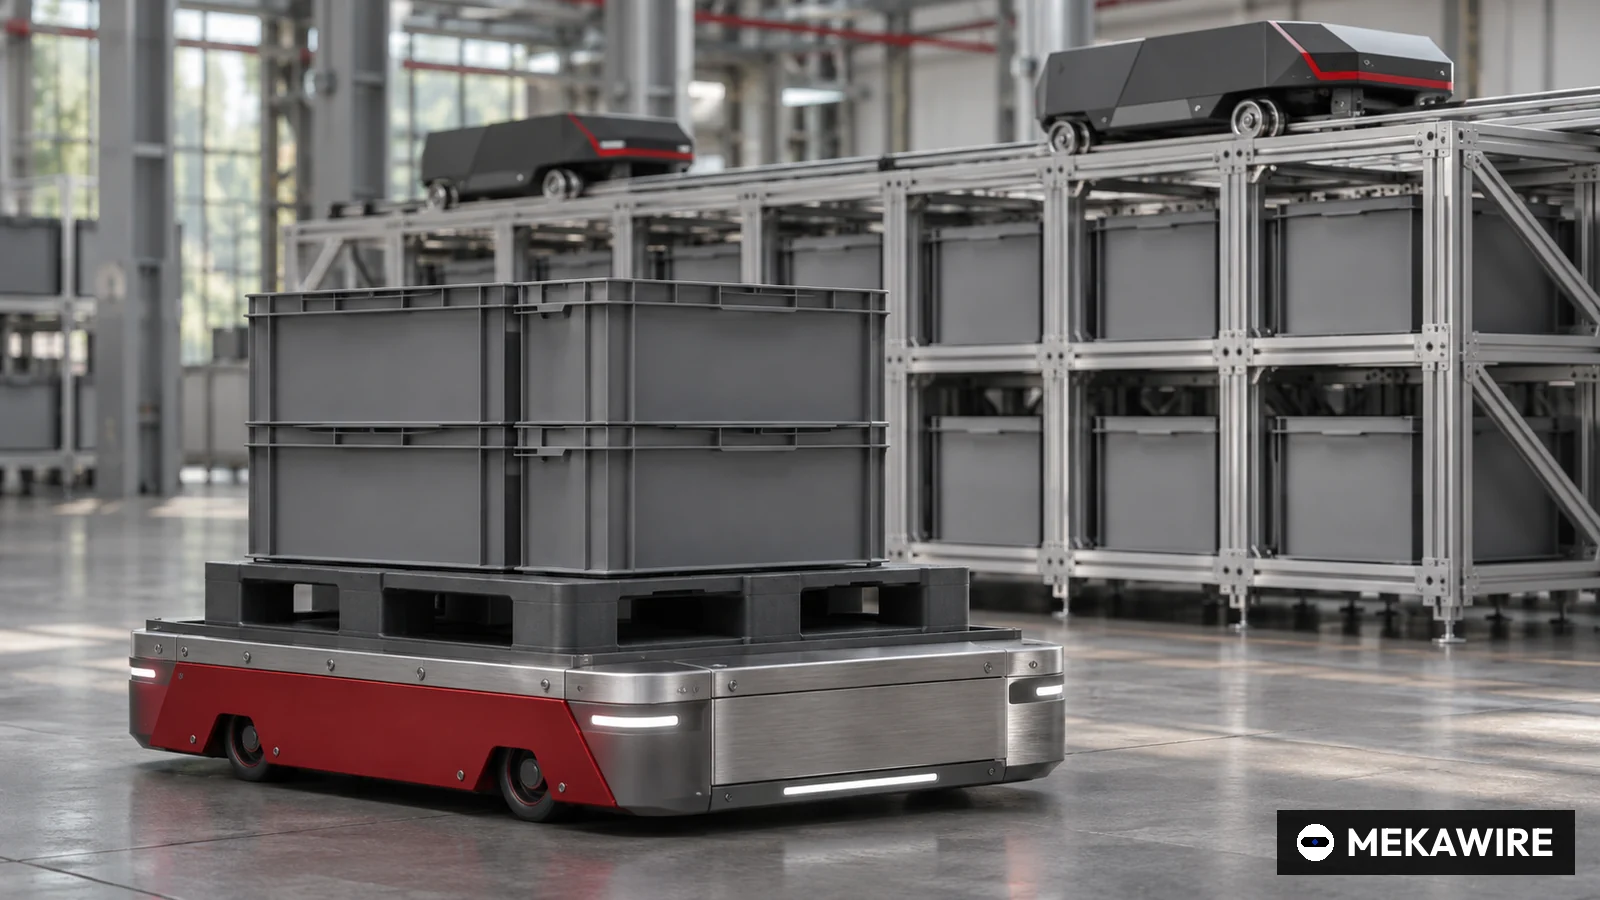
奥斯陆上市的立方体仓储机器人企业AutoStore于11月5日宣布,将以最高3000万欧元收购荷兰移动式托盘自动化立体仓库(AS/RS)企业Logiqs,并把2026年营收指引从约7亿美元上调至约7.5亿美元。第三季度营收1.921亿美元,同比增长38.2%;订单额1.776亿美元,增长16.5%。按MEKAWIRE测算,新指引意味着第四季度营收约2亿美元。
AutoStore于11月5日发布新闻稿称,已同意以最高3000万欧元收购荷兰移动式托盘自动化立体仓库(AS/RS)供应商Logiqs BV。公司同日公布第三季度业绩,并将2026年全年营收指引由二季度时给出的约7亿美元上调至约7.5亿美元。AutoStore以机器人在网格顶部存取料箱的立方体仓储起家,此前业务集中在料箱和纸箱层面,此次收购把触角伸向托盘仓储。
公司表示收购款以现有现金支付,预计不会对业绩产生重大影响。Logiqs总部位于荷兰马斯代克,开发存取托盘货物的移动机器人,其技术已在多个地区和行业的约30个客户站点运行,员工60人。Logiqs当天也在官网发布了收购消息。交易预计在2026年第四季度完成,需满足惯常交割条件。
上调指引背后的三季度数据
第三季度营收1.921亿美元,较上年同期的1.39亿美元增长38.2%;订单额1.776亿美元,增长16.5%。毛利率由73.1%降至71.3%,公司称主要是大宗商品涨价滞后传导所致;调整后EBITDA利润率由47.1%降至42.3%,反映持续的增长投入。经营现金流1.014亿美元,9月末现金1.512亿美元。截至11月4日,公司通过回购向股东返还5300万美元。
- 营收
- 139.0
- 192.1
- 192.1
- 订单额
- 152.4
- 217.6
- 177.6
- 毛利率
- 73.1%
- 72.2%
- 71.3%
- 调整后EBITDA利润率
- 47.1%
- 44.9%
- 42.3%
- 订单与营收之比
- 1.10
- 1.13
- 0.92
AutoStore 2026年二季度及三季度业绩材料。订单与营收之比为MEKAWIRE测算。
截至 2026年11月5日
MEKAWIRE 分析:新指引押注更强的下半年
AutoStore在主业仍在增长时低价切入托盘领域,但三季度数据显示需求趋于平稳,而非加速。
前三季度营收5.499亿美元,新指引意味着第四季度营收约2.001亿美元,比三季度高约4%(MEKAWIRE测算,7.5亿美元减去前三季度营收)。MEKAWIRE十月的解读文章指出,原7亿美元指引意味着下半年比上半年低约4.4%;新指引则意味着下半年约3.92亿美元,比上半年的3.578亿美元高约10%(MEKAWIRE测算)。但三季度营收与二季度持平,订单额从二季度的2.176亿美元回落,订单与营收之比约0.92(MEKAWIRE测算)。上调更多依靠已有积压订单,而非新增订单跑赢出货。
对中国供应链而言,托盘级自动化立体仓库是本土设备商出海的重要品类。料箱龙头补齐托盘能力后,海外集成商可以用同一平台同时报价两类方案,中国厂商的出海项目将面对更完整的对手。相关解读见AutoStore是什么?,公司页面见AutoStore。
乐观情形是第四季度营收超过2亿美元,托盘产品随现有客户一起销售;悲观情形是订单再有一个季度低于营收,毛利率继续下滑。值得关注的节点包括第四季度Logiqs交割公告、2027年2月发布的四季度报告中的全年营收,以及AutoStore托盘系统的首个公开客户。
- 约7.5亿美元(原约7亿美元)
- 1.921亿美元,同比增长38.2%
- 1.776亿美元,增长16.5%
- 毛利率71.3%,调整后EBITDA 42.3%
- 最高3000万欧元,现有现金支付
- 移动式托盘AS/RS,约30个客户站点,员工60人
- 约2亿美元(MEKAWIRE测算)
- 预计2026年第四季度
为何重要
Buying Logiqs would extend AutoStore's offering from cube storage into roaming pallet AS/RS, adding a business with about 30 customer sites and 60 employees. The guidance increase to about USD 750 million implies roughly USD 200 million of Q4 revenue, a MEKAWIRE calculation. Q3 revenue grew 38.2%, while order intake grew 16.5%, making order conversion and demand momentum important to assess separately.
竞争对手分析
Logiqs would broaden AutoStore's product coverage as it competes with warehouse automation suppliers including Symbotic, Ocado and Exotec. Symbotic serves retailers and distributors, with Walmart among its customers, while Ocado licenses robotic grocery fulfilment technology. Exotec combines rack-climbing bin retrieval robots with Deepsky software. The supplied facts provide no comparable pricing, margins or win rates to establish a competitive advantage.
估值背景
The acquisition consideration is up to EUR 30 million in cash, with no Logiqs revenue or earnings supplied to calculate transaction multiples. Market capitalizations for listed AutoStore, Symbotic and Ocado are absent. Exotec's USD 2 billion valuation is disclosed, with funding rounds dated 2020 and 2022, but its valuation date is unspecified and no current valuation estimate is supplied.
研究依据
No research papers are supplied, so technical performance claims cannot be assessed against published results. The cited company releases and quarterly update support the transaction and financial reporting.
供应链影响
AutoStore plans to fund the purchase from existing cash, with closing expected in Q4 2026. Logiqs brings 60 employees and about 30 customer sites, creating integration and service obligations to assess. Component suppliers, manufacturing capacity and sourcing dependencies are absent from the supplied material.
后续看点
Watch whether Q4 revenue reaches the roughly USD 200 million implied by guidance, a MEKAWIRE calculation. Track order intake after its 16.5% Q3 increase alongside revenue growth of 38.2%. Closing progress and subsequent gross and adjusted EBITDA margins will help assess execution against the reported 71.3% and 42.3% levels.
分析师观点
The acquisition offers a concrete route to broader warehouse automation coverage, supported by Logiqs' existing customer sites. Its financial contribution remains unquantified because revenue, earnings and integration costs are missing. The raised guidance supports near-term revenue expectations, while slower order growth warrants attention when assessing durability.
值得追问的问题
What revenue, earnings and integration costs does AutoStore expect from Logiqs, and what determines the final consideration within the EUR 30 million ceiling? What backlog conversion assumptions support the implied Q4 revenue, and how will AutoStore sell and service pallet systems through its existing commercial relationships?