액손, 드론기업 스카이디오에 12억달러 투자, 美와 캐나다 경찰 드론 독점 유통
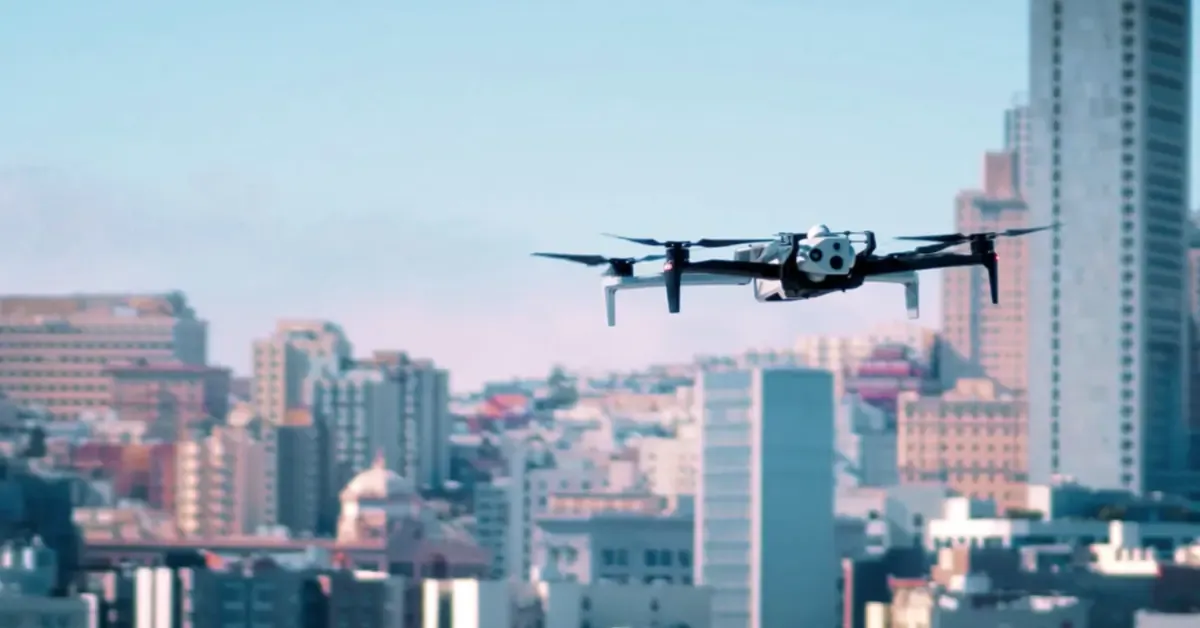
미국 공공안전 장비 기업 액손이 5일 보도자료를 통해 드론 기업 스카이디오에 현금과 자사주로 약 12억달러를 투자한다고 밝혔다. 투자 전 기업가치는 52억달러이며 액손의 완전희석 지분은 약 20%포인트 늘어난다.
이 가운데 스카이디오에 들어가는 신규 자금 약 2억5490만달러는 5일 거래가 종결됐고, 나머지는 기존 주주 지분 매입이다. 액손은 미국과 캐나다 공공안전 시장 독점 유통권을 얻는다.
액손(Axon Enterprise)은 5일 3분기 실적과 함께 낸 보도자료에서 스카이디오(Skydio)에 약 12억달러를 투자한다고 밝혔다. 투자 전 기업가치는 52억달러이고, 이번 거래로 액손의 완전희석 기준 지분이 약 20% 늘어난다. 대금은 현금과 액손 주식으로 치른다. 신규 자본 투입과 기존 주주 지분 매입이 함께 이뤄진다. 같은 날 제출된 8-K 공시에 따르면 신규 투자분은 시리즈G 우선주 2500만주, 주당 10.19617달러, 약 2억5490만달러로 5일 종결됐고, 대금 절반은 현금, 절반은 공개매수 정산 뒤 발행할 액손 주식으로 치른다.
경찰 드론 유통을 쥐다
액손은 미국과 캐나다 공공안전 기관 대상 스카이디오 제품의 독점 유통사가 된다. 양사는 이미 드론 초동대응(DFR) 사업을 함께하고 있다. 보도자료에 따르면 스카이디오의 공공안전 고객은 1500곳이 넘고, 출동한 사건의 약 80%에서 드론이 경찰보다 먼저 도착한다. 스카이디오는 이번 회계연도 수주 약 10억달러를 예상했다. 나머지 거래는 2026년 4분기와 2027년 1분기에 마무리될 예정이다.
- 2020년 7월
- 시리즈C
- 1억달러
- 회사 발표
- 2021년 3월
- 시리즈D
- 1억7000만달러
- 회사 발표
- 2023년 2월
- 시리즈E
- 2억3000만달러
- 회사 발표
- 2024년 11월
- 시리즈E 추가
- 1억7000만달러 이상
- 액손 등 전략 투자자
- 2026년 11월 5일
- 액손 투자
- 약 12억달러
- 신규 2억5490만달러 11월 5일 종결, 나머지 구주 매입, 투자 전 52억달러
시리즈C, D, E와 2024년 추가 투자 합계 6억7000만달러 이상. 신규 투자분 약 2억5490만달러(액손 8-K)는 그 합계의 최대 약 38%(MEKAWIRE 계산).
2026년 11월 14일 기준
MEKAWIRE DB에 있는 스카이디오의 시리즈C, D, E 투자액은 모두 5억달러다. 스카이디오 블로그에 따르면 2024년 11월 시리즈E 추가 투자로 1억7000만달러 이상이 더해졌다. 네 차례 투자 합계는 6억7000만달러를 넘는다. 12억달러 대부분은 기존 주식 매입이라 이 합계와 맞비교하기 어렵고, 스카이디오에 새로 들어가는 2억5490만달러는 그 합계의 최대 약 38%다(MEKAWIRE 계산).
MEKAWIRE 분석
액손이 사는 것은 드론 회사 지분이 아니라 경찰 드론 유통망의 통제권이다.
국내에서도 경찰청이 순찰 드론과 로봇 도입을 확대하고 있어, 장비와 증거관리 소프트웨어를 한 회사가 묶어 파는 미국 모델이 국내 공공 조달에도 참고가 될 전망이다. 반론은 의존도다. 스카이디오의 미국과 캐나다 공공안전 판매가 한 유통사를 거치게 되고, 12억달러의 약 5분의 4는 기존 주주에게 돌아간다(MEKAWIRE 계산).
- 약 12억달러, 현금과 액손 주식
- 투자 전 52억달러
- 완전희석 기준 약 20% 증가
- 미국과 캐나다 공공안전 독점
- 신규 투자분 11월 5일 종결, 나머지 2026년 4분기와 2027년 1분기 예정
- 이번 회계연도 약 10억달러 예상
- 신규 자금 2억5490만달러, 시리즈C부터 E까지 합계 6억7000만달러 이상의 최대 약 38%(MEKAWIRE 계산)
매일 아침 8시, 로봇 산업 1면을 텔레그램으로
주요 기사와 신규 투자, 인수, 제휴를 한 장에 담아 보냅니다. 관심 기업 소식은 들어오는 대로 알립니다.
왜 중요한가
Axon's exclusive US and Canada public-safety distribution agreement ties Skydio's drones to a supplier of body cameras, evidence software and police drone programmes. The headline $1.2 billion investment includes only about $254.9 million of new capital; the remainder purchases existing shares. Investors should separate the potential distribution benefit from the smaller funding injection available to Skydio.
경쟁사 비교
Exclusivity could strengthen Skydio's access to public-safety buyers through Axon, making distribution a competitive factor alongside drone autonomy, docks and software. Its stated scope is US and Canada public safety, so it does not establish exclusivity across Skydio's defence or infrastructure businesses. No rival pricing, contract wins or market-share figures are supplied to measure the competitive effect.
밸류에이션 맥락
The disclosed $5.2 billion figure is Skydio's pre-money valuation, not a public-market capitalization; Axon's market cap is not supplied. Against about $1 billion in expected fiscal-year bookings, it implies roughly 5.2 times bookings, not revenue. The $1.2 billion transaction mixes primary and secondary purchases and should not be treated entirely as new funding.
근거가 된 연구
No research papers are supplied. The press release, Skydio blog and Axon 8-K support the transaction context, but the input provides no research evidence for autonomy performance or deployment economics.
공급망 파급
Skydio builds autonomous drones, docks and software, but the input names no component suppliers, manufacturing capacity or production constraints. The $254.9 million primary purchase adds capital, while secondary purchases transfer ownership without funding production. Whether supply can support demand through Axon's distribution channel remains unquantified.
지켜볼 신호
Watch whether the remaining purchases close as expected in Q4 2026 and Q1 2027. Track whether Skydio achieves about $1 billion in expected fiscal-year bookings and whether those bookings convert into revenue and cash. Distribution economics, deployment volumes and margins are not supplied and would help assess the agreement's value.
애널리스트 시각
The strategic case rests on combining Skydio's autonomous drone offering with Axon's public-safety distribution position. The financing headline overstates the fresh capital reaching Skydio: MEKAWIRE calculates that the primary portion is at most about 38% of its combined Series C through E rounds. The investment case still needs evidence on distribution economics and bookings conversion.
따져봐야 할 질문
What margins, minimum commitments and duration govern Axon's exclusive distribution agreement? How much of Skydio's expected bookings comes from public safety, and when will those bookings become revenue and cash? What ownership percentage will Axon hold after all closings, and how is consideration divided between cash and Axon stock?