ugo borrows JPY 1bn from Mizuho, Bank of Yokohama and JFC to build ugo Nova
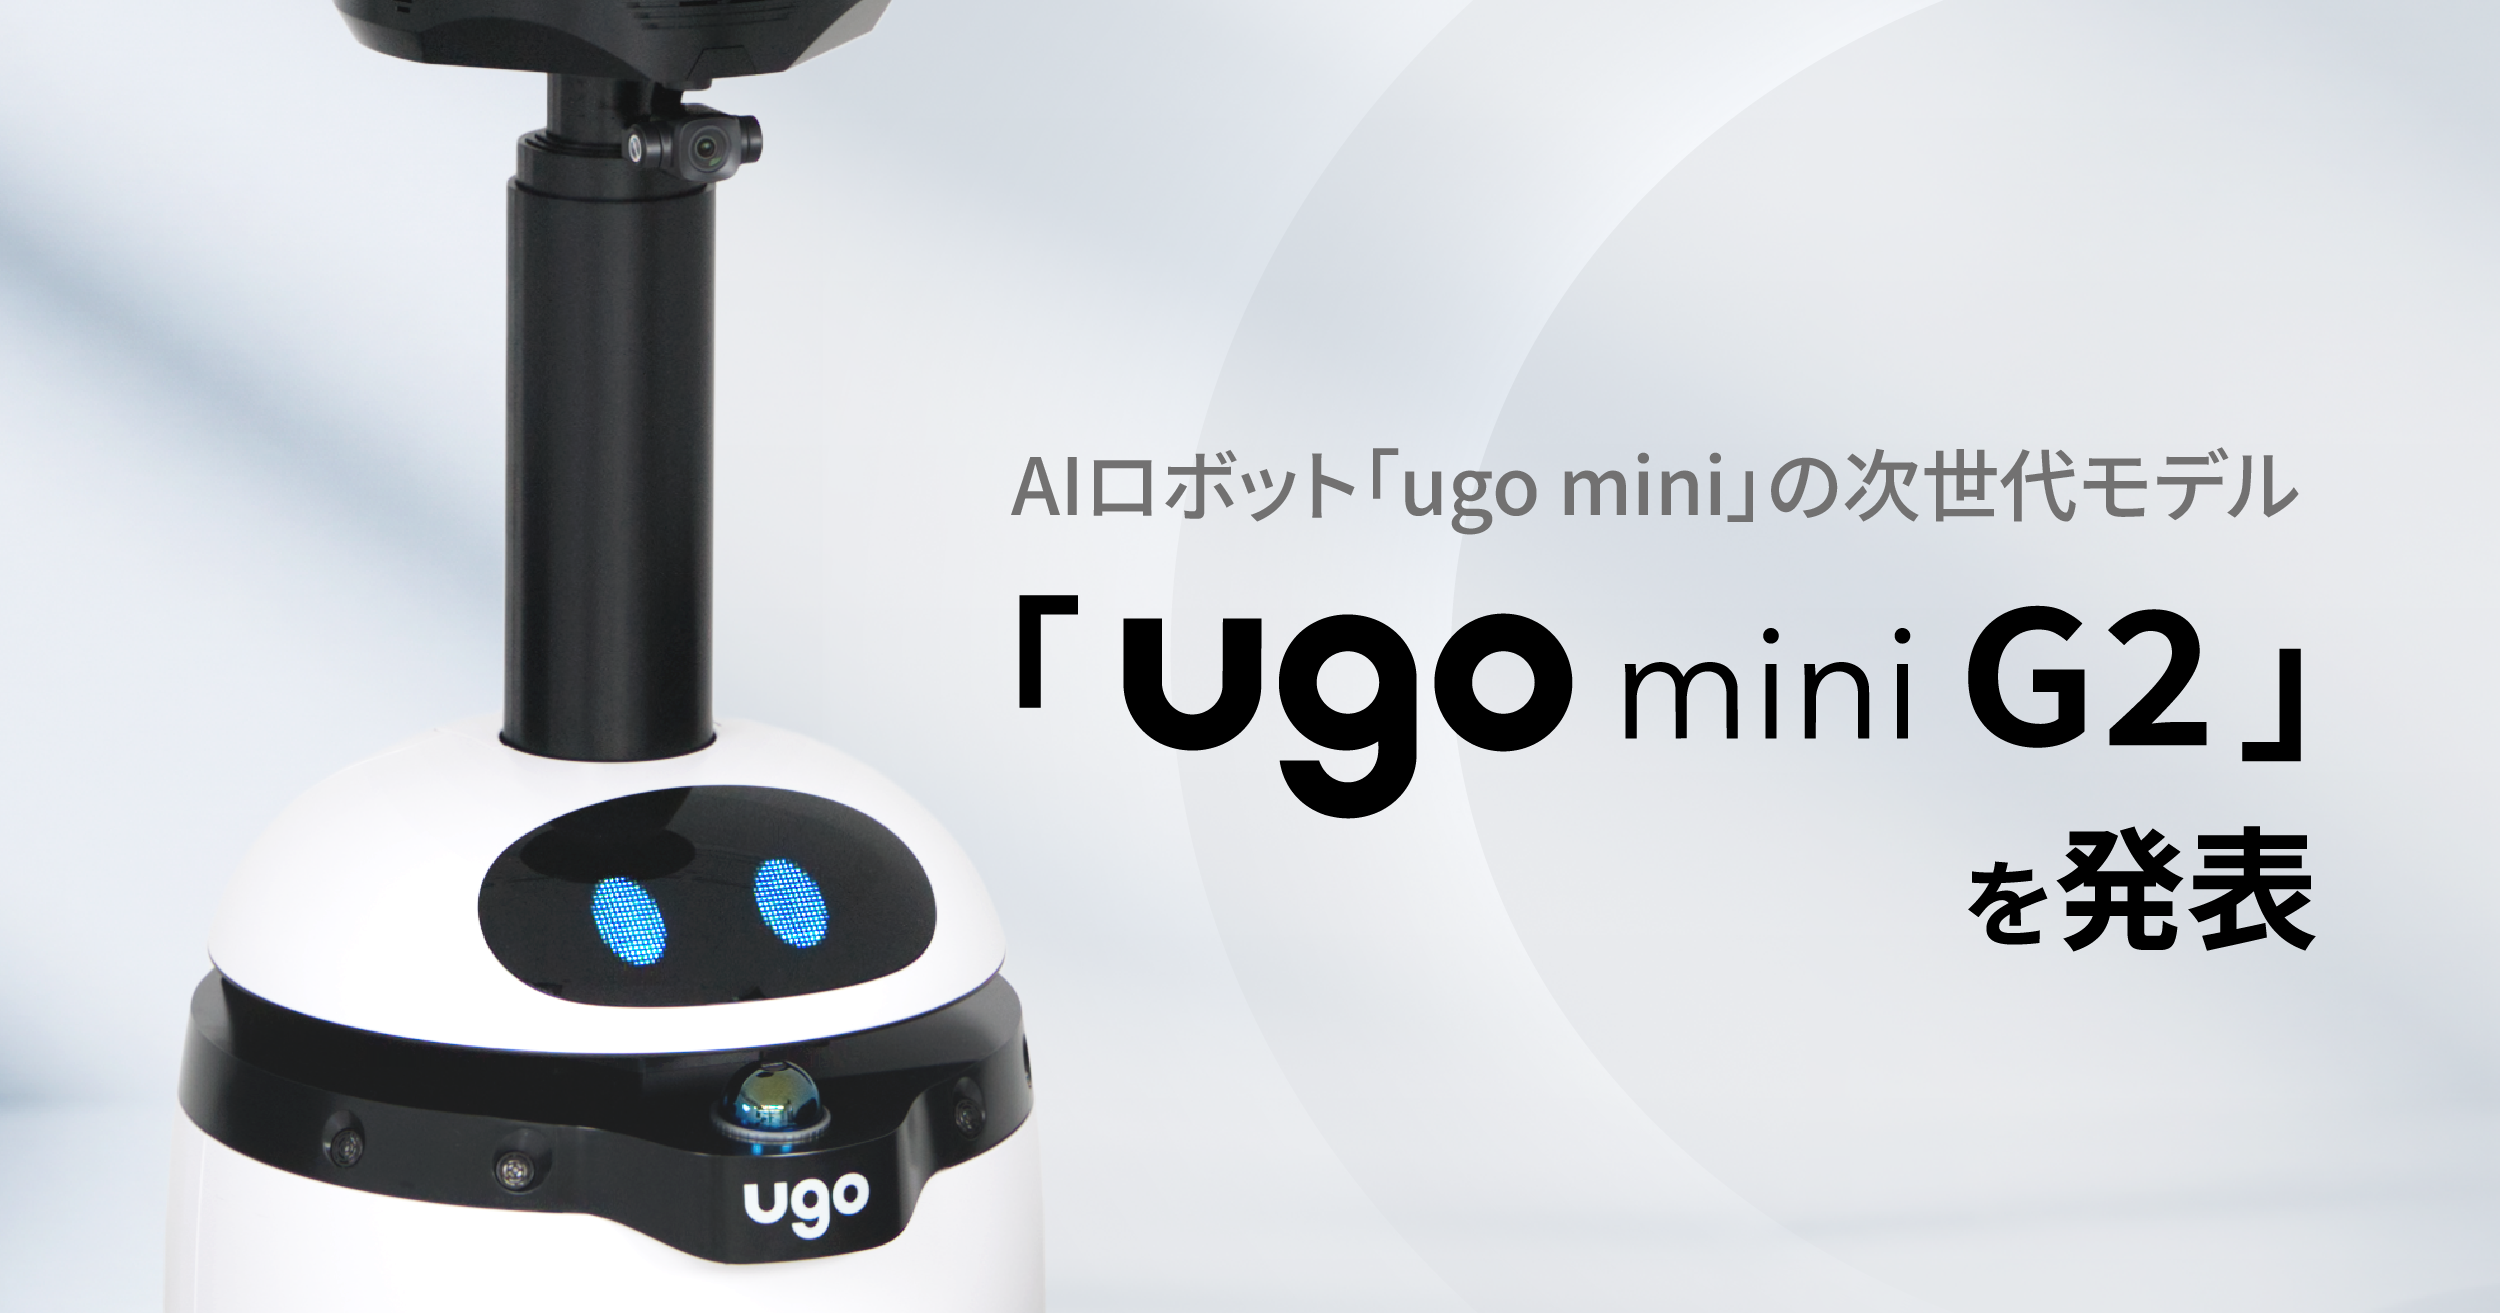
Tokyo robot maker ugo has raised JPY 1 billion in debt from Mizuho Bank, the Bank of Yokohama and the state-owned Japan Finance Corporation, taking its cumulative funding to about JPY 5 billion, the company said in a press release on Oct 21.
The money goes to AI models, mass production of the ugo Nova semi-humanoid and physical-AI services, one day after ugo opened orders for its ugo mini G2 inspection robot.
ugo, the Tokyo developer of security and inspection robots, said in a press release on Oct 21 that it has borrowed a total of JPY 1 billion from Mizuho Bank, the Bank of Yokohama and Japan Finance Corporation, the government-owned policy lender. The company said the loans lift its cumulative fundraising to about JPY 5 billion. It did not give the split between the three lenders, the interest rate or the maturity.
The timing matters more than the size. The financing came one day after ugo opened advance orders for the ugo mini G2 and said it had moved production of that robot to a domestic electronics contractor, after more than 100 units of the first ugo mini shipped. Lenders, unlike venture investors, are paid from cash flow, so a bank facility for a robot start-up is a statement that the business already sells something.
Where the JPY 1 billion goes
ugo listed three uses. The first is AI models that let its robots read a site and decide and act on their own. The second is the development and mass production of its own Japanese-made robots, starting with the ugo Nova, the semi-humanoid for physical-AI work that the company unveiled in September 2026. The third is physical-AI services that combine those models and robots with a platform for collecting field data, built with partner companies and aimed first at manufacturing.
ugo was founded in 2018 and is led by chief executive Ken Matsui. Its line-up is the ugo Pro for patrol and reception, the ugo mini for inspection rounds in plants, power stations and data centres, and the ugo Platform fleet software, plus a data-collection business (ugo Data Factory) and a robot foundation-model service (ugo Model Lab), according to the release.
MEKAWIRE analysis
Debt instead of a new equity round says ugo is now financing production and working capital, not discovery, and that Japanese banks are willing to lend against robots that already earn revenue.
By MEKAWIRE's arithmetic the loans are about a fifth of the roughly JPY 5 billion ugo has raised in total, and the JPY 850 million third-party share allotment recorded in MEKAWIRE's database for January 2024 is smaller than this single debt package. Japan Finance Corporation's presence is typical of Japanese hardware start-ups that have customers but want to avoid dilution before a larger round or a listing. The counter-argument is that debt carries fixed repayments: if ugo Nova orders lag, interest and principal fall due while the production line is still being paid for.
- Jan 2024
- Third-party share allotment
- JPY 850m
- MEKAWIRE database
- May 2025
- Third-party share allotment
- Undisclosed
- MEKAWIRE database
- Oct 21, 2026
- Debt (Mizuho, Bank of Yokohama, JFC)
- JPY 1bn
- ugo release
- Total to date
- All rounds
- About JPY 5bn
- ugo release
Disclosed figures only. Debt share of cumulative funding: 1 / 5 = about 20% (MEKAWIRE arithmetic).
As of Oct 21, 2026
The open question is the ugo Nova itself. ugo has disclosed neither a price nor a delivery date for the semi-humanoid, and the release speaks of building a production system rather than of orders. The next signals are the first ugo mini G2 deliveries on Nov 24, any ugo Nova customer or price announcement, and whether ugo follows the loans with an equity round.
- JPY 1 billion in debt financing
- Founded 2018, Tokyo; CEO Ken Matsui
- Mizuho Bank, Bank of Yokohama, Japan Finance Corporation
- ugo press release, Oct 21, 2026
- AI models, ugo Nova semi-humanoid development and mass production, physical-AI services
- Split by lender, interest rate, maturity
- About JPY 5 billion, per the company
Why it matters
Japanese service-robot makers have mostly funded themselves with equity from corporates and venture funds. A three-bank package that includes the state policy lender suggests ugo's revenue from the ugo mini and ugo Pro is now visible enough to support repayments, which changes how it can pay for the ugo Nova ramp.
It also sequences the company's next steps: contract manufacturing for the G2 (Oct 20), debt for production (Oct 21), and a semi-humanoid that still has no announced price.
Rival analysis
In Japanese inspection and security robots ugo competes for the same facility budgets as larger groups' in-house programmes and imported quadrupeds. Its distinction is a domestically made wheeled platform with an arm-mounted camera and its own fleet software. MEKAWIRE's database has few disclosed 2026 Japanese robotics rounds with amounts, so a like-for-like comparison is not yet possible.
Valuation context
No valuation was disclosed, and debt implies none. The only equity figure on record is the JPY 850 million allotment of January 2024. A future equity round would be the first chance to see how investors price the ugo Nova pivot.
Supply-chain implications
ugo moved ugo mini G2 production to an unnamed domestic EMS contractor. The release stresses Japanese-made robots, which matters for customers in power, rail and plants that prefer domestic suppliers for security reasons.
Signals to watch
Nov 24, 2026: first ugo mini G2 deliveries. Any ugo Nova price, order or delivery date. A follow-on equity round or listing plan.
Analyst view
Thesis: ugo is shifting from a venture-funded developer to a producer financed partly by banks. Confidence medium: the move is consistent with 100+ units shipped and EMS production, but ugo has not disclosed revenue or loan terms.
Questions you should be asking
What are the maturity and rate of the loans? How much of the JPY 1 billion is reserved for ugo Nova tooling? When will ugo Nova ship and at what price? What share of revenue now comes from ugo mini?