中国、ソフトバンクによるABBロボット中国事業の買収を禁止 ABB「緊密に協議」
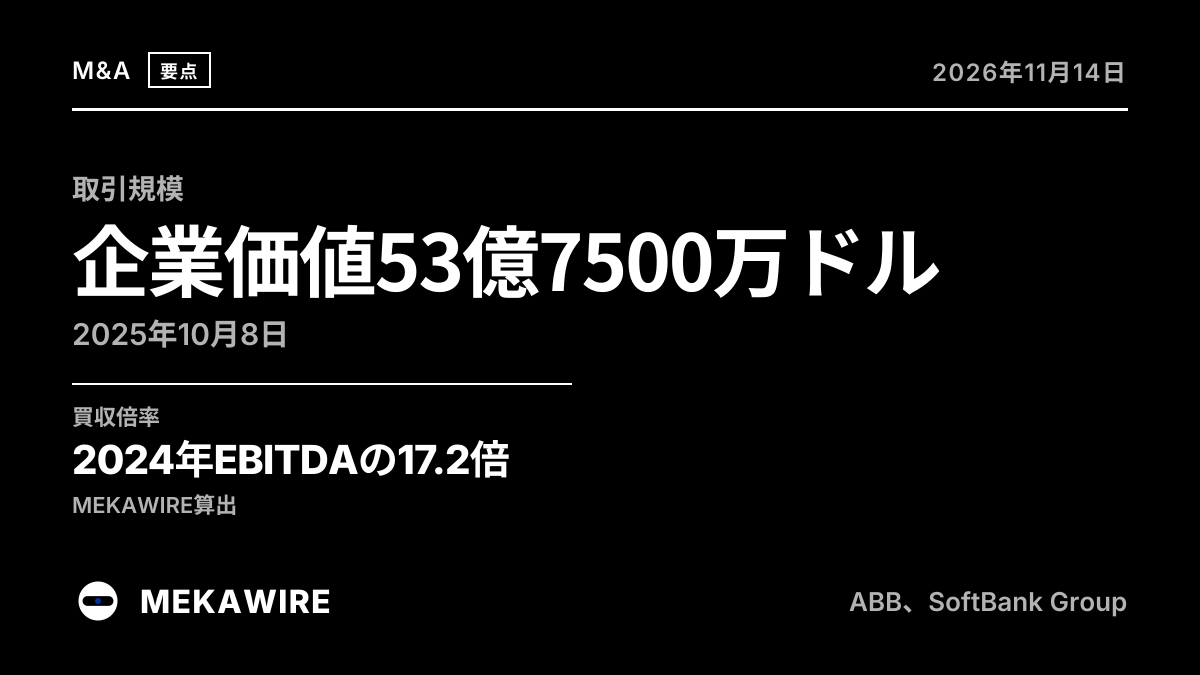
スイスのABBは5日、中国の外国投資安全審査機関がABBロボティクスの中国事業の買収を禁止したとソフトバンクグループから通知を受けたと明らかにした。2025年10月に合意した企業価値53億7500万ドルの取引の一部で、両社は緊密に協議しているという。ブルームバーグとロイターは9日、中国事業の分離案を検討中と報じたが、両社は確認していない。
ABBは5日の声明で、中国の外国投資安全審査工作メカニズム弁公室がABBロボティクス中国事業の買収を禁止したとソフトバンクグループから伝えられたと明らかにした、とザ ロボット レポートなどが報じた。同弁公室は国家発展改革委員会の下にある。ABBは両社が緊密に対話し、取引に建設的に取り組んでいるとした。MEKAWIREはABBサイト上の声明原文を確認できておらず、文言は報道に基づく。
欧州は承認、中国で停止
ソフトバンクは2025年10月8日、ABBのロボット事業を企業価値53億7500万ドルで買収することで合意した。ABBがそれまで検討していた事業の分離上場に代わる案だった。欧州委員会は2026年3月11日に簡易手続きで承認した。報道によれば中国の独占禁止審査は通過しており、今回は別の外国投資安全審査で止まった。MEKAWIREは3月時点で買収額を2024年EBITDAの17.2倍と算出している。
- 2025年10月8日
- 企業価値53億7500万ドルで買収合意
- ABBとソフトバンクの発表
- 2026年3月11日
- 欧州委員会が承認
- EUR-Lex決定
- 2026年11月5日
- 中国の安全審査が中国事業の買収を禁止
- ABB声明、報道
- 2026年11月9日
- 中国事業の分離を協議と報道
- ブルームバーグとロイター、未確認
一次資料と明示した報道に基づきMEKAWIREが作成。
2026年11月14日時点
中国事業の分離案
ブルームバーグとロイターは9日、両社が中国事業を別法人に切り出すか、売却対象から外す案を協議していると報じた。両社は確認していない。
MEKAWIRE分析
今回の判断でABBロボティクスは、ソフトバンクに渡せない中国事業と売却可能な残りの事業に分かれた。
英フィナンシャル タイムズは、ロボットのデータが国外に流出しAI学習に使われる懸念が審査理由になったと報じた。ソフトバンクのフィジカルAI戦略の中核案件であり、中国に大きな設置基盤を持つファナックや安川電機にとっても、資本構成の変更が同様の審査対象になりうることを示した。
- 企業価値53億7500万ドル(2025年10月8日)
- 外国投資安全審査が中国事業の買収を禁止
- 緊密に協議、建設的に推進(11月5日)
- 2026年3月11日承認
- 2024年EBITDAの17.2倍(MEKAWIRE算出)
- 11月9日にブルームバーグとロイターが報道、未確認
なぜ重要か
China's prohibition puts the agreed scope of SoftBank's ABB Robotics acquisition in question despite EU clearance on March 11, 2026. The decision covers the China business; the supplied facts do not establish the outcome for the remaining transaction. Investors need clarity on which operations SoftBank can acquire before assessing the deal's strategic reach.
競合分析
The regulatory block creates uncertainty around SoftBank's acquisition, but the supplied material identifies no rival bidders or competitor responses. SoftBank also led Skild AI's $1.4 billion Series C in January 2026, showing another robotics-related investment commitment. No integration plans or competitive performance comparisons are supplied.
企業価値の背景
The disclosed $5.375 billion figure is the enterprise value agreed for ABB's robotics division in October 2025, not ABB's or SoftBank's market capitalization. The 17.2x 2024 EBITDA multiple is a MEKAWIRE calculation, not a separately disclosed valuation. No revised price, China business valuation or current market capitalization is supplied, so any carve-out valuation would be speculative.
裏付けとなる研究
No research papers are included in the supplied material. The evidence concerns transaction terms and regulatory decisions, so it does not support conclusions about robotics technology performance.
サプライチェーンへの影響
The supplied facts do not identify factories, suppliers, component dependencies or arrangements for serving customers across a potential China carve-out. If the companies confirm a carve-out, disclosures on manufacturing, sourcing and service responsibilities would help establish operational consequences.
今後の注目点
Watch for company confirmation of the China carve-out reported by Bloomberg and Reuters on November 9; neither company has confirmed it. Revised transaction scope, consideration and closing terms would provide a firmer basis for assessing value. ABB's November 5 statement establishes continued dialogue, not an agreed restructuring.
アナリストの見方
Treat this as an unresolved change to transaction scope, with potential valuation consequences. EU clearance does not resolve China's prohibition, and constructive dialogue does not establish a viable revised deal. The investment assessment should turn on confirmed terms rather than the reported carve-out discussions.
問うべき論点
Can ABB and SoftBank agree on a transaction structure that addresses the prohibition on acquiring the China business? If China is excluded, what price adjustment and operating arrangements would apply? Neither answer is provided in the supplied material.