Vbot maker Vita Dynamics valued at RMB 3bn: Jiangte Motor invests RMB 100M
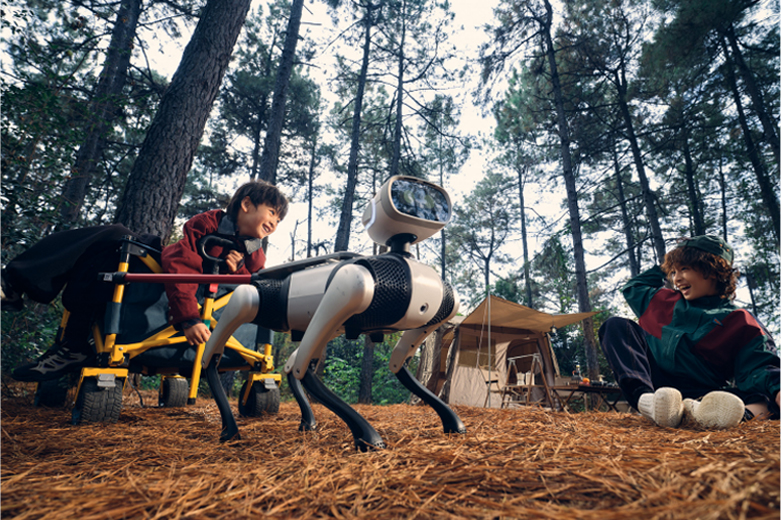
Vita Dynamics, maker of the Vbot consumer robot dog, is raising RMB 300M at a RMB 3bn pre-money valuation, with Shenzhen-listed Jiangte Motor paying RMB 100M for 3.03%, a filing dated Oct 13 shows; the start-up had H1 2026 revenue of RMB 10.94M and a RMB 50.06M net loss.
Vita Dynamics, the Beijing start-up behind the Vbot consumer robot dog, has agreed a RMB 300M Pre-A+++ round at a pre-money valuation of RMB 3bn, according to a related-party disclosure that Shenzhen-listed Jiangxi Special Electric Motor (Jiangte Motor, 002176) filed on Oct 13. Jiangte will pay RMB 100M for 3.0303% of the enlarged company. A vehicle being set up by Jiangte chairman Wang Xin, owned 90% by his Beijing Wubaiyingli Technology and 10% by Beijing Xinxuetang, pays the other RMB 200M for 6.0606%. Jiangte's board approved the deal on Oct 12, with Wang abstaining.
The filing puts real numbers on a consumer robot-dog maker
The disclosure is the first primary document MEKAWIRE has seen that shows Vita Dynamics' accounts. Unaudited consolidated revenue was RMB 10.94M in the first half of 2026 against RMB 48,515 for the whole of 2025, and the company lost RMB 50.06M in the half after RMB 63.93M last year. Net assets stood at RMB 363.0M on Jun 30. The round prices each yuan of registered capital at about RMB 1,700.25, which gives a post-money value of RMB 3.3bn (3,000 + 300, MEKAWIRE calculation). The filing says the pre-money figure is above the valuation of the company's previous round but does not state that earlier price.
Vita was registered on Dec 9, 2024 in Haidian, Beijing. Founder and legal representative Yu Yinan, who holds a doctorate from the Institute of Automation of the Chinese Academy of Sciences and was a founding core member of Horizon Robotics, keeps 30.31% after the round. Horizon's Beijing R&D unit holds 3.03%, two Hillhouse funds 1.84% combined, and Lenovo Capital, Fortune Capital, Huatai Zijin and Cathay Capital funds also appear on the register. The new shareholder agreement gives Yu five of nine board seats, with Hillhouse, Horizon, Today Capital and Wang's vehicle naming one director each.
- Pre-money valuation (Pre-A+++)
- RMB 3.0bn
- Round size so far
- RMB 300M (Jiangte RMB 100M, Wang Xin vehicle RMB 200M)
- Post-money (MEKAWIRE calc.)
- RMB 3.3bn
- Price per yuan of registered capital
- about RMB 1,700.25
- H1 2026 revenue (unaudited)
- RMB 10.94M
- H1 2026 net loss
- RMB 50.06M
- FY2025 revenue / net loss (unaudited, consolidated)
- RMB 48,515 / RMB 63.93M
- Net assets, Jun 30, 2026
- RMB 363.0M
Source: Jiangte Motor related-party investment announcement 2026-077, Oct 13, 2026. Post-money = 3,000 + 300. Shares may change if more investors join the round.
As of Oct 19, 2026
Why a motor maker is paying 8.3 times book
Jiangte makes servo and joint-module motors for industrial, collaborative and quadruped robots, and the filing says the two companies are already co-developing motors and key parts for a dexterous robot hand that Jiangte may later sell to other robot makers. The RMB 3bn pre-money price is 8.3 times Vita's net assets at the end of June (3,000 / 363.0), for a business whose half-year revenue was 225 times its 2025 total but is still small in absolute terms. Jiangte's RMB 100M equals 3.38% of its own latest audited net assets, so the stake is material for the investor but buys no control: Vita stays off Jiangte's consolidated accounts.
- Vita Dynamics
- Pre-A+++
- RMB 300M
- 2026-10-13
- D-Robotics
- Series C
- US$400M
- 2026-09-17
- Unitree Robotics
- STAR Market IPO
- valued about RMB 61bn at issue
- 2026-08-18
- LimX Dynamics
- Pre-IPO
- US$200M
- 2026-07-14
- EngineAI
- Series B
- US$200M
- 2026-04-10
Disclosed figures from primary sources in the MEKAWIRE database as of 2026-10-19; not estimates, not converted. Pre-money / net assets = 3,000 / 363.0 = 8.3x.
As of Oct 19, 2026
MEKAWIRE analysis
Jiangte is buying a parts customer and a dexterous-hand programme as much as a minority stake; the price is a bet on Vbot volume that the first-half accounts do not yet show.
Against the Chinese legged and embodied-AI rounds in MEKAWIRE's database, RMB 300M is mid-sized: D-Robotics, the Horizon chip spin-off, raised US$400M in September, and LimX Dynamics and EngineAI each disclosed US$200M rounds this year. Vita's RMB 3.3bn post-money is about 5.4% of the roughly RMB 61bn at which Unitree Robotics listed on the STAR Market in August (3.3 / 61; see our [Unitree explainer](/news/unitree-robotics-company-profile-quadrupeds-humanoids-ipo-20261002)). The strongest counter-argument is that consumer robot dogs have not yet proved repeat demand; the filing itself warns that the segment is at an early commercial stage. The bull case is that a quadruped sold in volume gives Jiangte a high-unit-count motor and hand programme; the bear case is that losses outrun revenue (RMB 4.58 of loss per yuan of sales in the half) and the related-party structure draws scrutiny of a chairman who is co-investing alongside the listed company. Signals to watch: closing before the Nov 30, 2026 long-stop date, whether other investors join the round at the same price as the agreement allows, and any Jiangte disclosure on dexterous-hand motor orders.
- Pre-A+++, RMB 300M so far, RMB 3bn pre-money
- Vita Dynamics (维他动力), Beijing, founded Dec 9, 2024; Vbot quadruped robot dog
- Revenue RMB 10.94M, net loss RMB 50.06M (unaudited)
- Dexterous-hand motors and key parts, co-developed with Jiangte
- RMB 363.0M on Jun 30, 2026
- RMB 100M for 3.0303% (002176.SZ)
- Nov 30, 2026
- RMB 200M for 6.0606%, controlled by Jiangte chairman Wang Xin
Why it matters
This is the first primary-source look at the accounts of a Chinese consumer quadruped maker outside Unitree. It shows a company that went from almost no revenue in 2025 to RMB 10.94M in one half while still losing RMB 50M, and it shows a listed motor supplier paying a premium to sit closer to a high-volume robot platform.
For component makers the structure matters as much as the price: the investment comes with joint development of dexterous-hand motors that Jiangte may sell to third parties, the pattern Chinese suppliers are using to lock in design wins.
Rival analysis
Unitree remains the reference: it listed on the STAR Market in August at roughly RMB 61bn and already earns more from humanoids than from quadrupeds, per its filings. Vita positions Vbot as a consumer product and is moving into humanoids, so it competes with Unitree on both fronts at about one-twentieth of the value.
Horizon's presence on the register and on the board links Vita to the D-Robotics chip ecosystem, which reports more than 20 robot customers for its S600 part.
Valuation context
RMB 3bn pre-money is 8.3 times net assets of RMB 363.0M and 274 times first-half revenue (3,000 / 10.94), so the price rests on expected volume. The filing says the pre-money exceeds the previous round's valuation but gives no number, so the step-up cannot be computed from primary data.
Redemption rights carry an 8% simple annual return for Pre-A+++ investors, and anti-dilution protection applies to any lower-priced issue, which puts a floor under this round's investors at the expense of later ones.
Supply-chain implications
Jiangte supplies servo and joint-module motors to industrial, collaborative and quadruped robot makers. The joint dexterous-hand project, still at R&D stage per the filing, would add a high-count actuator line: a hand needs many small motors per unit.
The filing also records Jiangte's April 2026 joint venture with Zidong Taichu in AI, showing the group building a robotics position on several fronts.
Signals to watch
1) Closing and business-registration change before the Nov 30, 2026 long-stop date. 2) Whether additional investors join at the same RMB 1,700.25 per registered-capital price, which would dilute the stated percentages. 3) Jiangte's next periodic report for the fair-value treatment of the stake and any hand-motor revenue.
Analyst view
Confidence: medium. The facts are filed and audited where stated, but Vita's 2026 numbers are unaudited and the sales trajectory beyond June is not disclosed. We read the deal as a supplier securing a platform customer at a full price.
Questions you should be asking
How many Vbot units has Vita delivered, and at what average price? What share of Vita's motor bill does Jiangte supply today? Why does the chairman's vehicle take twice the listed company's stake, and on what terms could it exit?