韓国ロボット上場企業の7〜9月期、ラオンとマキナロックスが伸び、ニューロメカとキュレクソは後退
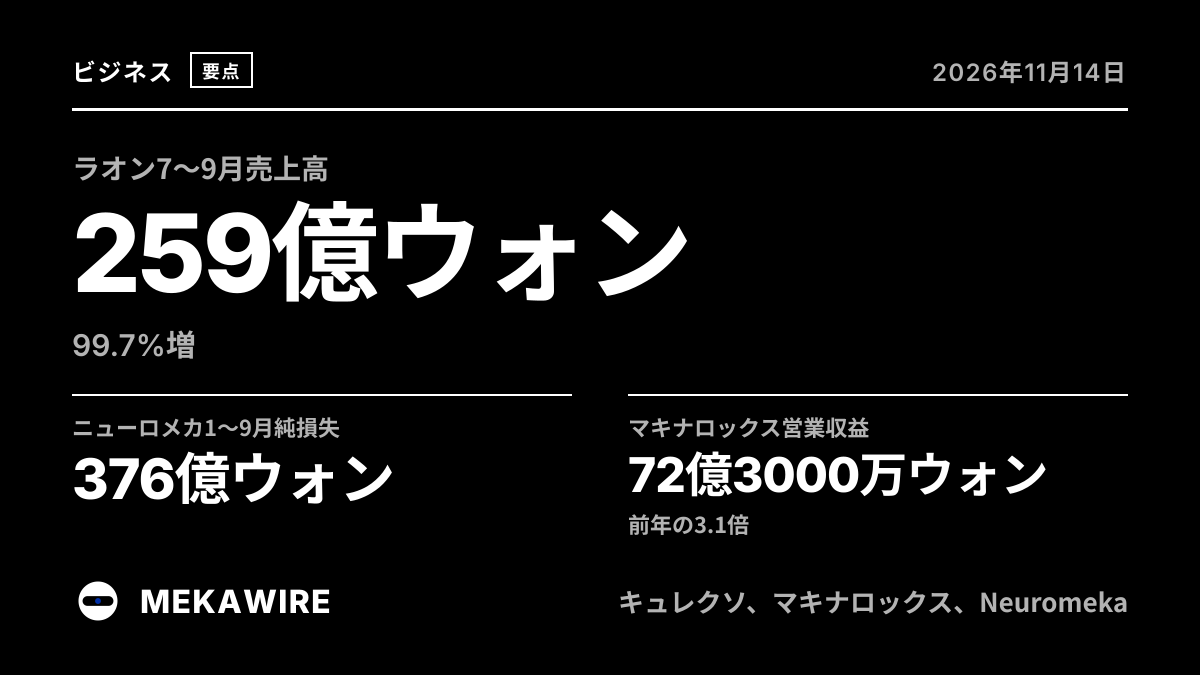
韓国KOSDAQ上場のロボット企業4社が13日、DARTに7〜9月期報告書を提出した。ウエハー搬送ロボットのラオンロボティクスは売上高が259億ウォンと倍増し、産業AIのマキナロックスは3.1倍になった。協働ロボットのニューロメカは37.9%の減収、手術ロボットのキュレクソは営業赤字に転じた。MEKAWIREが連結決算から集計した。
ラオンロボティクス、マキナロックス、ニューロメカ、キュレクソの4社は13日、9月末までの四半期報告書をDARTに提出した。MEKAWIREが連結損益計算書を比べると、半導体工場や工場AI向けの2社が大きく伸び、協働ロボットと手術ロボットの2社は落ち込んだ。
- ラオンロボティクス
- 259
- +99.7%
- 37
- 10
- 583
- +50.3%
- キュレクソ
- 147
- -14.4%
- -19
- 3
- 545
- +1.4%
- マキナロックス
- 72
- +213.8%
- -44
- -26
- 143
- +189.5%
- ニューロメカ
- 28
- -37.9%
- -70
- -32
- 86
- -22.5%
11月13日提出のDART四半期報告書の連結損益計算書。増減率はMEKAWIRE算出。
2026年11月14日時点
ラオンロボティクスの7〜9月期売上高は前年同期比99.7%増の259億ウォン、営業利益は37億1000万ウォンだった。10月30日の速報値(1〜9月の営業利益54億4000万ウォン)は今回の個別決算と一致し、連結では50億2000万ウォンとなる。
マキナロックスの営業収益は72億3000万ウォンと前年の3.1倍だが、営業損失は43億9000万ウォンに拡大した。ニューロメカは売上高27億8000万ウォンで37.9%減、営業損失70億ウォン。1〜9月の金融費用247億ウォンが響き、純損失は376億ウォンと2025年通期の220億ウォンを上回った。キュレクソは14.4%減収で、営業損失18億8000万ウォンを計上した。
MEKAWIRE分析
韓国の上場ロボット企業の売上は、協働ロボット市況ではなく半導体とAIの設備投資に連動するようになった。
ラオンの顧客である半導体工場の投資は日本の搬送ロボット大手にも追い風となる一方、ニューロメカの減収は中国勢の価格攻勢が協働ロボット全体に及んでいることを示す。前年の水準が低かった点は割り引いて見る必要がある。
- 259億ウォン、99.7%増
- 72億3000万ウォン、前年の3.1倍
- 27億8000万ウォン、37.9%減
- 18億8000万ウォンの赤字
- 376億ウォン
- 速報54億4000万(個別)、連結50億2000万ウォン
- DART四半期報告書、11月13日
なぜ重要か
The filings show sharply diverging revenue trends: Raon grew 99.7% to KRW 25.9bn and MakinaRocks reached KRW 7.23bn, 3.1 times a year earlier, while Neuromeka fell 37.9% to KRW 2.78bn. Curexo moved from KRW 0.34bn operating profit to a KRW 1.88bn operating loss. Investors should assess each business separately because these companies serve different markets.
競合分析
Neuromeka's collaborative robots overlap with offerings from Rainbow Robotics and Doosan Robotics, but the input provides no rival financial results or market shares. Rainbow's status as a Samsung subsidiary is relevant strategic context, although no resulting orders are disclosed here. Raon's semiconductor and biotech automation, MakinaRocks' industrial AI and Curexo's medical robots limit the usefulness of treating all four reporting companies as direct competitors.
企業価値の背景
The input supplies no market capitalizations, disclosed valuations or valuation estimates, so revenue growth alone cannot establish relative investment value. Share prices, share counts and comparable financial metrics are missing. For earnings comparisons, Raon's preliminary nine-month operating profit of KRW 5.44bn was on a separate basis, versus KRW 5.02bn consolidated; these figures should not be treated as interchangeable.
裏付けとなる研究
The supplied title Safety Standards and Deployment Patterns of Collaborative Robots in Korean SMEs is relevant to cobot deployment, but no findings are provided. DexStitch concerns dexterous skills learned from human videos; the input establishes no connection to these companies' financial results.
サプライチェーンへの影響
Raon supplies wafer transfer robots for semiconductor equipment, while MakinaRocks sells AI software to manufacturers and defence customers. Neuromeka supplies cobots and automation systems, and Curexo supplies surgical and rehabilitation robots. Supplier identities, component sourcing, inventory, production capacity and delivery lead times are missing, preventing a grounded assessment of supply constraints.
今後の注目点
Watch whether Raon and MakinaRocks sustain revenue growth and whether that growth translates into consolidated operating profit and cash generation. For Neuromeka, track liquidity and financing after its KRW 37.6bn nine-month net loss, alongside the outcome of the April 24 rights offering. Curexo's next operating result will help show whether its Q3 loss persists; the input gives no explanation for the reversal.
アナリストの見方
These results support selective analysis rather than a single Korean robotics growth thesis: revenue momentum differs sharply, and the companies have distinct business models. Neuromeka warrants closer balance-sheet scrutiny because its nine-month net loss already exceeds FY2025's KRW 22.0bn loss. Cash balances, debt, cash flow and order backlogs are missing, so the filings summarized here cannot establish funding runway or recovery prospects.
問うべき論点
What drove Raon's and MakinaRocks' revenue increases, and how much came from repeat customers or recurring contracts? What are Neuromeka's cash balance, cash burn and rights-offering proceeds, and what caused Curexo's operating reversal?