로봇 상장사 3분기 성적표, 라온로보틱스와 마키나락스 성장, 뉴로메카와 큐렉소 후퇴
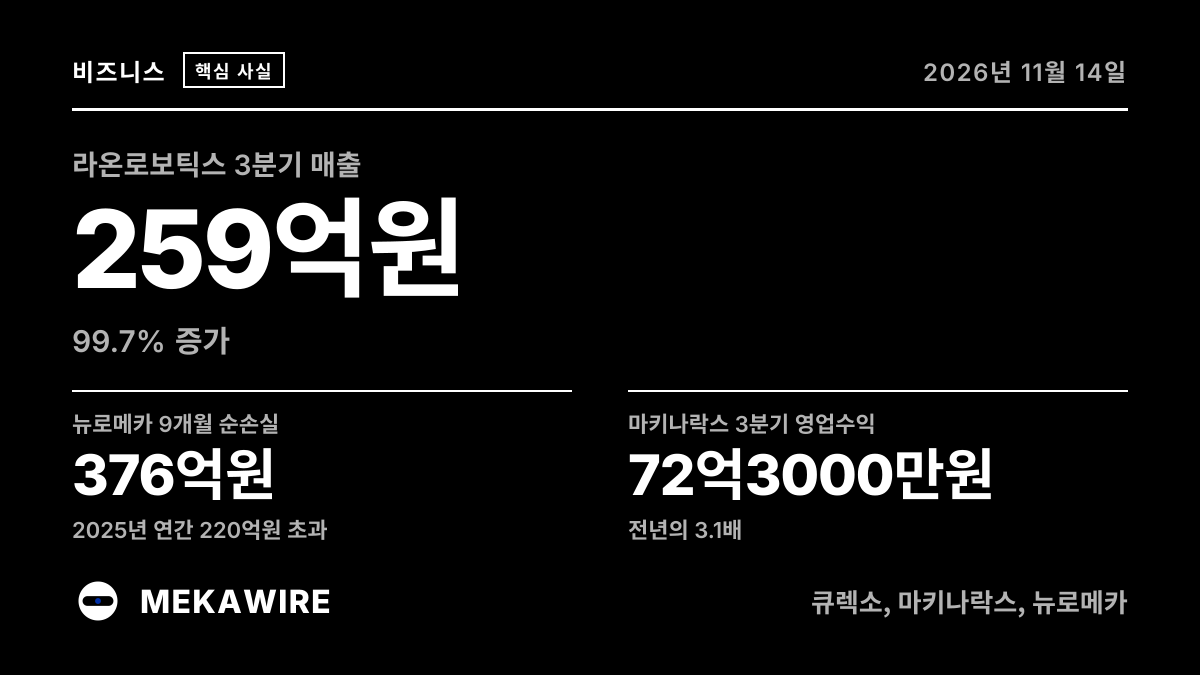
코스닥 상장 로봇 기업 4곳이 13일 DART에 3분기 보고서를 제출했다. 라온로보틱스는 3분기 매출이 259억원으로 99.7% 늘었고 마키나락스는 72억원으로 3배가 됐다. 반면 뉴로메카 매출은 28억원으로 37.9% 줄었고 큐렉소는 영업손실 19억원으로 적자 전환했다.
뉴로메카의 9개월 순손실 376억원은 최근 두 해 연간 손실을 모두 넘었다. MEKAWIRE가 연결재무제표를 직접 집계했다.
라온로보틱스와 마키나락스, 뉴로메카, 큐렉소가 13일 9월 말 기준 분기보고서를 DART에 제출했다. MEKAWIRE가 네 회사의 연결 포괄손익계산서를 비교한 결과 반도체 팹과 공장 AI에 납품하는 두 곳은 빠르게 성장했고, 협동로봇과 수술로봇 업체는 뒷걸음질했다.
- 라온로보틱스
- 259
- +99.7%
- 37
- 10
- 583
- +50.3%
- 큐렉소
- 147
- -14.4%
- -19
- 3
- 545
- +1.4%
- 마키나락스
- 72
- +213.8%
- -44
- -26
- 143
- +189.5%
- 뉴로메카
- 28
- -37.9%
- -70
- -32
- 86
- -22.5%
11월 13일 DART 분기보고서 연결 포괄손익계산서. 마키나락스는 영업수익. 증감률은 MEKAWIRE가 원 단위 공시 금액으로 계산했다.
2026년 11월 14일 기준
라온로보틱스, 잠정 실적과 차이
진공 웨이퍼 이송로봇 업체 라온로보틱스의 3분기 매출은 259억원으로 전년 동기 130억원보다 99.7% 늘었고 영업이익은 37억1000만원(전년 10억3000만원)이었다. 다만 10월 30일 잠정 공시의 9개월 매출 589억원과 영업이익 54억4000만원은 이번 보고서의 별도재무제표 수치와 같고, 연결 기준으로는 583억원과 50억2000만원이다. 두 수치 모두 기준에 따라 맞으며 다른 회사와 비교할 때는 연결 기준을 써야 한다.
마키나락스 현금 331억원
산업 AI 소프트웨어 업체 마키나락스의 3분기 영업수익은 72억3000만원으로 1년 전 23억원의 3.1배였다. 영업손실은 43억9000만원으로 커졌다. 9월 말 현금성자산은 331억원으로 지난해 말 46억원에서 크게 늘었다.
뉴로메카 손실 확대
뉴로메카의 3분기 매출은 27억8000만원으로 전년 44억7000만원에서 줄었고 분기 매출총이익은 1억2000만원에 그쳤다. 영업손실은 70억원으로 두 배가 됐다. 9개월 금융비용 247억원이 더해져 순손실은 376억원으로 2025년 연간 220억원, 2024년 168억원을 모두 웃돌았다. 자본총계는 지난해 말 139억원에서 1046억원으로 늘었다.
큐렉소는 3분기 매출이 147억원으로 14.4% 줄고 영업손실 18억8000만원을 냈다. 9개월 매출은 545억원으로 1.4% 늘었다.
MEKAWIRE 분석
국내 로봇 상장사의 매출은 이제 협동로봇 경기가 아니라 반도체와 AI 설비투자 흐름을 따른다.
라온은 팹, 마키나락스는 제조 AI 프로젝트 수요를 탔다. 뉴로메카와 큐렉소는 완제품 판매 의존도가 높아 중국산 협동로봇의 가격 공세와 병원 예산 영향을 받는다. 반론은 기저효과다. 마키나락스와 라온의 전년 분기 규모가 작았다. 레인보우로보틱스와 두산로보틱스 3분기 보고서에서도 같은 흐름이 나타나는지, 그리고 뉴로메카가 새로 확보한 자본을 중국 합작법인과 포스코 로봇 파운드리에 어떻게 쓰는지가 다음 확인 지점이다.
- 259억원, 99.7% 증가
- 72억3000만원, 전년의 3.1배
- 27억8000만원, 37.9% 감소
- 18억8000만원 손실, 전년 3억4000만원 이익
- 376억원, 2025년 연간 220억원 초과
- 잠정 영업이익 54억4000만원(별도), 연결 50억2000만원
- DART 분기보고서, 11월 13일
매일 아침 8시, 로봇 산업 1면을 텔레그램으로
주요 기사와 신규 투자, 인수, 제휴를 한 장에 담아 보냅니다. 관심 기업 소식은 들어오는 대로 알립니다.
왜 중요한가
The filings show sharply diverging revenue trends: Raon grew 99.7% to KRW 25.9bn and MakinaRocks reached KRW 7.23bn, 3.1 times a year earlier, while Neuromeka fell 37.9% to KRW 2.78bn. Curexo moved from KRW 0.34bn operating profit to a KRW 1.88bn operating loss. Investors should assess each business separately because these companies serve different markets.
경쟁사 비교
Neuromeka's collaborative robots overlap with offerings from Rainbow Robotics and Doosan Robotics, but the input provides no rival financial results or market shares. Rainbow's status as a Samsung subsidiary is relevant strategic context, although no resulting orders are disclosed here. Raon's semiconductor and biotech automation, MakinaRocks' industrial AI and Curexo's medical robots limit the usefulness of treating all four reporting companies as direct competitors.
밸류에이션 맥락
The input supplies no market capitalizations, disclosed valuations or valuation estimates, so revenue growth alone cannot establish relative investment value. Share prices, share counts and comparable financial metrics are missing. For earnings comparisons, Raon's preliminary nine-month operating profit of KRW 5.44bn was on a separate basis, versus KRW 5.02bn consolidated; these figures should not be treated as interchangeable.
근거가 된 연구
The supplied title Safety Standards and Deployment Patterns of Collaborative Robots in Korean SMEs is relevant to cobot deployment, but no findings are provided. DexStitch concerns dexterous skills learned from human videos; the input establishes no connection to these companies' financial results.
공급망 파급
Raon supplies wafer transfer robots for semiconductor equipment, while MakinaRocks sells AI software to manufacturers and defence customers. Neuromeka supplies cobots and automation systems, and Curexo supplies surgical and rehabilitation robots. Supplier identities, component sourcing, inventory, production capacity and delivery lead times are missing, preventing a grounded assessment of supply constraints.
지켜볼 신호
Watch whether Raon and MakinaRocks sustain revenue growth and whether that growth translates into consolidated operating profit and cash generation. For Neuromeka, track liquidity and financing after its KRW 37.6bn nine-month net loss, alongside the outcome of the April 24 rights offering. Curexo's next operating result will help show whether its Q3 loss persists; the input gives no explanation for the reversal.
애널리스트 시각
These results support selective analysis rather than a single Korean robotics growth thesis: revenue momentum differs sharply, and the companies have distinct business models. Neuromeka warrants closer balance-sheet scrutiny because its nine-month net loss already exceeds FY2025's KRW 22.0bn loss. Cash balances, debt, cash flow and order backlogs are missing, so the filings summarized here cannot establish funding runway or recovery prospects.
따져봐야 할 질문
What drove Raon's and MakinaRocks' revenue increases, and how much came from repeat customers or recurring contracts? What are Neuromeka's cash balance, cash burn and rights-offering proceeds, and what caused Curexo's operating reversal?