Mech-Mind raises HK$2.35 billion at the top of its range as Hong Kong retail demand for the 3D vision supplier hits 3,835 times
Mech-Mind Robotics Technologies priced its Hong Kong listing at HK$101.70 per H share, the top of its HK$95.30 to HK$101.70 range, raising gross proceeds of HK$2,353.4 million before any over-allotment, according to its allotment results announcement.
The Hong Kong public tranche was subscribed 3,835.36 times and the international tranche 13.39 times, and dealings in stock code 09615 were set to begin at 9:00 a.m. on September 1, 2026.
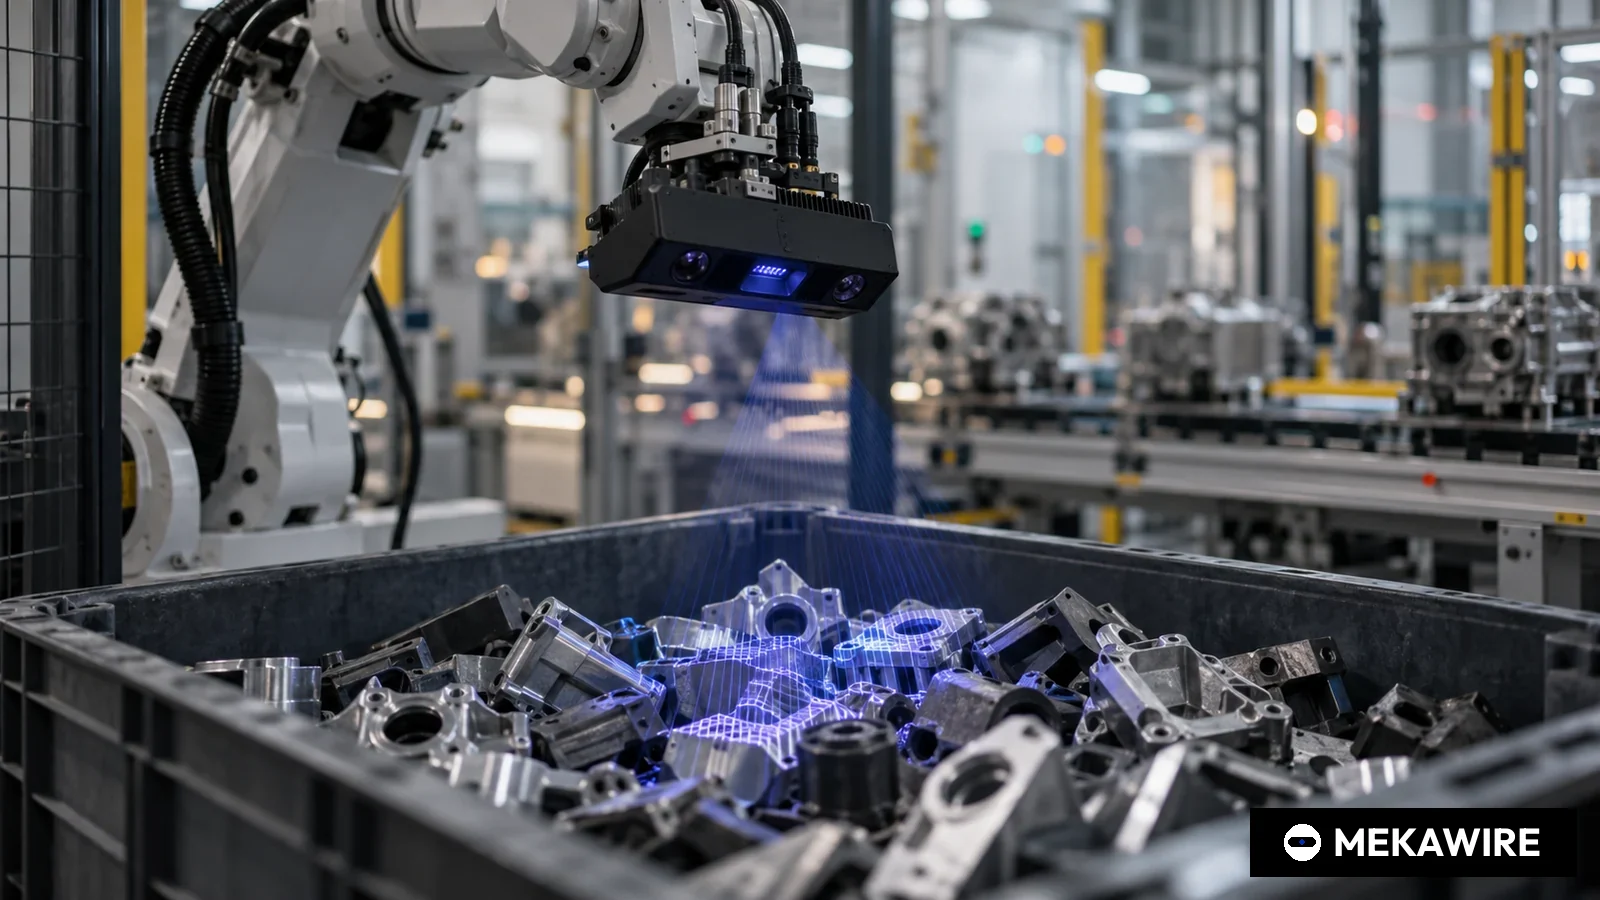
Mech-Mind Robotics Technologies, the Chinese maker of industrial 3D cameras and vision software that act as the eyes of factory robots, sold 23,140,590 new H shares at HK$101.70 each in its Hong Kong initial public offering, the top of an indicated range of HK$95.30 to HK$101.70, the company said in its final offer price and allotment results announcement dated August 31, 2026. Gross proceeds came to HK$2,353.4 million and net proceeds to HK$2,200.2 million after estimated listing expenses of HK$153.2 million. The company said dealings in its H shares, stock code 09615 and short name MECH-MIND ROBOT, were expected to begin at 9:00 a.m. Hong Kong time on Tuesday, September 1, 2026.
Demand came overwhelmingly from Hong Kong retail investors. The announcement shows 252,461 valid applications for a public tranche that was initially 1,157,040 shares, a subscription level of 3,835.36 times. That triggered the full claw-back, moving 3,471,090 shares from the international book and lifting the retail slice to 4,628,130 shares, or 20.00% of the offer. The international offering was 13.39 times subscribed across 130 placees and ended at 18,512,460 shares. CLSA, the stabilizing manager, over-allocated 3,471,060 shares, which can be covered by the over-allotment option or by market purchases until the stabilization period ends on September 26, 2026.
Nine cornerstone investors took 14,351,310 shares, or 62.02% of the offer before any over-allotment. Baillie Gifford was the largest with 4,629,480 shares (20.01% of the offer), followed by Taikang Life with 3,086,310. Invus, Jane Street, Ghisallo and Ruihua took 1,157,370 shares each, NGS Super Fund 771,570, E Fund 771,540 and Golden Link 462,930. At the offer price, the cornerstone tickets add up to about HK$1,459.5 million, a MEKAWIRE calculation from the disclosed share counts. The announcement identifies Golden Link as a subsidiary of a Mech-Mind customer, and lists DAIDO Co., Ltd., the shareholder of another customer, as an international placee with 229,980 shares.
The company listed under Chapter 18C of the Hong Kong Listing Rules, the regime for specialist technology companies that cannot meet the standard profit, revenue or cash-flow tests of Rule 8.05. Based on the offer price and 125,011,050 shares in issue after the offering, the company stated an expected market capitalisation of HK$12,713.6 million at listing, before the over-allotment. China Securities (International) Corporate Finance and CITIC Securities (Hong Kong) were the joint sponsors.
- Mech-Mind Robotics
- 09615
- 2026-09-01
- 101.7
- 2353.4
- 3835.36
- 13.39
- Geek+
- 02590
- 2025-07-09
- 16.8
- 2711.62
- 133.62
- 30.17
- Huayan Robotics
- 01021
- 2026-03-30
- 17
- 1579.34
- 5059.38
- 16.65
- Estun Automation
- 02715
- 2026-03-09
- 15.36
- 1486.54
- 19.67
- 3.34
- Excelland Robotics
- 03231
- 2026-09-09
- 14.45
- 650.2
- 140.02
- 0.99
- Dobot
- 02432
- 2024-12-23
- 18.8
- 752
- 9.25
- 2.64
All figures from each issuer's final offer price and allotment results announcement on HKEXnews; gross proceeds before any over-allotment exercise; Geek+ subscription levels before its offer size adjustment option. Figures disclosed, not estimated.
As of Oct 3, 2026
Mech-Mind was founded in September 2016 by Shao Tianlan, now chairperson and chief executive, with co-founders Fu Ao and Ding Youshuang. Its registered headquarters is in the Xiong'an New Area in Hebei province. The prospectus describes the company as a supplier of intelligent robot components: Mech-Eye industrial 3D cameras bundled with its Mech-Vision, Mech-Viz and Mech-DLK software for robotic guidance, Mech-Eye 3D laser profilers with Mech-MSR software for inspection and measurement, and two early-stage products, the Mech-GPT large multimodal model and Mech-Hand, a five-finger dexterous end-effector. Most sales go through system integrators, which accounted for 81.5% of revenue in 2025.
The prospectus shows revenue rising from RMB180.8 million in 2023 to RMB268.8 million in 2024 and RMB388.8 million in 2025, and to RMB106.9 million in the first quarter of 2026 from RMB61.8 million a year earlier. Gross margin widened from 39.1% to 64.6% over the three years. Units sold rose from 3,690 to 6,103 and then 8,669, with 2,485 in the first quarter of 2026. The loss for 2025 was RMB360.2 million, wider than 2024's RMB283.3 million, but the company attributes the increase mainly to a RMB209.2 million change in the carrying amount of redemption liabilities tied to its Series D and pre-IPO rounds. Its non-IFRS adjusted loss narrowed from RMB334.4 million in 2023 to RMB109.0 million in 2025.
- Revenue (RMB m)
- 180.8
- 268.8
- 388.8
- 106.9
- Gross margin (%)
- 39.1
- 51.1
- 64.6
- 64.8
- Loss for the period (RMB m)
- -401
- -283.3
- -360.2
- -56.8
- Adjusted loss, non-IFRS (RMB m)
- -334.4
- -214.3
- -109
- -33.5
- Units sold
- 3690
- 6103
- 8669
- 2485
- Overseas revenue (RMB m)
- 58.6
- 97.7
- 195.5
- 47.1
Source: Mech-Mind prospectus dated August 24, 2026 (Accountants' Report summary and business section). Adjusted loss excludes changes in redemption liabilities, share-based pay and listing expenses as defined by the company. Figures disclosed, not estimated.
As of Oct 3, 2026
Overseas sales are the story behind the margin. Overseas revenue reached RMB195.5 million in 2025, 50.3% of the total, against RMB97.7 million in 2024. The prospectus puts the 2025 overseas gross margin at 79.2% against 49.8% in mainland China, and says a single substantial order from a U.S. customer lifted the overseas share that year and should not be read as a trend. Average selling prices diverge sharply: RMB94,300 per unit overseas in 2025 against RMB29,300 in mainland China, where the company cut prices on mature models to stay competitive. The largest customer took 15.0% of 2025 revenue and the top five 39.3%.
On competition, the prospectus cites a report by China Insights Industry Consultancy (CIC) that ranks Mech-Mind first in what it calls the global AI plus 3D vision-guided robot component market in 2025, with revenue of about RMB389 million and a share of about 22.1%, and first by shipment volume. The next four players are not named. CIC describes them as two Tokyo-listed Japanese groups founded in 1958 and 1974, a Nasdaq-listed U.S. machine vision company founded in 1981, and a private Chinese 3D vision firm founded in 2018, with estimated shares between about 8.5% and 2.8%. The top five held about 45.4% of a segment with more than 20 players.
The company plans to spend the net proceeds, pro rata at the final price, on research and development (31.8%), new products and application scenarios (25.2%), global expansion and commercialization (29.4%), production capacity and efficiency (5.0%) and working capital (8.6%). The prospectus says existing capacity is about 18,000 units a year and outlines a progressive build-out to about 60,000 units by 2031. It also warns that the company expects a net loss for 2026, and that heavy selling and R&D spending will continue.
There are open questions. Pricing at home is falling while the overseas margin rests in part on one U.S. order. Customer concentration is rising. The first-quarter 2026 cash burn rate jumped to RMB24.3 million a month from RMB10.3 million a year earlier, which the company attributes to advance purchases of memory chips. Lock-ups set the calendar: cornerstone shares are free from February 28, 2027, while PRC law bars all existing shareholders, including the Chapter 18C pathfinder investors Hanchen (11.11%) and Qiming Rongke (6.02%) and the founders, from selling until August 31, 2027.
MEKAWIRE analysis
Mech-Mind has become the public market's cleanest bet on robot perception as a standard component, but its premium rests on overseas pricing that one customer flattered in 2025.
The evidence for the thesis is in the prospectus. Gross margin rose 25.5 percentage points in two years as volume scaled, adjusted losses fell by two thirds, and the company is the only one of the six Hong Kong robotics listings in our table that sells a sensor and software layer rather than a robot. The CIC ranking puts it ahead of established Japanese and U.S. vision suppliers in a narrow but growing segment, and more than 29,000 units deployed gives it a training data base for its deep learning tools that newer rivals lack.
The strongest counter-argument is that the gross margin and the overseas mix were both lifted by a single U.S. order in 2025 that the company itself says is not indicative. Strip that out and the business looks closer to its mainland profile, where average prices fell from RMB43,300 in 2023 to RMB29,300 in 2025 and margins sit near 50%. A HK$12.7 billion market value on 2025 revenue of RMB388.8 million leaves little room for a reversion.
Bull case: overseas orders broaden beyond one customer, Mech-GPT and Mech-Hand turn the company from a camera seller into a perception and manipulation stack for humanoid and mobile manipulators, and the proceeds fund the jump to 60,000 units of capacity. Losses close as operating leverage holds.
Bear case: Chinese price competition spreads to export markets, robot makers integrate their own depth sensing, and the 2025 margin proves a peak. With cornerstone lock-ups ending in February 2027 and all pre-IPO holders free from September 2027, the shareholder base could turn over before the business proves itself.
Signals to watch:
- The over-allotment and stabilization outcome announced after September 26, 2026, which will show whether the offer grew by up to 3,471,060 shares.
- Full-year 2026 results, due by March 31, 2027, for the overseas revenue share and whether gross margin holds near 64% without a repeat U.S. order.
- February 28, 2027, when cornerstone lock-ups end, and August 31, 2027, the last locked day for founders, pathfinder investors and other pre-IPO shareholders.
- 09615 (HKEX Main Board, Chapter 18C)
- 9 investors, 14,351,310 shares, 62.02% of offer
- 23,140,590 H shares (3,471,060 over-allocated)
- September 1, 2026, 9:00 a.m. HKT
- HK$101.70, top of HK$95.30 to HK$101.70 range
- RMB388.8m / RMB360.2m
- HK$2,353.4m / HK$2,200.2m
- 13.39x subscribed, 130 placees
- 3,835.36x subscribed, 252,461 valid applications
- HK$12,713.6m on 125,011,050 shares
Why it matters
Mech-Mind is the first company whose core product is robot perception, rather than a finished robot, to list on Hong Kong's Chapter 18C board in the current wave of robotics IPOs. Its pricing at the top of the range, a 3,835-times retail book and a cornerstone book led by Baillie Gifford show that investors are willing to pay for the component layer of embodied AI, not only for humanoid or cobot assemblers.
The proceeds of HK$2,200.2 million net are large against the company's balance sheet. Cash and cash equivalents stood at RMB345.9 million on March 31, 2026, and operating cash outflow was RMB107.4 million in 2025. The listing also converts redemption liabilities to equity, turning net liabilities of RMB2,544.8 million at March 31, 2026 into net assets, according to the prospectus. The IPO therefore resets the company's financial position rather than topping up a healthy balance sheet.
Rival analysis
The prospectus lists four unnamed competitors behind Mech-Mind in the AI plus 3D vision-guided robot component segment, with estimated 2025 revenue of about RMB150 million, RMB130 million, RMB80 million and RMB50 million. Two are long-established Tokyo-listed groups, one a Nasdaq-listed U.S. machine vision house and one a private Chinese firm founded in 2018. For the incumbents this segment is a sliver of much larger vision and automation businesses, which means Mech-Mind's lead is real in a niche but not a sign that it outsells them overall.
Among Hong Kong peers, Mech-Mind sits upstream of Estun, Dobot and Huayan, whose arms its cameras guide, and alongside logistics automation names such as Geek+ that need depalletizing and picking vision. That makes the listed peers potential customers as much as comparables. The more direct competitive threat is vertical integration: robot makers building their own depth sensing and AI planning, which would compress the market for a stand-alone eye-brain layer.
Valuation context
At HK$101.70 the company stated a market capitalisation of HK$12,713.6 million on 125,011,050 shares before the over-allotment. Against 2025 revenue of RMB388.8 million, that is a high multiple by industrial automation standards even after allowing for the currency difference, and it implies investors are pricing several more years of revenue growth near the 46.6% compound rate the company reported for 2023 to 2025.
Gross proceeds of HK$2,353.4 million trail Geek+'s HK$2,711.62 million but exceed every 2026 robotics listing in our table, including Huayan's HK$1,579.34 million and Estun's HK$1,486.54 million. The international book at 13.39 times was thinner than Geek+'s 30.17 times and Huayan's 16.65 times, so the headline retail number overstates the depth of institutional demand. If the over-allotment is fully exercised, a further 3,471,060 shares would raise about HK$353.0 million more at the offer price, a MEKAWIRE calculation.
Supply-chain implications
The prospectus names optical components such as camera sensors, lenses and laser projectors, embedded processors and communication modules, and precision mechanical parts as its main purchases, most of them sourced in China. Its five largest suppliers took 24.8% of purchases in 2025 and the largest just 6.3%, which suggests limited single-supplier dependence.
Memory is the pinch point. The company says lead times for certain memory chips lengthened from late 2025 on AI-related demand, and it pre-bought inventory in the first quarter of 2026, which pushed its monthly cash burn to RMB24.3 million. Capacity is the other constraint: about 18,000 units today against a plan for about 60,000 by 2031, funded in part by the 5.0% of proceeds earmarked for production.
Signals to watch
The stabilization period ended on September 26, 2026; the company must announce whether the over-allotment option was exercised and how many shares were bought back in the market. That filing will show how the stock traded against the HK$101.70 offer price in its first month.
The 2026 annual results, due by March 31, 2027, are the first full-year test of the overseas mix without the 2025 U.S. order. Watch the overseas revenue share against 50.3% in 2025, the gross margin against 64.6%, and any naming of large customers. The cornerstone lock-up expiry on February 28, 2027 and the end of the PRC lock-up for all pre-IPO holders on August 31, 2027 are the two supply events for the stock.
Analyst view
Thesis: Mech-Mind is the scale leader in a narrow, fast-growing robot component segment, and the IPO gives it the balance sheet to stay there, but the valuation assumes its 2025 margin and overseas mix are durable when the company itself says part of both came from one order.
Confidence: medium. The financial data is audited and the market ranking comes from an independent consultant commissioned for the prospectus, which supports the scale argument. Confidence is not high because the competitor set is anonymised, the U.S. order's size is not disclosed, and the company has guided to a 2026 net loss with no profitability date.
Questions you should be asking
How large was the single U.S. order in 2025, and has the customer placed repeat orders in 2026? Who are the four anonymised competitors, and how does Mech-Mind's pricing compare outside China?
How much of Mech-GPT and Mech-Hand revenue is recurring, and when does the company expect either to move from early-stage to commercial scale? Will the over-allotment have been exercised in full, and at what level did the stabilizing manager support the price?