Geek+ raises HK$2.71 billion as the first listed warehouse AMR maker, with Hong Kong retail demand covered 133 times
Beijing Geekplus Technology began trading in Hong Kong on July 9, 2025 under code 2590 after selling 161,405,800 H shares at HK$16.80, raising gross proceeds of HK$2,711.62 million. The retail tranche was subscribed 133.62 times and the international book 30.17 times, while four cornerstone investors led by Xiong'an Intelligent Robotics took about 26% of the deal.
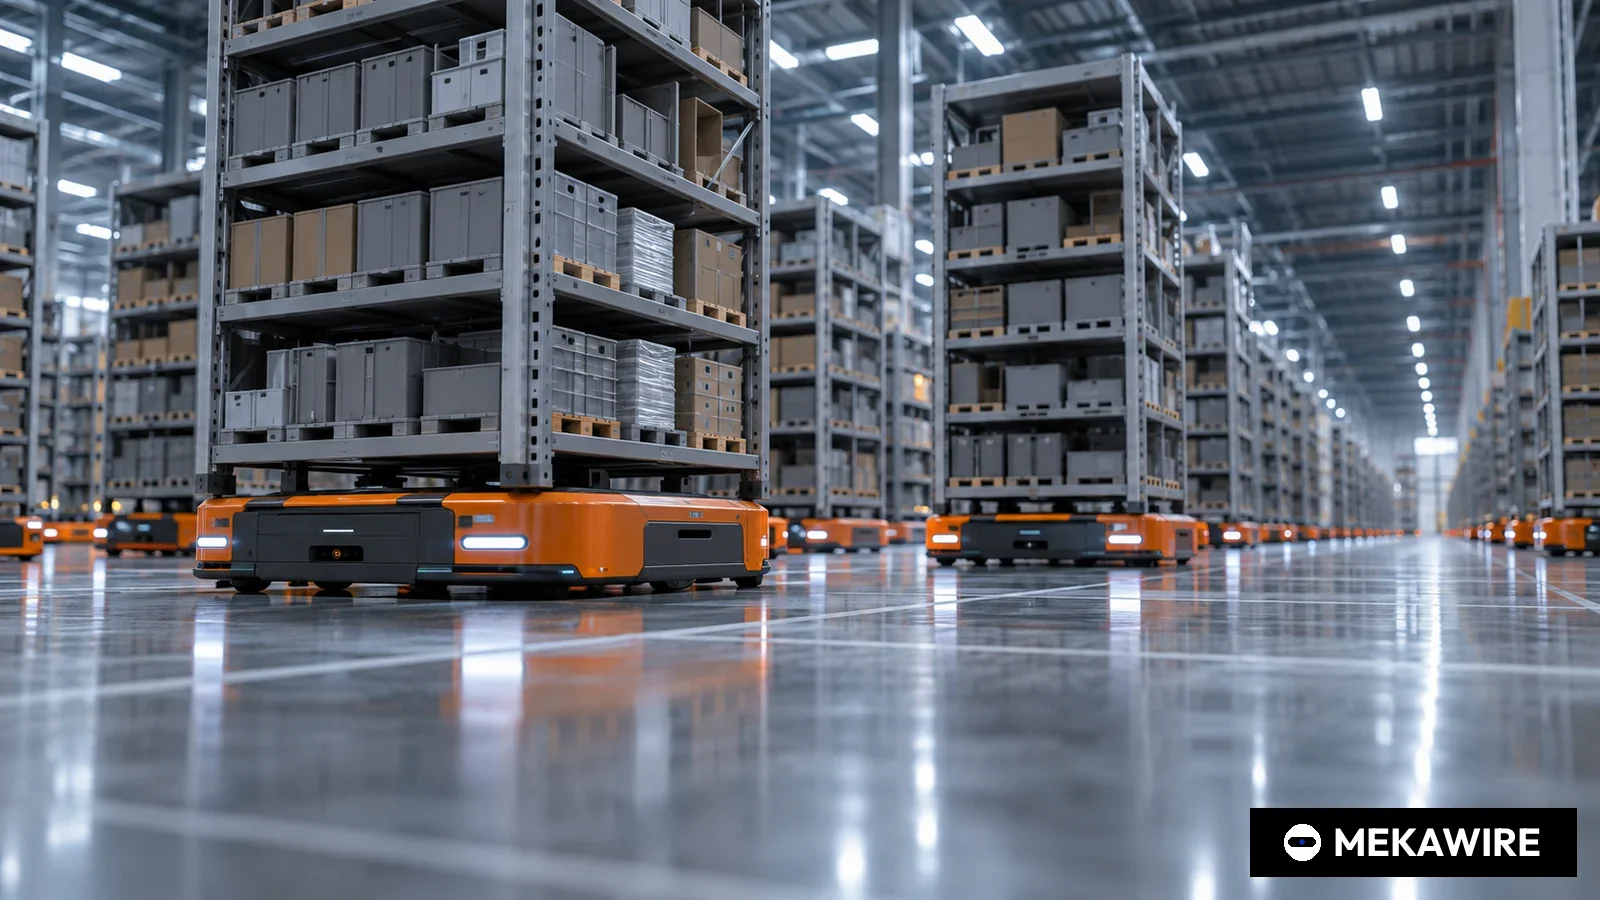
Beijing Geekplus Technology, the warehouse robot maker known as Geek+, began trading on the Main Board of the Hong Kong Stock Exchange at 9:00 a.m. on July 9, 2025 under stock code 2590. It priced its H shares at HK$16.80 and raised gross proceeds of HK$2,711.62 million, according to the final offer price and allotment results announcement it filed with HKEX the day before. The company describes itself as the world's first publicly listed business built around autonomous mobile robots (AMRs) for warehouses.
The offering
The global offering comprised 161,405,800 H shares after Geek+ fully exercised an offer size adjustment option that added 21,052,800 shares to the base deal. Net proceeds came to HK$2,545.00 million, the allotment announcement said. The Hong Kong public offering drew 94,292 valid applications and was subscribed 133.62 times, which triggered a reallocation that lifted the retail tranche to 70,176,600 shares, or 43.48% of the deal. The international placing of 91,229,200 shares was covered 30.17 times. Shares trade in board lots of 200.
The filing shows 1,320,617,198 shares in issue at listing before any exercise of the over-allotment option, of which 814,075,882 H shares, about 61.64%, count toward the public float. At the offer price that share count implies a market value of about HK$22.19 billion, a MEKAWIRE calculation (1,320,617,198 shares multiplied by HK$16.80). The joint global coordinators hold an over-allotment option over up to 24,210,800 further H shares, and the stabilisation period ends on the 30th day after the last day for lodging Hong Kong applications.
Who bought
Four cornerstone investors took fixed allocations, the filing shows. Xiong'an Intelligent Robotics (雄安智能機器人有限公司) received 19,300,000 shares; Arc Avenue Asset Management received 11,681,200; Eastspring Investments (Singapore) received 7,008,600; and a Hong Kong company registered as 香港億格有限公司 received 4,672,400. Together that is 42,662,200 shares, or 26.4% of the offering and about HK$716.72 million at the offer price, by MEKAWIRE calculation. The cornerstone lock-up runs to January 8, 2026, while lock-ups on a group of existing shareholders and pre-IPO investors run to July 8, 2026.
The business behind the listing
In its listing-day release Geek+ said research firm China Insights Consultancy (CIC) has ranked it the largest provider of warehouse fulfilment AMRs worldwide for six consecutive years. It reported 2024 revenue of RMB2.409 billion and a 45% compound annual growth rate from 2021 to 2024. Annual contracted order value rose to RMB3.14 billion in 2024 from RMB1.59 billion in 2021, and gross profit grew to RMB840 million from RMB80 million over the same span, with a 2024 gross margin of 34.8%. The company is not yet profitable on its own adjusted measures. It reported a 2024 adjusted EBITDA loss of RMB25 million and an adjusted net loss margin of 3.8%.
Geek+ says it serves more than 800 enterprise customers in over 40 countries and regions, mainly third-party logistics operators, retailers and e-commerce groups. Its overall customer repurchase rate in 2024 was 74.6%, rising to 84.3% among key customers, the company said. Founder, chairman and chief executive Zheng Yong said the listing gives the company "twin engines of capital and technology".
The core product idea is goods-to-person picking. Instead of workers walking aisles, small robots lift shelves or totes and bring them to a picking station, while software decides which robot fetches which item in which order. Geek+ says its system can coordinate more than 5,000 devices at the same time inside a single warehouse. That orchestration layer, rather than the robot chassis, is where most of the engineering value sits, because throughput depends on traffic control, battery scheduling and slotting decisions made every second.
Competitors and comparables
Geek+ competes with Chinese private rivals Hai Robotics, which raised US$200 million in combined Series C and D funding in 2021, and Quicktron, whose Series C+ round in 2021 was led by Germany's KION Group. In the United States, Locus Robotics reached a US$1 billion post-money valuation in its US$150 million Series E in 2021. Listed comparables include Oslo-traded AutoStore and Nasdaq-traded Symbotic, both of which sell storage and retrieval systems into the same distribution centres.
Geek+ said the deal is the largest H-share IPO by a robotics company to date. Its gross proceeds were 2.67 times those of UBTech Robotics in December 2023 and 3.61 times those of Dobot in December 2024, by MEKAWIRE calculation from each company's allotment results. Horizon Robotics raised HK$5,407 million in October 2024, but it is not an H-share issuer and sells driving-assistance chips rather than robots. The company itself said the deal ranked in the top three Hong Kong listings of 2025 by international coverage and was the largest technology IPO of the year in Hong Kong that was not a dual A+H listing.
- Geek+ (Beijing Geekplus Technology)
- 2590
- 2025-07-09
- 16.8
- 161,405,800
- 2711.62
- 133.62
- 30.17
- 1
- UBTech Robotics
- 9880
- 2023-12-29
- 90
- 11,282,000
- 1015.38
- 5.16
- 2.16
- 2.67
- Dobot
- 2432
- 2024-12-23
- 18.8
- 40,000,000
- 752
- 9.25
- 2.64
- 3.61
- Horizon Robotics
- 9660
- 2024-10-24
- 3.99
- 1,355,106,600
- 5407
- 33.83
- 13.81
- 0.5
Source: each issuer's final offer price and allotment results announcement on HKEXnews; figures before any over-allotment exercise, disclosed not estimated. Last column is a MEKAWIRE calculation: Geek+ gross proceeds / peer gross proceeds. Horizon Robotics is not an H-share issuer and sells driving-assistance chips.
As of Oct 1, 2026
Risks and open questions
The listing documents leave several questions. The company has not yet shown a full year of positive adjusted EBITDA, and the allotment announcement does not restate how much of the net proceeds will go to research, overseas expansion or working capital. The headline ranking rests on CIC, a consultancy commissioned for the prospectus. Warehouse automation buyers also face long sales cycles, so contracted orders do not convert to revenue in the same year, a gap that shows in 2024 orders running ahead of revenue.
What to watch
The first hard test comes when the stabilisation period ends in early August 2025, when the over-allotment decision will show whether the coordinators needed to support the price. Under Hong Kong rules Geek+ must publish its first interim results as a listed company by August 31, 2025. The cornerstone lock-up expires on January 8, 2026.
MEKAWIRE analysis
Hong Kong investors priced Geek+ as a logistics software platform with near-breakeven economics, and that template will decide which Chinese robot makers can list next.
The evidence sits in the book. A retail tranche covered 133.62 times and an international book covered 30.17 times are far above UBTech's 5.16 and 2.16 times in 2023 and Dobot's 9.25 and 2.64 times in 2024. The difference is not the robot. Geek+ arrived with RMB2.409 billion of revenue, a 34.8% gross margin and an adjusted EBITDA loss of only RMB25 million, which lets investors underwrite a path to profit rather than a story about humanoids.
The strongest counter-argument is that oversubscription in a small retail tranche is a thin signal. The four cornerstones took 26.4% of the shares on fixed allocations, so a quarter of the deal was committed before price discovery, and the stabilisation period has not yet run its course.
Bull case: overseas customers keep reordering at the 84.3% rate the company reports for key accounts, orders keep running ahead of revenue, and the fleet software becomes the reason customers stay. A first adjusted profit would let the shares trade against software multiples and open the door for Hai Robotics and Quicktron to follow.
Bear case: price competition among Chinese AMR suppliers compresses the gross margin, trade barriers slow sales into the United States, and post-listing supply from cornerstones in January 2026 and pre-IPO holders in July 2026 weighs on the stock before profits arrive.
Signals to watch:
- Early August 2025: whether the over-allotment option over up to 24,210,800 shares is exercised in full, in part or not at all.
- By August 31, 2025: first interim results, especially gross margin against 34.8% and the sign of adjusted EBITDA.
- January 8, 2026: expiry of the cornerstone lock-up on 42,662,200 shares.
- HKEX Main Board, code 2590, July 9, 2025, 9:00 a.m. HKT
- HK$16.80 per H share
- RMB2.409 billion, gross margin 34.8%
- 4 investors, 42,662,200 shares (26.4%, MEKAWIRE calc.)
- HK$2,545.00 million
- 161,405,800 H shares (incl. 21,052,800 from offer size adjustment)
- HK$2,711.62 million
- 133.62 times subscribed, 94,292 valid applications
- 30.17 times subscribed
- about HK$22.19 billion (MEKAWIRE calc.)
Why it matters
Geek+ is the first company whose main business is warehouse AMRs to reach a public market, so its pricing sets the reference valuation for an entire class of Chinese logistics robot makers that have so far been valued only in private rounds. Hai Robotics and Quicktron, its closest domestic rivals, now have a public comparable against which every future round or listing will be benchmarked.
The deal also shows what Hong Kong's market is willing to fund in 2025. The book was strongest for a company with RMB2.409 billion of revenue and a near-breakeven adjusted EBITDA, not for a pre-revenue humanoid story. That ordering of investor preference is useful for anyone planning a robotics listing in the next 12 months.
Rival analysis
Hai Robotics competes most directly with tote-handling robots aimed at dense storage. Quicktron carries KION Group as a strategic backer, giving it a channel into Dematic's integration business. Locus Robotics in the United States sells collaborative picking robots that work alongside staff in the aisles.
Among listed players, AutoStore's cube storage and Symbotic's large Walmart-centred systems address bigger, more capital-intensive sites. Geek+ sits in between: modular fleets that can be added to existing buildings. Its stated ability to coordinate more than 5,000 devices in one warehouse is the claim rivals will most often challenge in tenders.
Valuation context
At HK$16.80 and 1,320,617,198 shares in issue, the implied market value at listing is about HK$22.19 billion by MEKAWIRE calculation. We do not express that value as a multiple of 2024 revenue of RMB2.409 billion, because doing so would require an estimated exchange rate; readers can apply the rate of their choice.
The gross proceeds of HK$2,711.62 million were 2.67 times UBTech's 2023 IPO and 3.61 times Dobot's 2024 IPO. Horizon Robotics raised HK$5,407 million in 2024, but it designs driving-assistance chips rather than robots.
Supply-chain implications
An AMR fleet is built from commodity drives, batteries, cameras and lidar, most of which Geek+ can source inside China at costs foreign rivals struggle to match. The scarce input is software and site engineering, which is why the company emphasises fleet coordination and repurchase rates.
The more sensitive dependency is on the customer side. More than 40 countries and regions means exposure to tariffs and local content rules, especially for warehouse projects in the United States, where Chinese-made hardware can face additional duties.
Signals to watch
Early August 2025: the over-allotment decision on up to 24,210,800 shares. Full exercise would signal demand held above the offer price after listing.
By August 31, 2025: first interim results. Watch gross margin against the 34.8% reported for 2024, order intake against the RMB3.14 billion annual pace, and whether adjusted EBITDA turns positive.
January 8, 2026 and July 8, 2026: cornerstone and pre-IPO lock-up expiries respectively.
Analyst view
Thesis: Geek+ is being valued as an orchestration platform, and its first two reporting periods as a listed company will decide whether that holds. Confidence: medium. The book quality and margin profile support the thesis, but the company has not yet produced a period of positive adjusted EBITDA under public scrutiny, and a quarter of the deal sits with cornerstones on fixed allocations.
We would raise confidence to high if the interim results show positive adjusted EBITDA with gross margin at or above 34.8%, and lower it if margin falls as the company chases volume overseas.
Questions you should be asking
How much of the HK$2,545.00 million net proceeds will go to overseas sales and service capacity rather than research? The allotment announcement refers back to the prospectus without restating the split.
What share of revenue comes from the largest customers, and how exposed is the order book to US tariff changes? Will Xiong'an Intelligent Robotics, the largest cornerstone, take any role beyond that of a shareholder?